Comments
Unlock

觅信聚合
我的关注
年(甚至可能长达十年)压缩到 1-2 年(实现 80% 以上的陌生环境任务),这是一种显著的前景变化。
Comments
Unlock
原文:
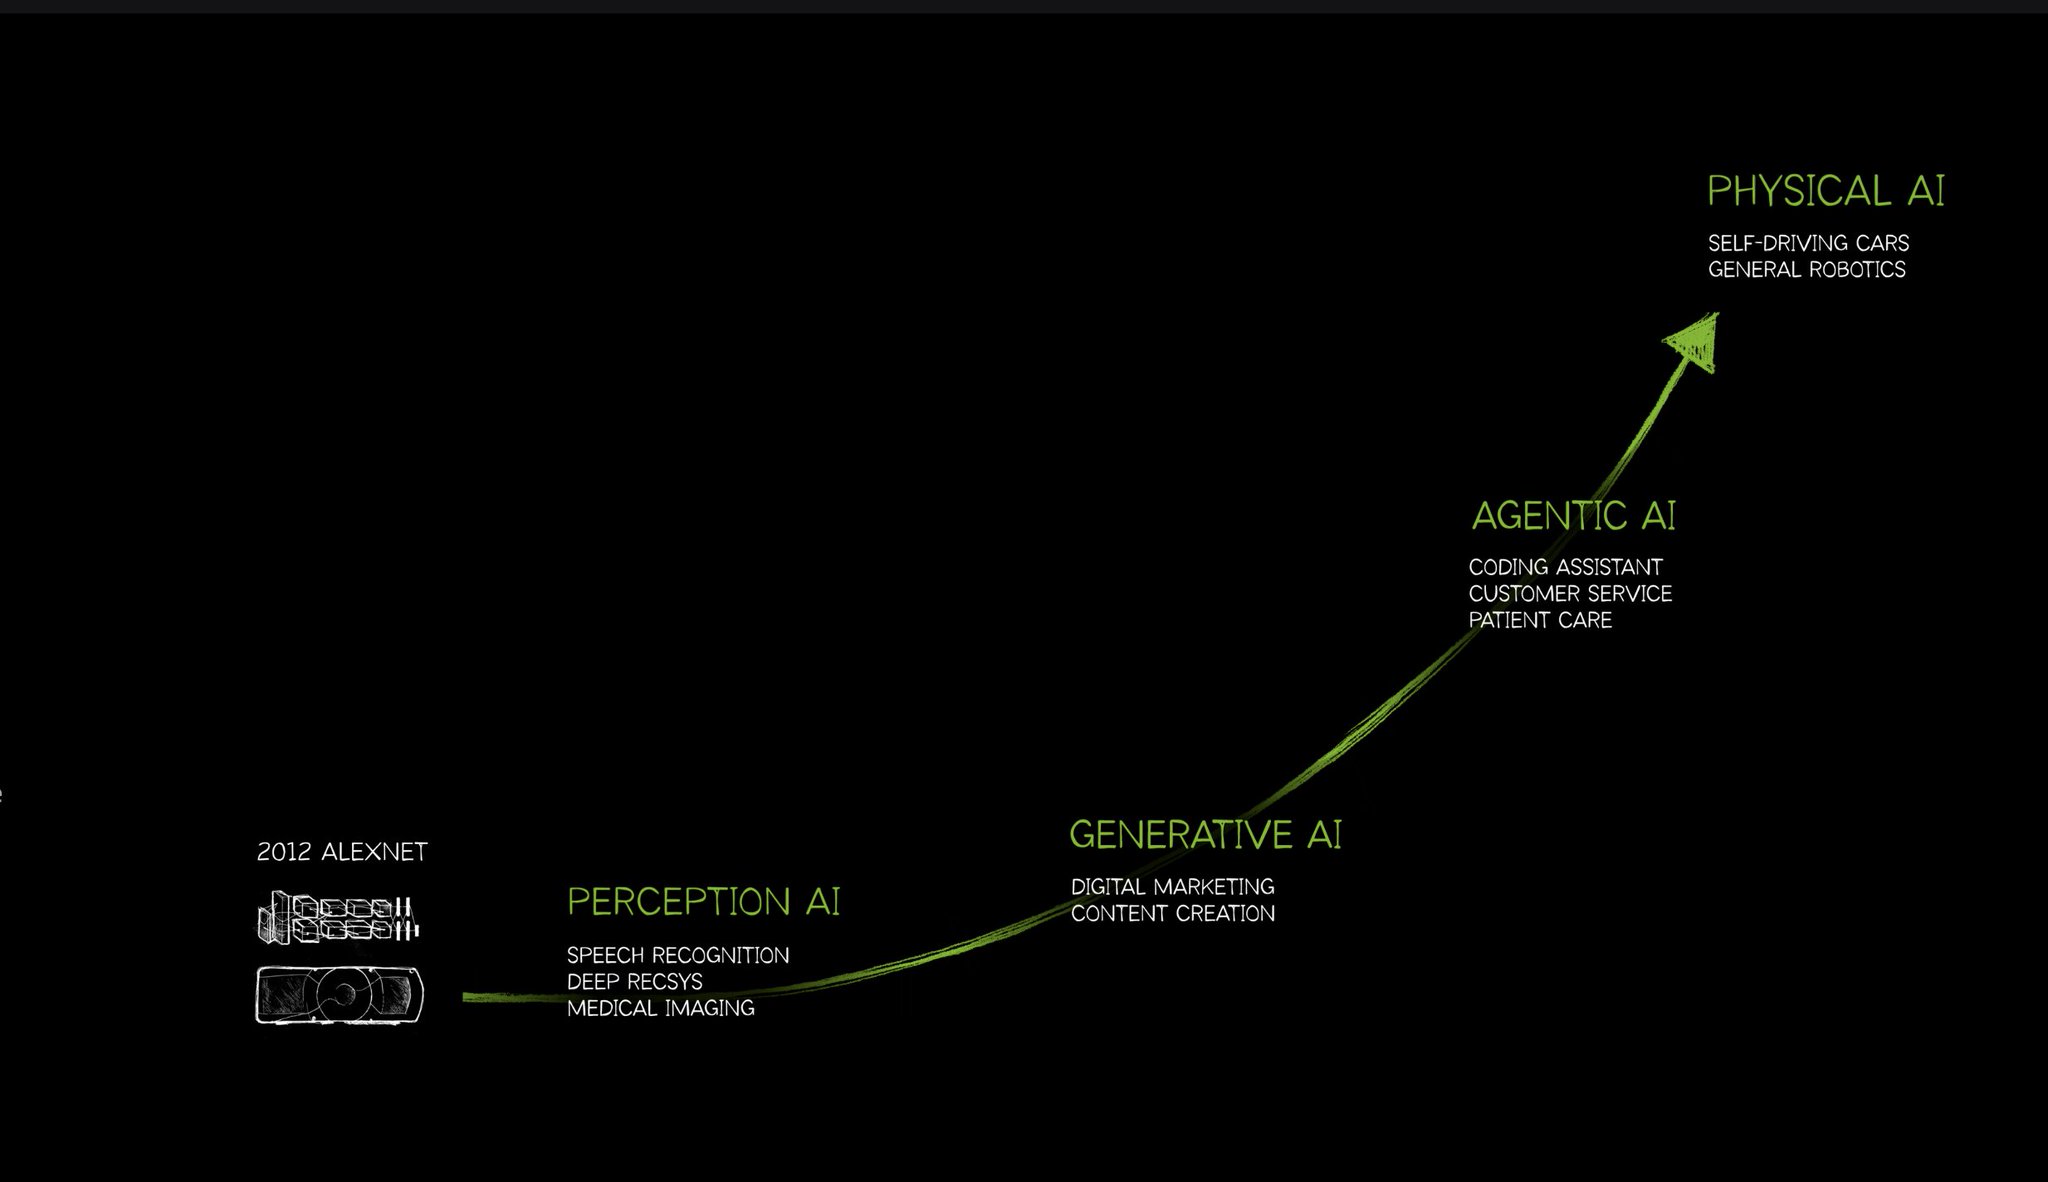
Physical AI + Humanoids are the next progression of AI.
$NVDA CES 2025 projections and Elon's prediction on $TSLA + 1 Billion humanoids in the next decade, seems to be speeding up.
New statement from Unitree CEO after testing GPT-6 on their humanoid program was that:
- In August, before GPT-6's release, Wang said the industry could take two to three years at its fastest pace, or as long as a decade, to reach its "ChatGPT moment"
- Now, OpenAI's GPT-6 model prompted expectations that a breakthrough could happen "within 1 or 2 years"
- He defined that moment as robots being able to complete around 80 per cent of tasks in 80 per cent of unfamiliar environments using voice or text commands.
- "It's possible that, say, a GPT-7 model released next year could directly crack the problems of embodied intelligence"
- "The whole embodied intelligence industry has been shaken up after the release of GPT-6"
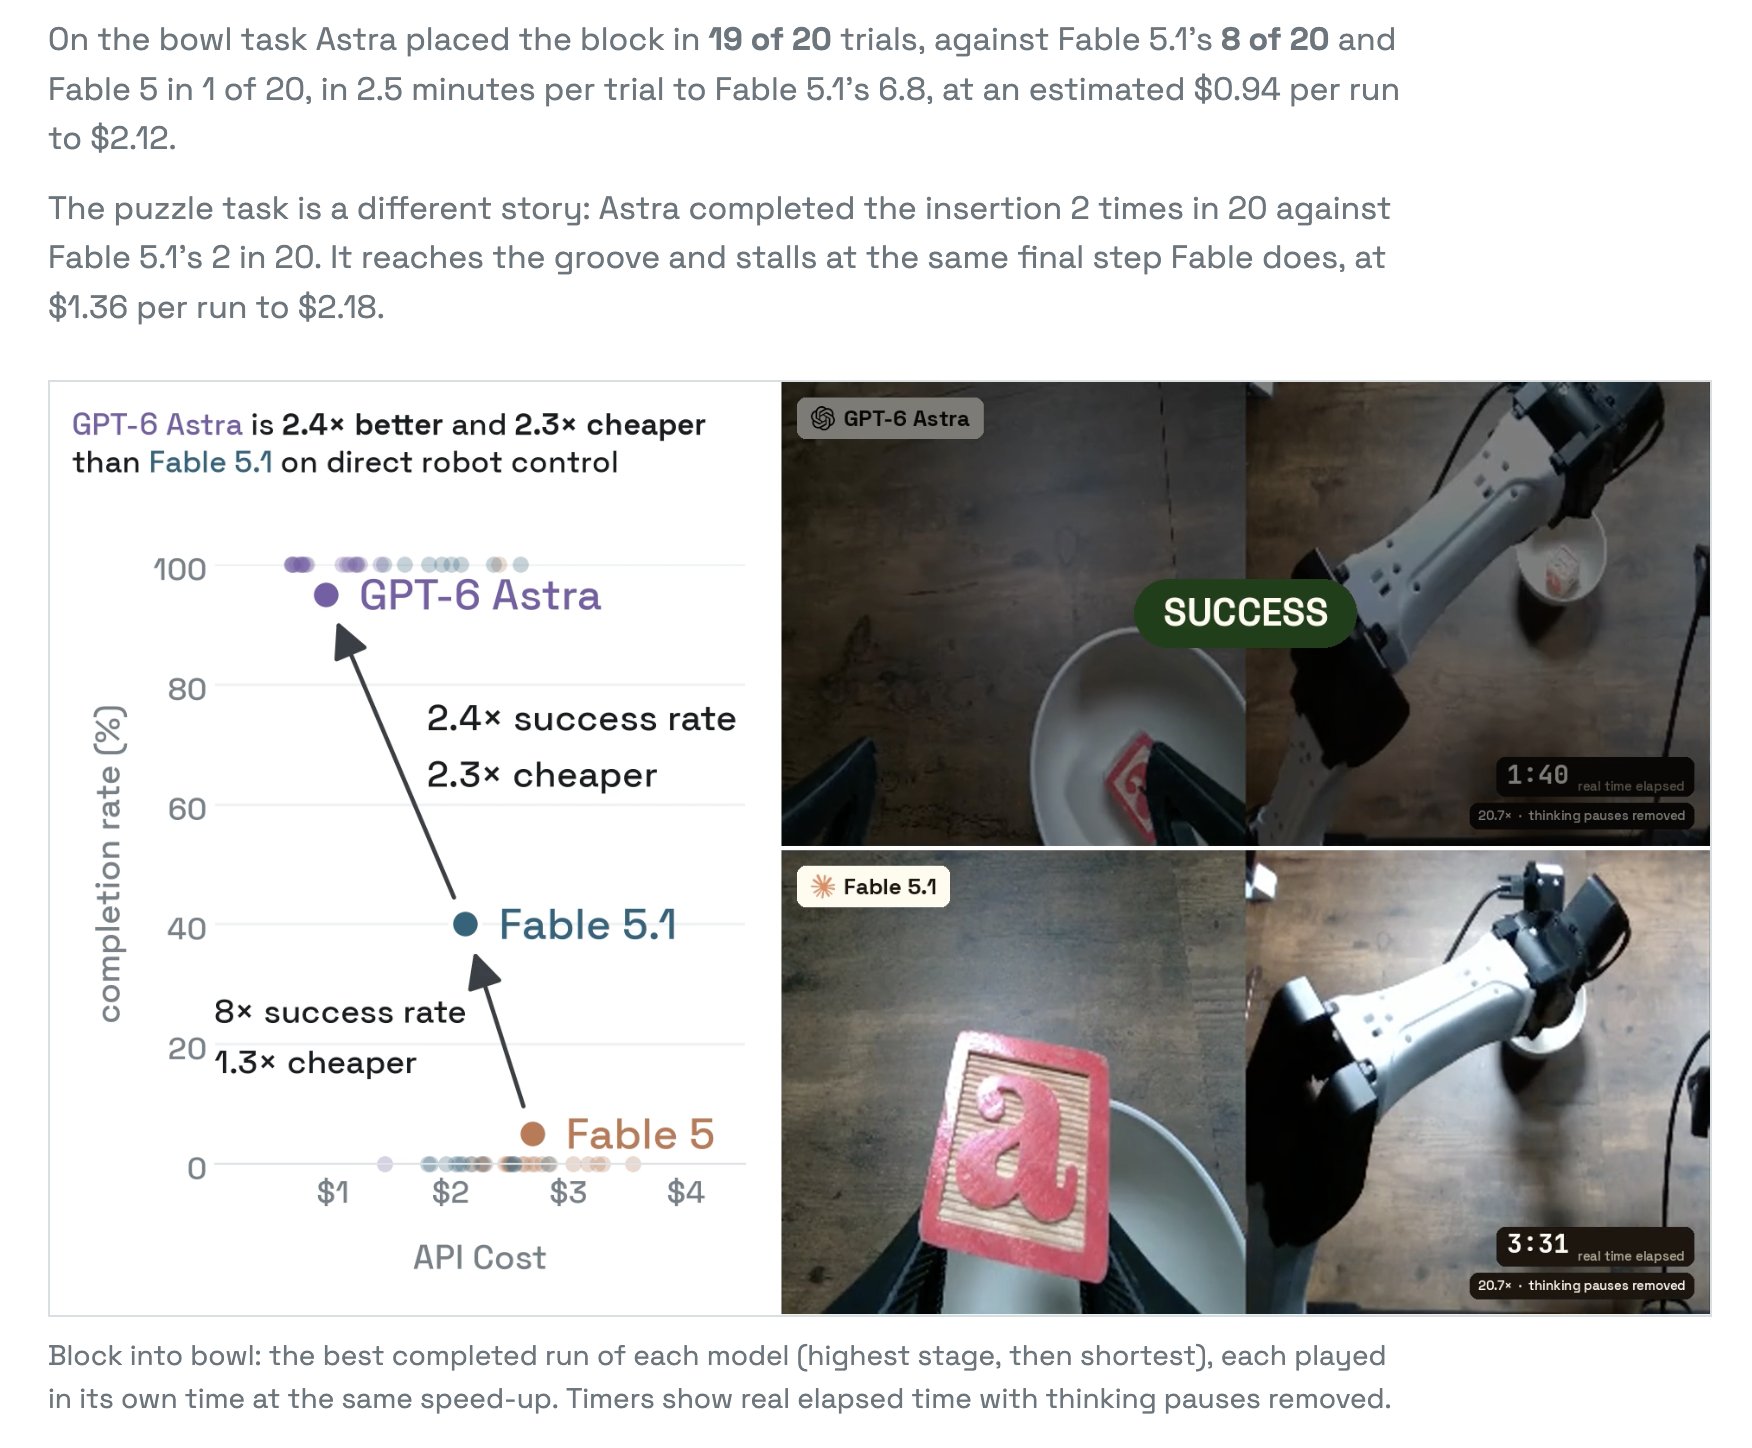
Just looking at some benchmarks on robotic hand manipulation, "On the bowl task Astra placed the block in 19 of 20 trials, against Fable 5.1's 8 of 20".
But for the puzzle task "Astra completed the insertion 2 times in 20 against Fable 5.1's 2 in 20"".. so we're getting there.
But going from 2-3 years (potentially to a decade), and compressing that down to 1 or 2 years (to achieve 80%+ of tasks in unfamiliar environemnts) is a significant change in outlook.
翻译:
实体 AI + 类人机器人是 AI 的下一步发展。
$NVDA 在 CES 2025 的预测以及 Elon 对 $TSLA 的预测——未来十年将有 10 亿类人机器人——似乎在加速。
Unitree CEO 在对其类人机器人项目测试 GPT-6 后的新表述是:
- 8 月,在 GPT-6 发布前,Wang 表示行业最快可能需要两到三年,最慢可能需要十年才能迎来其“ChatGPT 时刻”。
- 现在,OpenAI 的 GPT-6 模型让人们期待突破可能在“一到两年内”出现。
- 他将该时刻定义为机器人能够在 80% 的陌生环境中,通过语音或文字指令完成约 80% 的任务。
- “比如说,明年发布的 GPT-7 模型有可能直接破解具身智能的问题”。
- “GPT-6 发布后,整个具身智能行业都被震动”。
但从机器人手部操作的一些基准来看,“在碗任务中,Astra 在 20 次试验中成功放置块体 19 次,而 Fable 5.1 为 8 次”。
而在拼图任务中,“Astra 在 20 次中完成插入 2 次,Fable 5.1 也是 2 次”……我们正在接近目标。
但从原本的 2-3
Physical AI + Humanoids are the next progression of AI.
$NVDA CES 2025 projections and Elon's prediction on $TSLA + 1 Billion humanoids in the next decade, seems to be speeding up.
New statement from Unitree CEO after testing GPT-6 on their humanoid program was that:
- In August, before GPT-6's release, Wang said the industry could take two to three years at its fastest pace, or as long as a decade, to reach its "ChatGPT moment"
- Now, OpenAI's GPT-6 model prompted expectations that a breakthrough could happen "within 1 or 2 years"
- He defined that moment as robots being able to complete around 80 per cent of tasks in 80 per cent of unfamiliar environments using voice or text commands.
- "It's possible that, say, a GPT-7 model released next year could directly crack the problems of embodied intelligence"
- "The whole embodied intelligence industry has been shaken up after the release of GPT-6"
Just looking at some benchmarks on robotic hand manipulation, "On the bowl task Astra placed the block in 19 of 20 trials, against Fable 5.1's 8 of 20".
But for the puzzle task "Astra completed the insertion 2 times in 20 against Fable 5.1's 2 in 20"".. so we're getting there.
But going from 2-3 years (potentially to a decade), and compressing that down to 1 or 2 years (to achieve 80%+ of tasks in unfamiliar environemnts) is a significant change in outlook.
翻译:
实体 AI + 类人机器人是 AI 的下一步发展。
$NVDA 在 CES 2025 的预测以及 Elon 对 $TSLA 的预测——未来十年将有 10 亿类人机器人——似乎在加速。
Unitree CEO 在对其类人机器人项目测试 GPT-6 后的新表述是:
- 8 月,在 GPT-6 发布前,Wang 表示行业最快可能需要两到三年,最慢可能需要十年才能迎来其“ChatGPT 时刻”。
- 现在,OpenAI 的 GPT-6 模型让人们期待突破可能在“一到两年内”出现。
- 他将该时刻定义为机器人能够在 80% 的陌生环境中,通过语音或文字指令完成约 80% 的任务。
- “比如说,明年发布的 GPT-7 模型有可能直接破解具身智能的问题”。
- “GPT-6 发布后,整个具身智能行业都被震动”。
但从机器人手部操作的一些基准来看,“在碗任务中,Astra 在 20 次试验中成功放置块体 19 次,而 Fable 5.1 为 8 次”。
而在拼图任务中,“Astra 在 20 次中完成插入 2 次,Fable 5.1 也是 2 次”……我们正在接近目标。
但从原本的 2-3
Comments
Unlock
和 Anthropic 实现广泛的市场应用,它们的吸引力将大幅增强融资时的议价能力。
但他也提醒,全球利率高企可能使资本需求成为未来增长的制约因素。
- 他说,真正的驱动力在于,前沿 AI 公司能否开发出能够创造足够价值和回报的模型,从而证明基础设施扩张是合理的。(这很合理)
- 大多数公司都在词元上浪费钱。他还警告称,大多数公司花钱购买词元,就像孩子在电子游戏厅里乱花游戏币一样。
考虑到陈福阳掌管的是 $AVGO,这部分是他措辞最糟糕的地方。
但西方媒体的报道却将其简化为:
- “现在资本短缺,AI 投资者都是赌徒。”
实际上,在会议上,Broadcom CEO 是在为前沿实验室的估值辩护,并对 AI 基础设施需求发表了谨慎乐观的看法。
他只是将利率上升列为潜在制约因素,而更高的营收或更广泛的应用可以克服这一阻力。
断章取义地摘选言论,扭曲了他的真实表达。
简而言之:
- AI 半导体需求庞大且持续高企,半导体供应不足以满足市场需求。高投入至少还会持续 2 年
- OpenAI 的估值站得住脚;那些因为对公司抱有极端预期而卖出的人,就像赌场赌徒
- 陈福阳表示,市场误读了 OpenAI 的年化经常性收入,因为其基本面依然强劲
- 如果前沿实验室实现广泛应用并获得可观营收,其融资能力将得到增强,足以压过利率上升带来的阻力
$AVGO CEO 的许多言论其实非常讲究分寸,却被西方媒体的报道扭曲了。
💬 引用 Serenity(@aleabitoreddit)
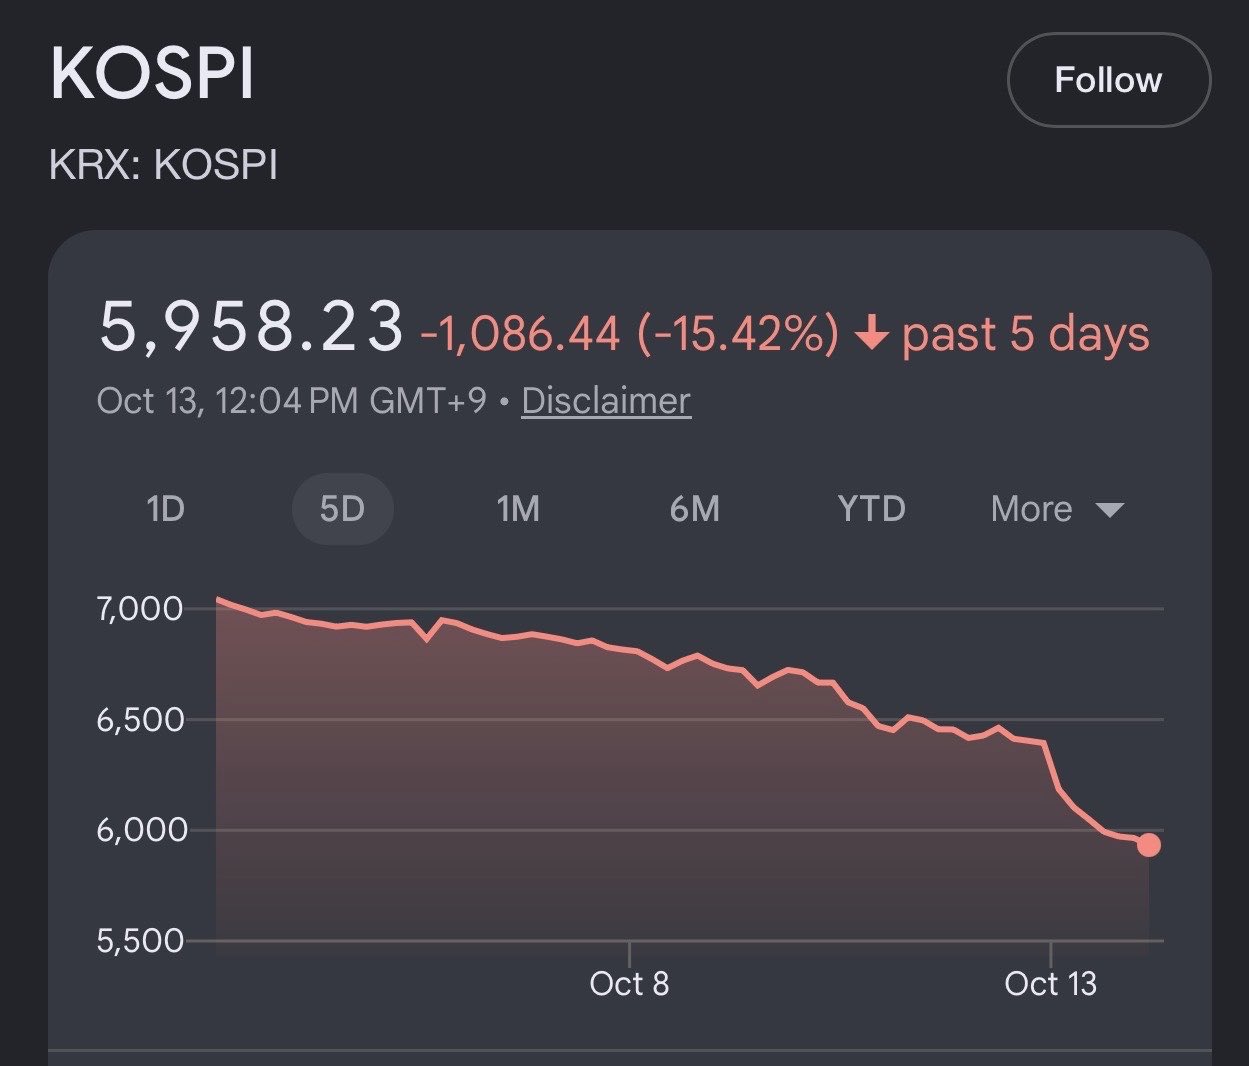
看到韩国市场的 $SKHY / 三星跌成这样,真让人难过。
还得特别“感谢”$AVGO CEO 火上浇油……
他说 AI 投资者都是赌徒,还称企业级 AI 没能带来投资回报。https://t.co/fHzsD9Na4s
原帖:https://x.com/aleabitoreddit/status/2109852646484201736
Serenity (@aleabitoreddit) on X
Wow this is sad to see Korean markets with $SKHY / Samsung crash like this.
Special thanks to $AVGO CEO adding fuel the fire…
Calling AI investors gamblers and saying enterprise AI isn’t delivering ROI.
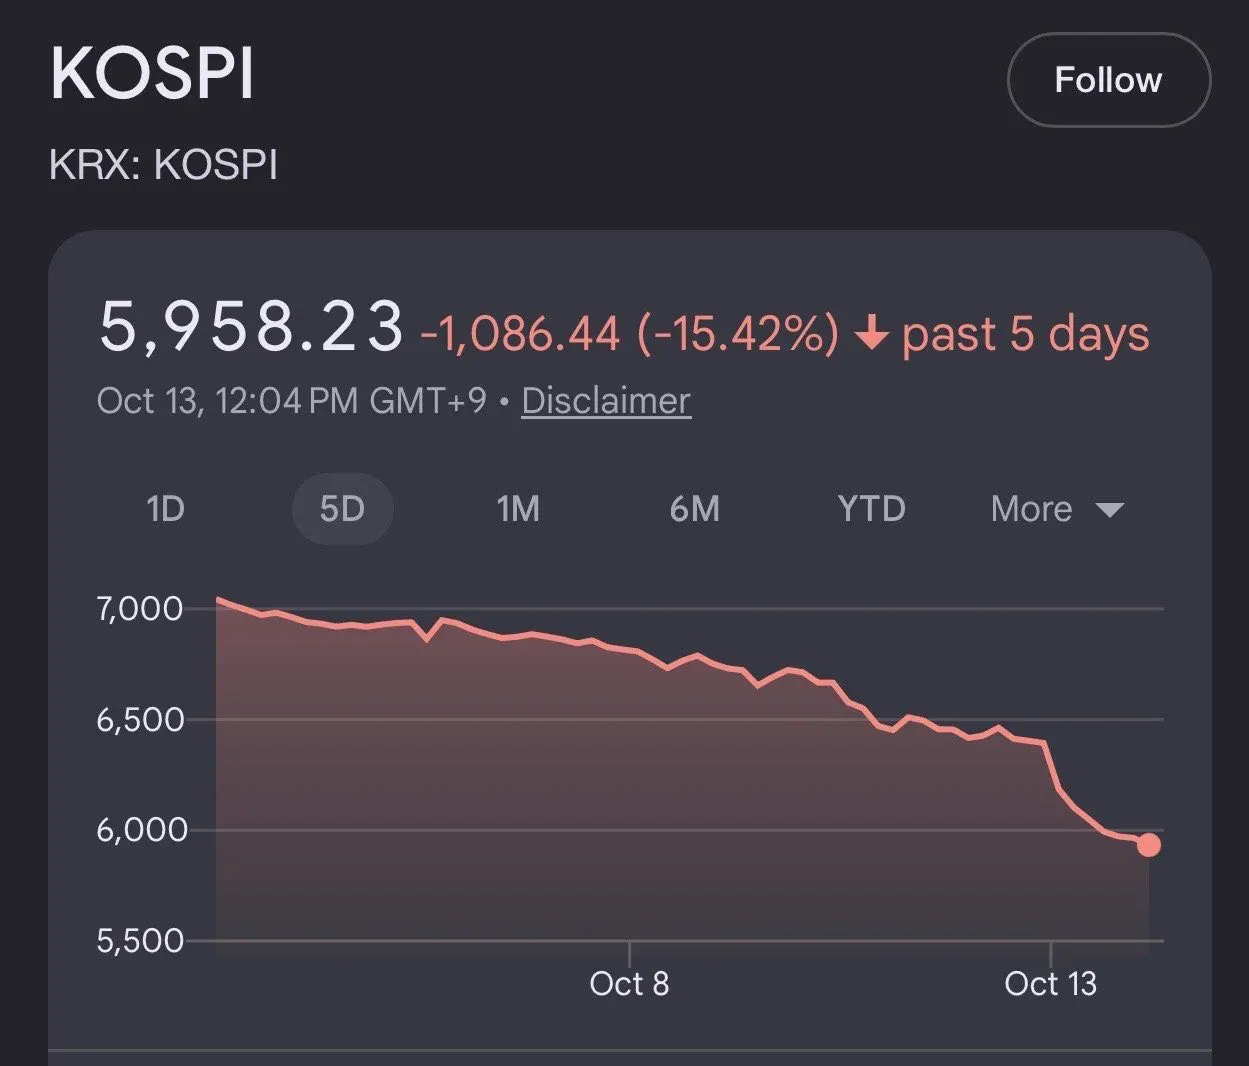
Serenity (@aleabitoreddit)
https://twitter.com/aleabitoreddit/status/2109852646484201736
Wow this is sad to see Korean markets with $SKHY / Samsung crash like this\.
Special thanks to $AVGO CEO adding fuel the fire…
Calling AI investors gamblers and saying enterprise AI isn’t delivering ROI\.
但他也提醒,全球利率高企可能使资本需求成为未来增长的制约因素。
- 他说,真正的驱动力在于,前沿 AI 公司能否开发出能够创造足够价值和回报的模型,从而证明基础设施扩张是合理的。(这很合理)
- 大多数公司都在词元上浪费钱。他还警告称,大多数公司花钱购买词元,就像孩子在电子游戏厅里乱花游戏币一样。
考虑到陈福阳掌管的是 $AVGO,这部分是他措辞最糟糕的地方。
但西方媒体的报道却将其简化为:
- “现在资本短缺,AI 投资者都是赌徒。”
实际上,在会议上,Broadcom CEO 是在为前沿实验室的估值辩护,并对 AI 基础设施需求发表了谨慎乐观的看法。
他只是将利率上升列为潜在制约因素,而更高的营收或更广泛的应用可以克服这一阻力。
断章取义地摘选言论,扭曲了他的真实表达。
简而言之:
- AI 半导体需求庞大且持续高企,半导体供应不足以满足市场需求。高投入至少还会持续 2 年
- OpenAI 的估值站得住脚;那些因为对公司抱有极端预期而卖出的人,就像赌场赌徒
- 陈福阳表示,市场误读了 OpenAI 的年化经常性收入,因为其基本面依然强劲
- 如果前沿实验室实现广泛应用并获得可观营收,其融资能力将得到增强,足以压过利率上升带来的阻力
$AVGO CEO 的许多言论其实非常讲究分寸,却被西方媒体的报道扭曲了。
💬 引用 Serenity(@aleabitoreddit)
看到韩国市场的 $SKHY / 三星跌成这样,真让人难过。
还得特别“感谢”$AVGO CEO 火上浇油……
他说 AI 投资者都是赌徒,还称企业级 AI 没能带来投资回报。https://t.co/fHzsD9Na4s
原帖:https://x.com/aleabitoreddit/status/2109852646484201736
Serenity (@aleabitoreddit) on X
Wow this is sad to see Korean markets with $SKHY / Samsung crash like this.
Special thanks to $AVGO CEO adding fuel the fire…
Calling AI investors gamblers and saying enterprise AI isn’t delivering ROI.
Serenity (@aleabitoreddit)
https://twitter.com/aleabitoreddit/status/2109852646484201736
Wow this is sad to see Korean markets with $SKHY / Samsung crash like this\.
Special thanks to $AVGO CEO adding fuel the fire…
Calling AI investors gamblers and saying enterprise AI isn’t delivering ROI\.
Comments
Unlock
原文:
So spent some more time to look at more DBS conference material:
- "Two semiconductor giants, $AVGO and $INTC, both stated that breakthroughs in AI will keep demand for chip investment elevated for at least another 2 years. As current supply is insufficient to meet market demand."
- "Current chip production capacity is already far from sufficient to meet demand, and $AVGO CEO expects the shortage to become even more severe in the future." (HKEJ)
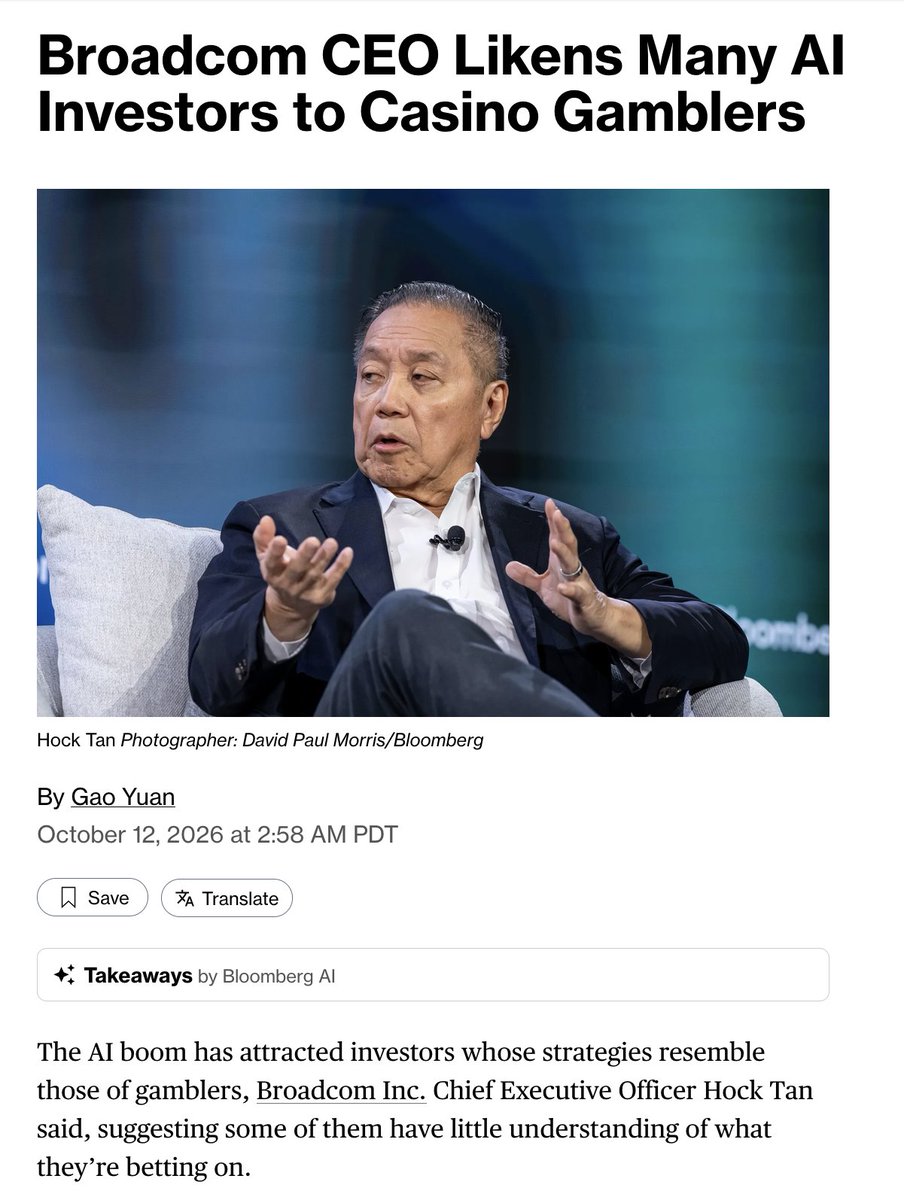
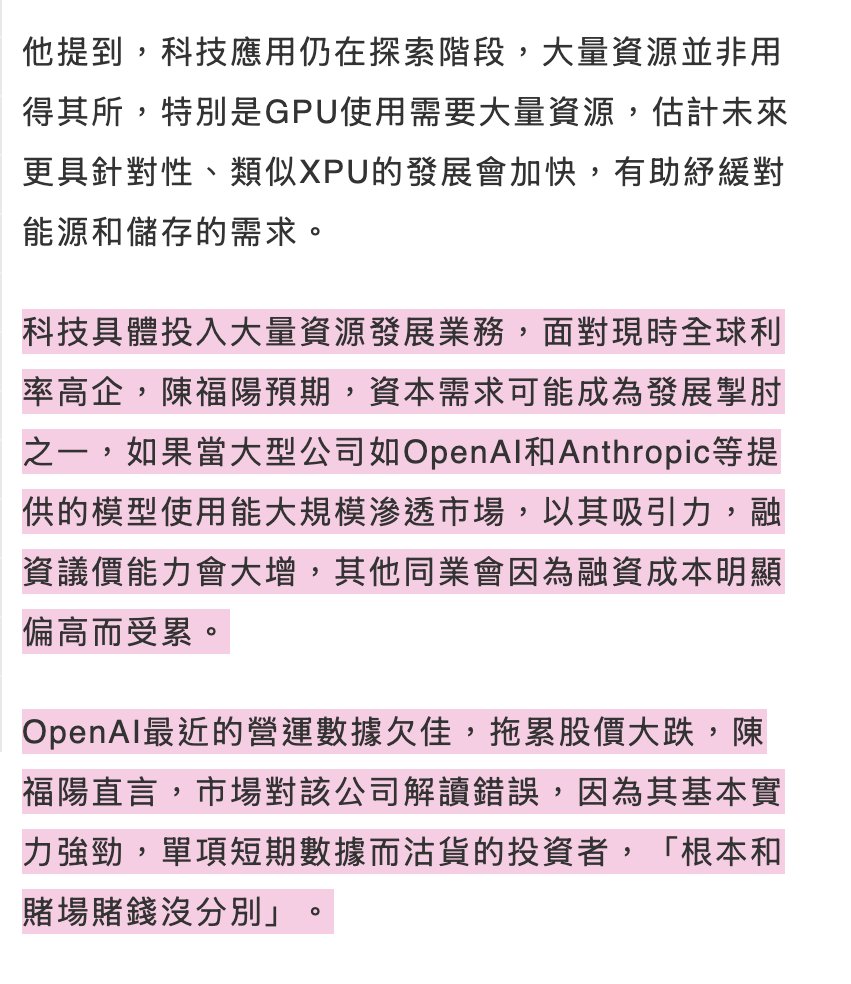
- "Regarding OpenAI, Hock Tan stated that the market had misinterpreted the company because its underlying fundamentals remained strong.
He argued that investors who sell based on a single short-term data point [$50B ARR] are "essentially no different from people gambling in a casino." (eg. Hong Kong Economic Journal):
- Commenting on investors' disappointment in OpenAI’s latest revenue forecast: "by itself, not that bad" on their $50B ARR. (Business Times)
And connected investors' disappointment to a failure to understand the business and excessive expectations like a casino.
- Tan rejected the proposition that OpenAI was overvalued. It quotes him saying:
"It’s almost like they are in a casino gambling" in regards to investors' unrealistic expectations and lack of understanding on OpenAI.
- Hock Tan if OpenAI and Anthropic achieve widespread market adoption: their attractiveness would substantially strengthen their bargaining power when raising capital.
But cautioned elevated global interest rates could make capital requirements a constraint for future growth.
- The real driver, he said, is whether frontier AI companies can create models that generate enough value and returns to justify the buildout. (which is fair)
- Most companies are wasting money on tokens. He also warned that most companies just waste money spending tokens like kids in a video arcade.
This part was the most badly worded by Hock Tan
So spent some more time to look at more DBS conference material:
- "Two semiconductor giants, $AVGO and $INTC, both stated that breakthroughs in AI will keep demand for chip investment elevated for at least another 2 years. As current supply is insufficient to meet market demand."
- "Current chip production capacity is already far from sufficient to meet demand, and $AVGO CEO expects the shortage to become even more severe in the future." (HKEJ)
- "Regarding OpenAI, Hock Tan stated that the market had misinterpreted the company because its underlying fundamentals remained strong.
He argued that investors who sell based on a single short-term data point [$50B ARR] are "essentially no different from people gambling in a casino." (eg. Hong Kong Economic Journal):
- Commenting on investors' disappointment in OpenAI’s latest revenue forecast: "by itself, not that bad" on their $50B ARR. (Business Times)
And connected investors' disappointment to a failure to understand the business and excessive expectations like a casino.
- Tan rejected the proposition that OpenAI was overvalued. It quotes him saying:
"It’s almost like they are in a casino gambling" in regards to investors' unrealistic expectations and lack of understanding on OpenAI.
- Hock Tan if OpenAI and Anthropic achieve widespread market adoption: their attractiveness would substantially strengthen their bargaining power when raising capital.
But cautioned elevated global interest rates could make capital requirements a constraint for future growth.
- The real driver, he said, is whether frontier AI companies can create models that generate enough value and returns to justify the buildout. (which is fair)
- Most companies are wasting money on tokens. He also warned that most companies just waste money spending tokens like kids in a video arcade.
This part was the most badly worded by Hock Tan
Comments
Unlock
given he's running $AVGO.
But Western media commentary narrowed this down to:
- "Shortage of capital now, AI Investors are gamblers".
In the conference, Broadcom's CEO was actually defending frontier lab valuations and giving cautiously bullish statements about AI infrastructure demand.
While citing rising interest rates as a potential constraint that larger revenue or adoption could overcome.
Cherry picking quotes out of context disorts the actual messaging.
TLDR:
- Large and elevated AI semi demand, semi supply insufficient to meet market demand. At least another 2 years of elevated spend
- OpenAI valuations defensible, people who sell based on extreme expectations for the company are like casino gamblers.
- Tan stated markets had misinterpreted OpenAI's ARR because its underlying fundamentals remained strong.
- Frontier labs if they achieve widespread adoption / revenue would strengthen capital raising, which overpower headwinds from raising interest rates.
Lot of $AVGO CEO remarks looks heavily nuanced, which Western media coverage distored.
💬 引用 Serenity (@aleabitoreddit)
Wow this is sad to see Korean markets with $SKHY / Samsung crash like this.
Special thanks to $AVGO CEO adding fuel the fire…
Calling AI investors gamblers and saying enterprise AI isn’t delivering ROI. https://t.co/fHzsD9Na4s
原帖:https://x.com/aleabitoreddit/status/2109852646484201736
翻译:
所以我又花了些时间,查看了更多 DBS 会议资料:
- “两家半导体巨头 $AVGO 和 $INTC 都表示,AI 的突破将使芯片投资需求至少再维持 2 年高位,因为目前的供应不足以满足市场需求。”
- “目前的芯片产能已远远无法满足需求,$AVGO CEO 预计未来短缺还会进一步加剧。”(香港《信报财经新闻》)
- “谈到 OpenAI 时,陈福阳表示,市场误读了这家公司,因为其基本面依然强劲。
他认为,仅凭单一的短期数据点[$50B 年化经常性收入]就卖出的投资者,‘本质上与在赌场赌博的人没什么区别’。”(例如香港《信报财经新闻》)
- 在评论投资者对 OpenAI 最新营收预测的失望时,他表示,$50B 的年化经常性收入“单看这个,其实没那么糟”。(《商业时报》)
他还指出,投资者之所以失望,是因为不了解这项业务,并像赌场赌徒一样抱有过高预期。
- 陈福阳否认 OpenAI 估值过高。报道援引他的话称:
“这几乎就像他们在赌场里赌博。”
这句话指的是投资者对 OpenAI 抱有不切实际的预期,并且缺乏了解。
- 陈福阳表示,如果 OpenAI
Serenity (@aleabitoreddit) on X
Wow this is sad to see Korean markets with $SKHY / Samsung crash like this.
Special thanks to $AVGO CEO adding fuel the fire…
Calling AI investors gamblers and saying enterprise AI isn’t delivering ROI.
Serenity (@aleabitoreddit)
https://twitter.com/aleabitoreddit/status/2109852646484201736
Wow this is sad to see Korean markets with $SKHY / Samsung crash like this\.
Special thanks to $AVGO CEO adding fuel the fire…
Calling AI investors gamblers and saying enterprise AI isn’t delivering ROI\.
Comments
Unlock
where more capacity comes online like test or DRAM. So it's a lot more nuanced than capex down = everything down or vice versa.
I also slightly agree with community agreements that open weight models wouldn't lessen demand on AI infrastructure (otherwise $NVDA wouldn't be funneling funds into Reflection), but all the contractual obligations that Anthropic has might get messy if their models/company get cannibalized.
Either way, I'd expect some of these frontier lab valuations to likely compress but I do think Jensen knows what he's doing though to avoid contagion.
But basically:
- Extremely difficult market now, can't just throw money at any AI supply chain company like $GLW and expect it to go up. There's cause for concern of rate hikes mixed with financing per $AVGO CEO but not to the point you just blindly sell off everything.
Also I think markets are stupid and ties baskets together so that leads to mispricing + individual buying opportunities with certain chokepoints too.
If capacity + demand is visible and forward p/e compresses like $AAOI to single digits off hundreds or thousands of percent growth from hyperscalers off $471m transceiver revenues and hundreds of thousands of monthly ELSFP capacity. Or $SIVE coming online with 100M+ laser capacity + multiple foundries with ASP hikes on lasers. I wouldn't lump them into other AI supply chain names in IP like $RMBS or others.
My take is that AI supply chain beneficiaries with closer inflection points, demand visibility, and forward P/E compressing due to economic leverage would likely outperform medium term despite current volatility.
TLDR:
- Memory strongest risk/adjusted return with LTAs + pricing floors extending to 2030's + buybacks.
- My opinion is that optical supercycle for 2027-2028 with CPO/NPO is going to look absurd relative to capacity coming online of smaller suppliers.
-
Comments
Unlock
Overwhelming fundamentals/growth colliding with sht macro + media scares
- Markets are stupid and groups things in baskets and sells them all off together or buys overvalued names, creating short/long opportunities
I'd give a prayer to people on short term options given underlying drop + IV decline, but there could be a reversal... who knows. Most valuable thing right now is time.
💬 引用 Wolfex (@Wolfex_Yeat)
@aleabitoreddit @SiversSemicond Serenity please give us some cope we are panicking out here with photonic stocks and memory 😭
原帖:https://x.com/Wolfex_Yeat/status/2109748007386087814
翻译:
好的……现在随意聊聊市场的想法,光学方面如 $LITE / 内存 + $IREN / Anthropic。
关于内存:
- 对 $MU / Samsung / SK Hynix 的需求可视性延伸至 2030‑2031。
- Samsung 已签订长期协议,覆盖其 70% 容量至 2031(可能带有 SK Hynix 类的价格底线)……其营业利润已经非常夸张。
- 市场普遍认为 2027 年的短缺将比 2026 年更为严重……甚至 $SNDK 的毛利率将提升至 80% 以上,进入 2030 年。
- 你会听到 Acer 以及其他 CEO 们在希望内存价格下跌时引用 CXMT/YMTC 和中国厂商的悲观案例。
- 但仅从 $NVDA 正在进行的供应采购加上超大规模算力提供商来看,未来 5 年的需求可视性已经非常夸张。到那时,这些买断/付费加价格底线合同产生的累计自由现金流可能超过它们的整体市值,感觉已经形成了某种基准。
- 短期总是波动的(隐含波动率在 $EWY、$DRAM、$MU 上大幅下降),因此持有看涨期权的投资者可能被炸得体无完肤,标的价格也随之下跌。
- 但如果 Samsung 2027 年预期是 3 倍,且已有 5 年长期协议锁定 70% 容量来自超大规模算力提供商,并且设有价格底线,那么这些公司出现持续崩盘的可能性就不大……
关于光学:
- $LITE 的订单已经售罄至 2029,正在讨论 2030 年的供货。需求可视性延伸至 2031……超大规模算力提供商基本上在为产能扩张提供资金。
- 其 2028 年在 Greensboro 的工厂扩建仅光学激光产能收入约 50 亿美元,且基本上已分配给 $NVDA(占比 50% 以上,并有进一步选项)以及渠道调查得到的其他客户。
- 现有供应链瓶颈极为严重,光学内容/XPU 在 2027‑2028 年将出现爆发式增长。
- 因此 DSP、TIA、光电二极管、激光器、InP/SOI 基板、晶圆(外延、SOI 等)都预计会“嗡嗡作响”。
- 那么这对 $AAOI、$SIVE、$MTSI 等将在 2027 年投产的大容量供应商意味着什么?或者其他玩家如 Sumitomo / Furukawa?
- 但这与内存的情况不同,因为在一个集群中 BOM 比例极低……如果 Micron/Samsung 再提升 2000% 超大规模算力提供商将破产。但对 InP 基板来说,这种提升似乎是可能的,或者 CW 激光产能翻倍。
- 我原本认为 $LITE 的市值超过 1000 亿美元相对其容量扩张而言被高估了,尤其是相对于更小光学玩家的市值。因此我选择相应的仓位(但 Lumentum 确实因需求可视性而值得溢价)。
对于领头羊如 $NVDA / $AVGO / $MRVL:
- Nvidia
Wolfex (@Wolfex_Yeat)
https://twitter.com/Wolfex_Yeat/status/2109748007386087814
@aleabitoreddit @SiversSemicond Serenity please give us some cope we are panicking out here with photonic stocks and memory 😭
Comments
Unlock
ongoing financing (think they're like halfway through their $6B ATM).
Just some hopium for $IREN investors, $NBIS also signed a deal with $META at the start of the year (but markets didn't care at all, since Nebius dropped to ~$70-80 at the lowest point?).
But did 6 months later, as the time to revenue inflection gets closer and you're past the ATM/capex window, markets would likely care more.
I don't think it's irrational but at the same time, the fundamentals have improved from Mirantis acquisition to others. I also think it was known for awhile it was either OpenAI/Anthropic from CEO comments earlier too?
But either way to be a more risk-off environment where funds seem to be rotating to larger names as a flight to safety.
$CRWD / $PLTR as just two example, but my take is that the valuations of these rotations are reaching clown levels. And that certain AI supply chain beneficiaries in comparison are undervalued now.
I was thinking markets would just rotate to names that are extremely profitable like Samsung or names that have <2X P/E, so it was surprising to see $KOSPI and some legacy memory players get sold off today.
Since all of this is colliding with uncertainty about sht macro environments and renewed sustainability concern of AI capex/commitments from frontier labs like OpenAI/Anthropic from due to that FT piece recently. I've always been sounding the alarm about the contractual backlog OpenAI has with $CBRS, $MSFT, $ORCL and others earlier in the year. But OpenAI did just raise $122B or so , so I don't quite think they're at risk of going down anytime soon.
I also don't think overall capex can just exponentially go up, but even if it stalls / hovers around a certain point or even drops...
Capex toward certain areas like optics will still explode as hyperscalers fight over allocations when CPO scale up comes about, but might drop in others
Comments
Unlock
原文:
Sure... Random train of thoughts on markets now, optics like $LITE / memory + $IREN / Anthropic.
On Memory:
- Demand visibility on $MU / Samsung / SK Hynix extend into 2030-2031.
Samsung has LTAs covering 70% of their capacity into 2031 (likely with SK Hynix type price floors)... and their operating profit is already absurd.
There's a consensus that shortage in 2027 will be much more severe than 2026... Even $SNDK expends gross margins to exceed 80% entering 2030.
You're going to hear Acer and other CEOs that want memory prices to go down cite bear cases like CXMT/YMTC, and Chinese players.
But just looking at supply procurement that $NVDA is doing + hyperscalers, demand visibility is absurd for the next 5 years. And by that time, cumulative FCF coming in from these take/pay + pricing floor contracts might exceed some of their entire marketcaps so it feels like there's some baseline.
Near-term is always volatile (IV dropped a ton across $EWY to $DRAM to $MU), so people with call options likely got nuked, along with underlying prices.
But if Samsung is 3x 2027E, has 5 year LTAs with 70% of capacity committed from hyperscalers, and price floors, it's kinda hard to see these names suffer a sustained crash...
For optics:
- $LITE is literally sold out into 2029, starting discussions into 2030. With demand visibility lasting into 2031… with hyperscalers largely funding the capacity buildout.
Their 2028 Greensboro fab expansion was ~$5B in UHP laser capacity revenue alone, yet it’s basically allocated toward $NVDA (50%+ with options for more) and co from channel checks.
Existing supply chain bottlenecks are extremely severe as optical content/XPU skyrockets entering 2027-2028.
So everything from DSPs/TIAs, photodiodes, lasers, InP/SOI substrates, wafers (epi, SOI, etc) are expected to go brrr.
And what does that imply to anyone else with
Comments
Unlock
enormous amounts of capacity coming online like $AAOI + $SIVE + $MTSI capacity expansion in 2027? Or other players like Sumitomo / Furukawa?
But again it's not quite the same situation as memory since the BOM % is extremely low in a cluster... If micron/samsung raised another 2000% hyperscalers would go bankrupt. But doing that for InP substrates seems possible. Or a 100% increase on CW laser content.
I actually thought $LITE was overvalued at $100B+ MC, relative to capacity expansion on your smaller optical players to their respective MCs. So I chose to position accordingly (But lumentum does deserve premiums for demand visibility).
For the companies leading the charge like $NVDA / $AVGO / $MRVL:
- Nvidia has 70% forward revenue growth FY2028 which is supply constrained growth.
- Broadcom 100% Y/Y for 2027/2028 which is also supply constrained growth.
- Marvell FY2031 upgraded guidance to $70B-$90B from $46B analyst projections...
They all seem to be very happy.... and read through on demand for next 2-3 years is enormous (also echoing what $INTC CEO said today on the panel with $AVGO CEO).
So you have overwhelming growth on memory + photonics + from the leaders... But the nuance is not everything in the AI supply chain get the same economic benefit.
HBM/Laser/CPU/MLCC and other players in the bottlenecks look to be printing money. And seem to be the largest beneficiaries of the current bottlenecks.
Test players are also getting price hikes + capacity allocated by players like $NVDA, but economic impact seems a tad lower than other players since forward P/E for many I modeled were still in the 45x+ range even if you hiked prices like 10-30%.
As for capex intensive players... there's some like $IREN ($25-30B for 2027) that despite a deal with Anthropic ended up dropping. I don't think markets seem to appreciate players spending a lot of money +
Comments
Unlock
原文:
Looks like one of you posted on $RDDT WSB… with a $1M $AAOI position.
I’m laughing at the comments, even more amusing when my name pops up
Might still be early if people think there’s “no moat” in lasers and that AOI makes no money. (wait and see Q2 2027) https://t.co/vG6Zl4LZHf
翻译:
看起来你们中有人在 $RDDT WSB 上发帖… 持有 100 万美元的 $AAOI 仓位。
我在笑这些评论,尤其是当我的名字被提及时更觉得好笑。
如果有人认为激光没有护城河且 AOI 不赚钱,可能仍然为时过早。(拭目以待 2027 年第二季度) https://t.co/vG6Zl4LZHf
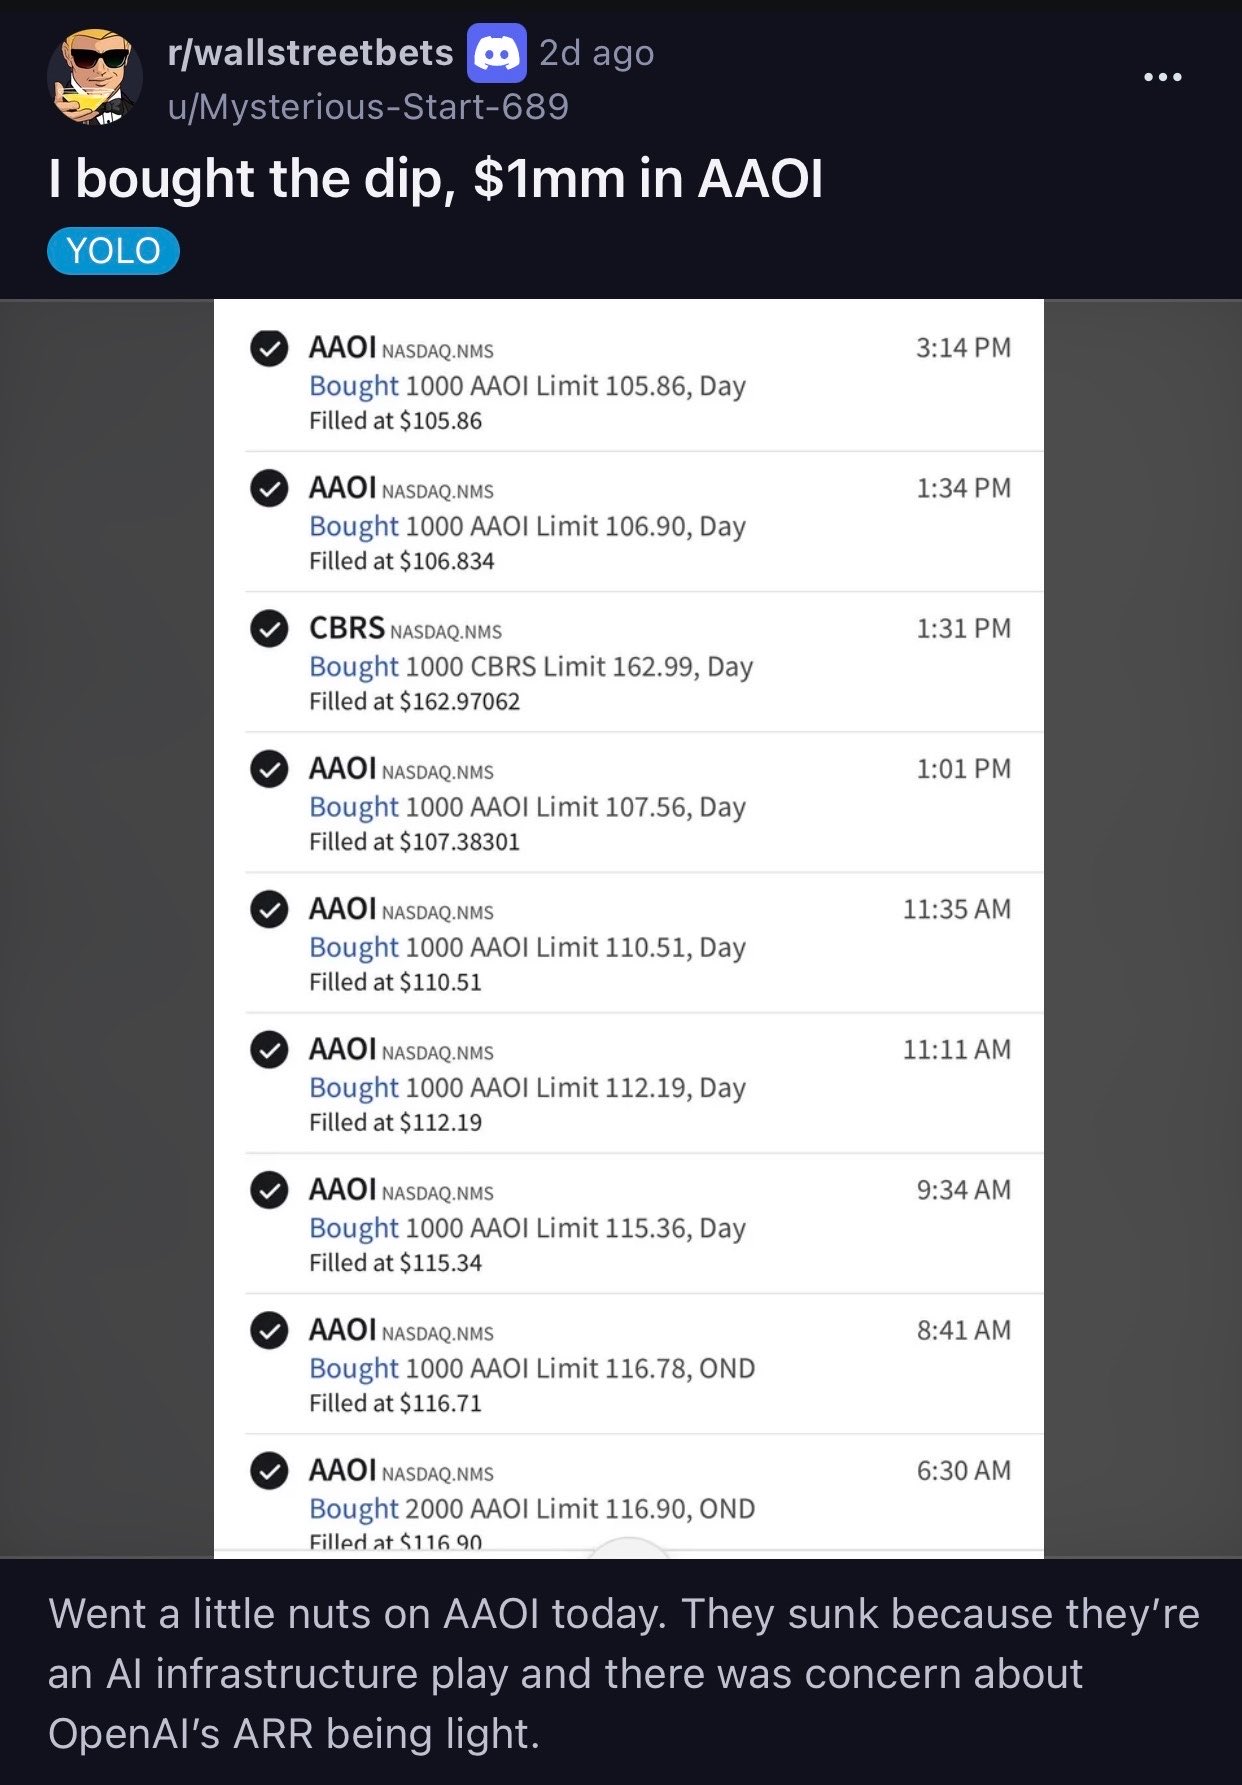
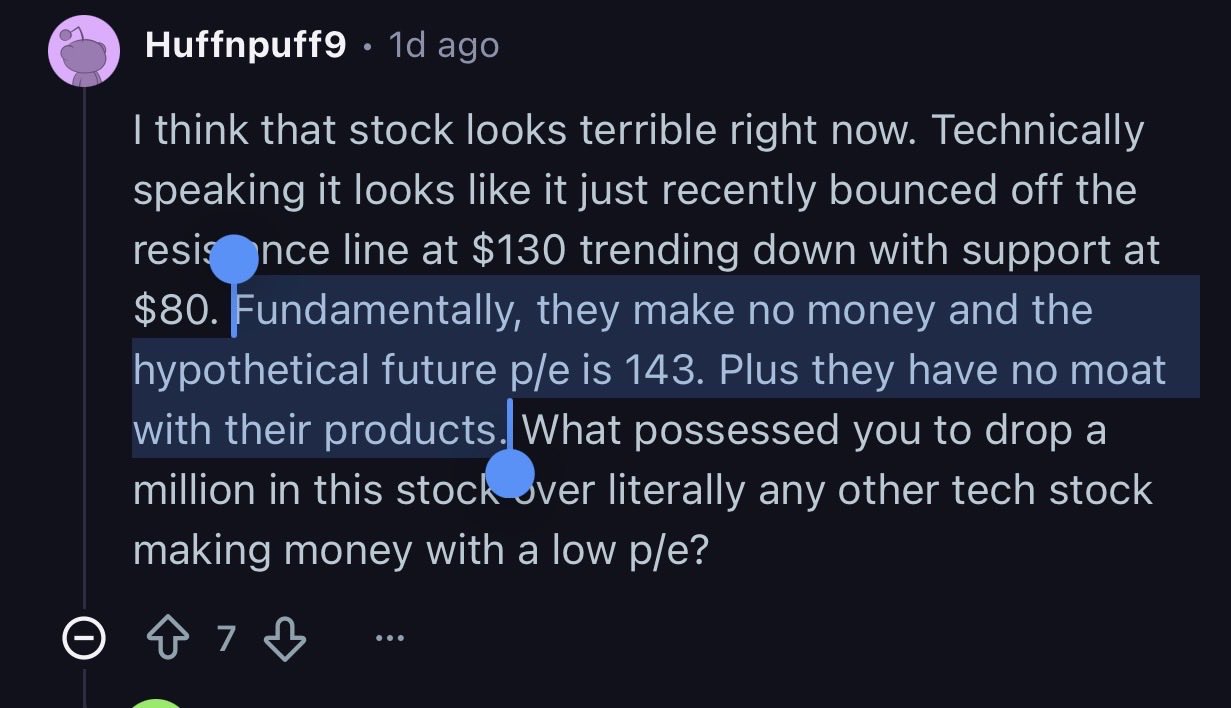
Looks like one of you posted on $RDDT WSB… with a $1M $AAOI position.
I’m laughing at the comments, even more amusing when my name pops up
Might still be early if people think there’s “no moat” in lasers and that AOI makes no money. (wait and see Q2 2027) https://t.co/vG6Zl4LZHf
翻译:
看起来你们中有人在 $RDDT WSB 上发帖… 持有 100 万美元的 $AAOI 仓位。
我在笑这些评论,尤其是当我的名字被提及时更觉得好笑。
如果有人认为激光没有护城河且 AOI 不赚钱,可能仍然为时过早。(拭目以待 2027 年第二季度) https://t.co/vG6Zl4LZHf
Comments
Unlock
原文:
Woooow... $LITE CEO went out on Bloomberg today and stated:
Lumentum is "effectively sold out through nearly 2029".
From our perspective, "Completely Sold Out, there's no end in sight". With demand visibility from hyperscalers that carries them out into 2030, 2031.
The implications of these statements are enormous for photonics and remaining laser suppliers with capacity coming online like $SIVE, Sumitomo Electric, to $AAOI.
What a crazy bottleneck that's unfolding.
💬 引用 Serenity (@aleabitoreddit)
Can someone explain how media headlines about OpenAI’s ~$50B ARR…
(vs. ~$70B from incorrect accounting comparisons with Anthropic)
Somehow ends a 3-5 year laser shortage with $AAOI or memory shortage with $MU?
Hint: it doesn’t. https://t.co/FiVsvg8I0G
原帖:https://x.com/aleabitoreddit/status/2108272287908860377
翻译:
哇……$LITE CEO 今天在彭博表示:
Lumentum 的“产能实际上已售罄,订单排期已接近2029年”。
在我们看来,就是“彻底卖光,而且完全看不到尽头”。超大规模云服务商的需求能见度已经延伸至2030年、2031年。
这些表态对光子产业,以及$SIVE、住友电工和$AAOI等即将释放新产能的其他激光器供应商而言,意义极其重大。
正在形成的这个瓶颈太疯狂了。
💬 引用 Serenity(@aleabitoreddit)
谁能解释一下,为什么媒体有关 OpenAI 年化经常性收入约500亿美元的标题……
(而不是通过与 Anthropic 进行错误会计口径比较得出的约700亿美元)
竟然就能终结$AAOI面临的3-5年激光器短缺,或$MU面临的存储芯片短缺?
提示:根本不能。https://t.co/FiVsvg8I0G
原帖:https://x.com/aleabitoreddit/status/2108272287908860377
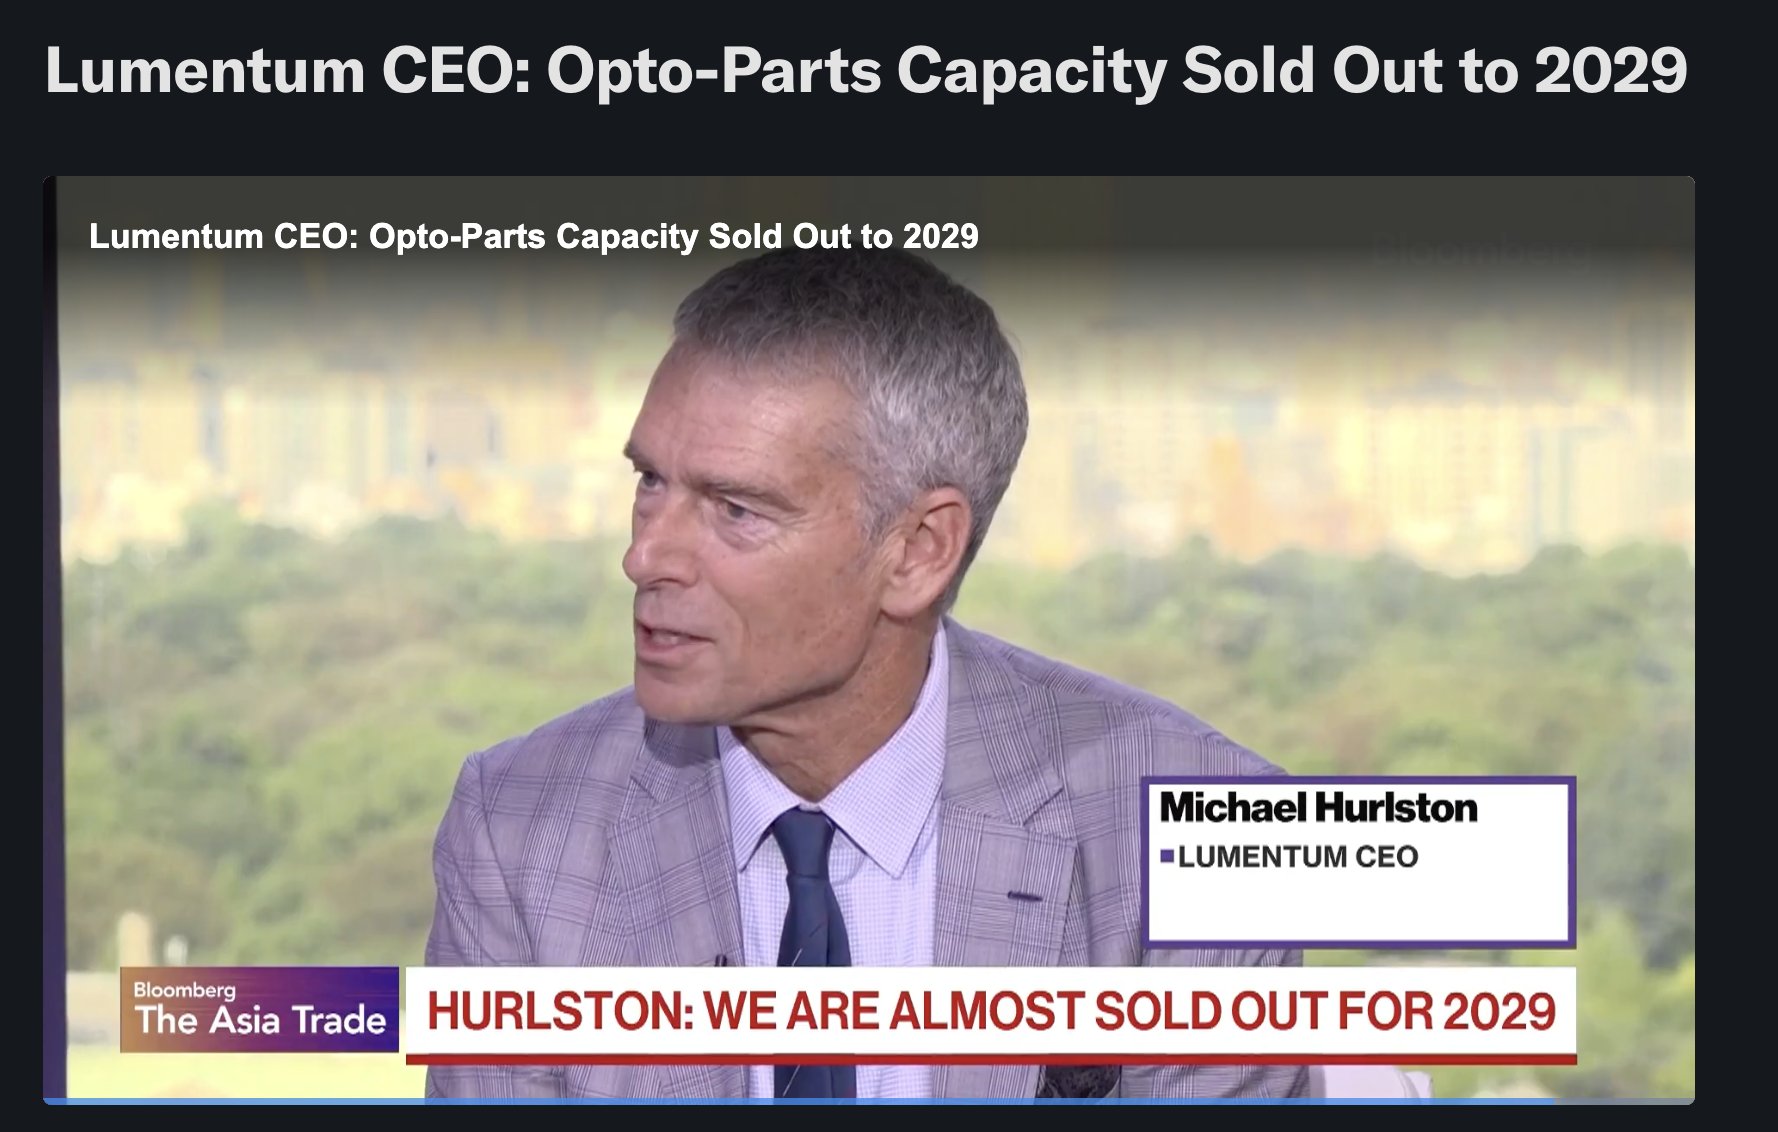
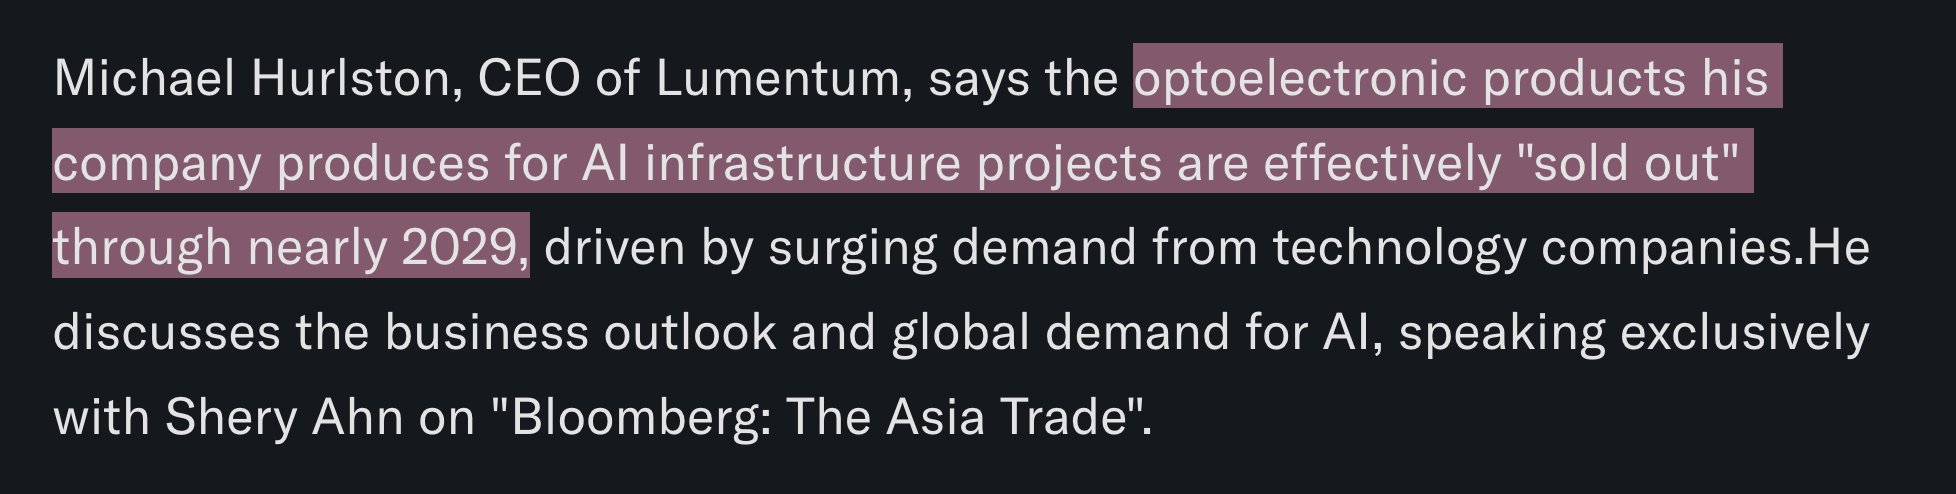
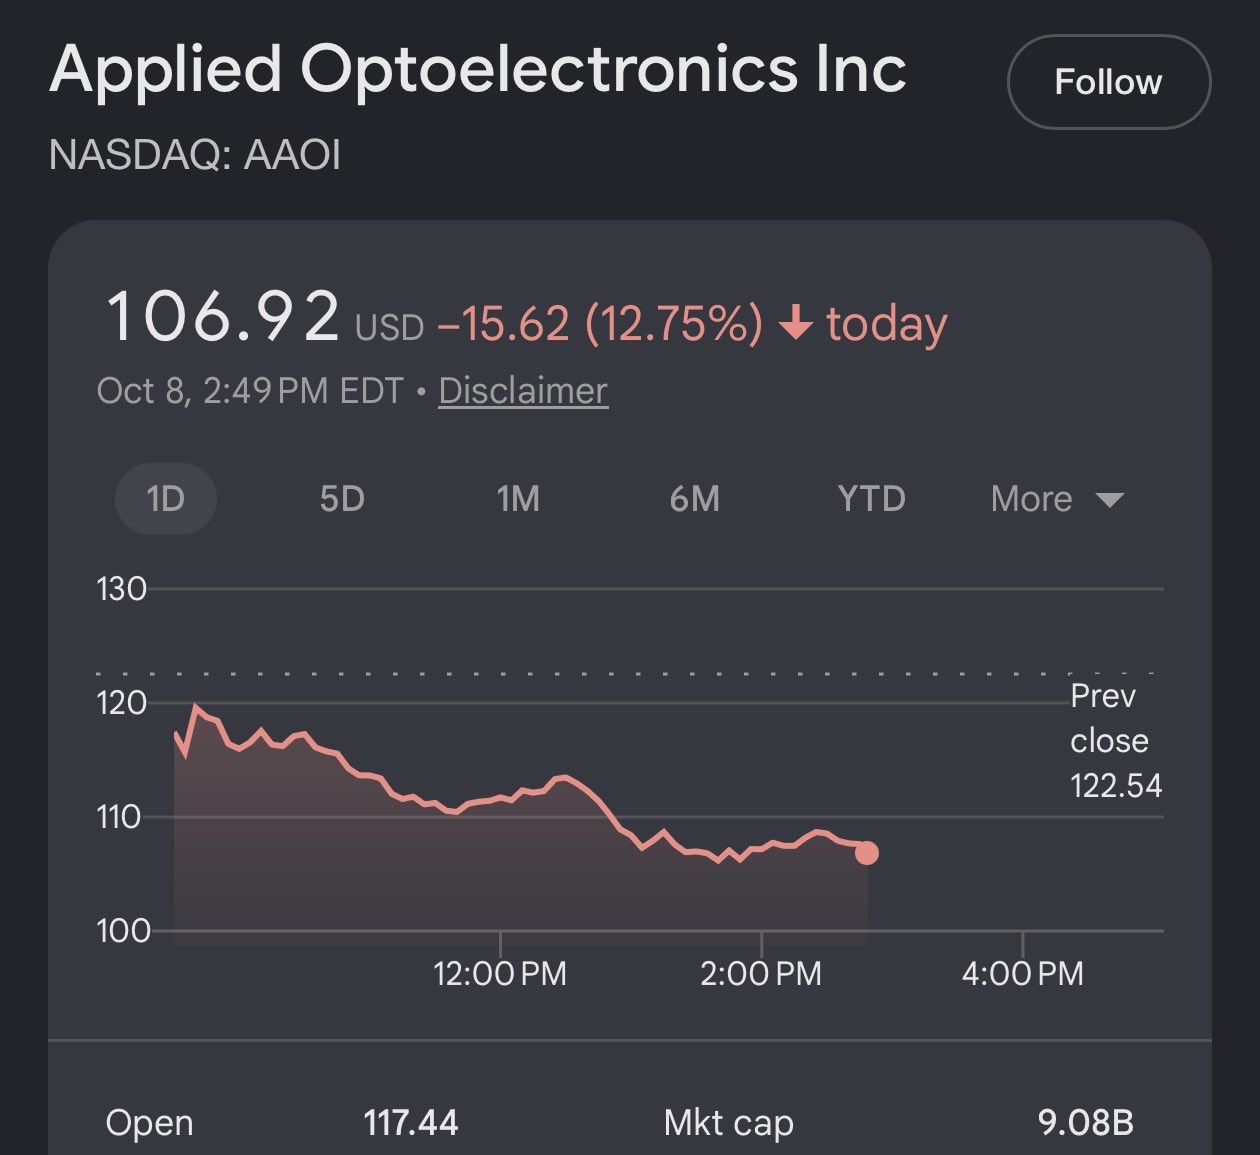
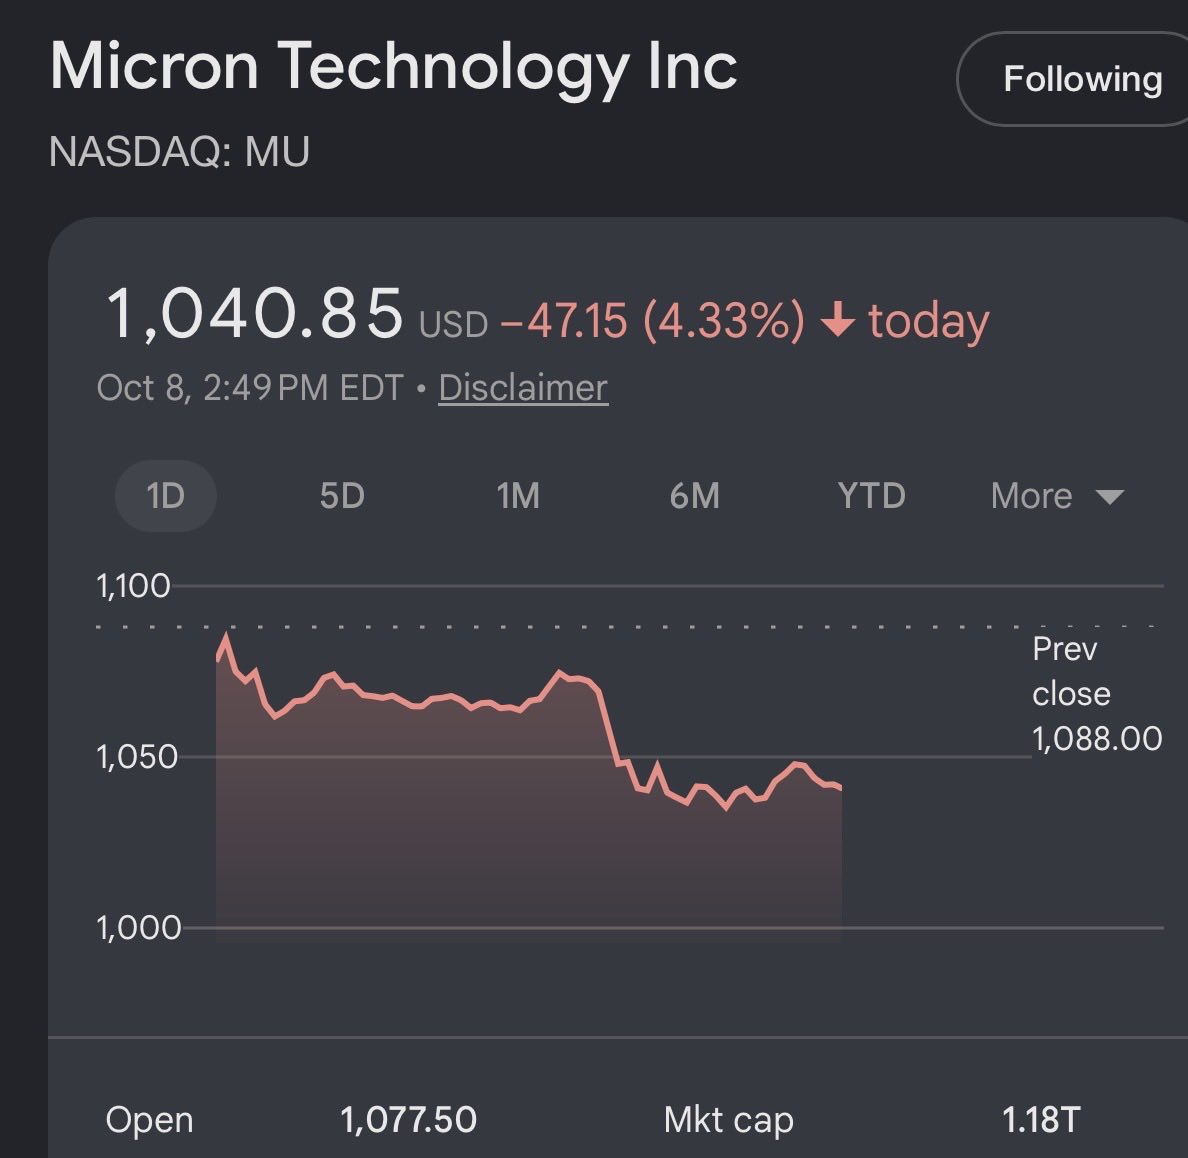
Woooow... $LITE CEO went out on Bloomberg today and stated:
Lumentum is "effectively sold out through nearly 2029".
From our perspective, "Completely Sold Out, there's no end in sight". With demand visibility from hyperscalers that carries them out into 2030, 2031.
The implications of these statements are enormous for photonics and remaining laser suppliers with capacity coming online like $SIVE, Sumitomo Electric, to $AAOI.
What a crazy bottleneck that's unfolding.
💬 引用 Serenity (@aleabitoreddit)
Can someone explain how media headlines about OpenAI’s ~$50B ARR…
(vs. ~$70B from incorrect accounting comparisons with Anthropic)
Somehow ends a 3-5 year laser shortage with $AAOI or memory shortage with $MU?
Hint: it doesn’t. https://t.co/FiVsvg8I0G
原帖:https://x.com/aleabitoreddit/status/2108272287908860377
翻译:
哇……$LITE CEO 今天在彭博表示:
Lumentum 的“产能实际上已售罄,订单排期已接近2029年”。
在我们看来,就是“彻底卖光,而且完全看不到尽头”。超大规模云服务商的需求能见度已经延伸至2030年、2031年。
这些表态对光子产业,以及$SIVE、住友电工和$AAOI等即将释放新产能的其他激光器供应商而言,意义极其重大。
正在形成的这个瓶颈太疯狂了。
💬 引用 Serenity(@aleabitoreddit)
谁能解释一下,为什么媒体有关 OpenAI 年化经常性收入约500亿美元的标题……
(而不是通过与 Anthropic 进行错误会计口径比较得出的约700亿美元)
竟然就能终结$AAOI面临的3-5年激光器短缺,或$MU面临的存储芯片短缺?
提示:根本不能。https://t.co/FiVsvg8I0G
原帖:https://x.com/aleabitoreddit/status/2108272287908860377
Comments
Unlock
原文:
Having coffee with a $GOOGL TPU designer rn
Anyone have questions that are non confidential?
翻译:
正在和一位 $GOOGL TPU 设计师喝咖啡
有人有非机密的问题吗?
Having coffee with a $GOOGL TPU designer rn
Anyone have questions that are non confidential?
翻译:
正在和一位 $GOOGL TPU 设计师喝咖啡
有人有非机密的问题吗?
Comments
Unlock
原文:
Can someone explain how media headlines about OpenAI’s ~$50B ARR…
(vs. ~$70B from incorrect accounting comparisons with Anthropic)
Somehow ends a 3-5 year laser shortage with $AAOI or memory shortage with $MU?
Hint: it doesn’t. https://t.co/FiVsvg8I0G
翻译:
有人能解释一下媒体关于 OpenAI 约 $50 B ARR 的标题是怎么来的…
(相较于约 $70 B 的错误会计比较,针对 Anthropic)
它们怎么会用 $AAOI 解决 3‑5 年的激光短缺,或用 $MU 解决内存短缺?
提示:并没有。 https://t.co/FiVsvg8I0G
Comments
Unlock
原文:
$AAOI is... finally... done...
With their $600m ATM program, turns out it's ~$105.36 average.
I do think AOI outperforms $LITE, as long as they stop filing these ATM programs.
Just due to their sheer magnitude of ramp with $471m/month transceiver revenue + 400K/month ELSFP coming up.
💬 引用 Serenity (@aleabitoreddit)
$AAOI has finished a $500m ATM In April.. $600m ATM in June. Then filed another $600m in August.
It's out of my control if management wants to abuse this trash repeated ATM structure. Instead following $AXTI like LTA prepayments and using that to fund buildout.
Or taking private placements like $NVDA + Nebius for $2B and using that to fund buildout.
Or convertible notes at 40% premiums.
It's really hard for the stock to break out of $100 or $150 or $200 if there's $600M of selling pressure at those levels (and maybe expectations of future ATMs).
I had the same criticism with $IREN with their $6B ATM, which is why it's been rangebound for half a year. And I'll say the same thing with my own thesis names too.
I see $AAOI operationally very bullish for 2027, with $471m/month transceiver revenue. 400k ELSFP units/month entering 2028.
The revenue ramp is absurd and can compress to single digit forward P/E.
But I find it hard to get excited over funding infinite ATMs during the buildout, when you're sacrificing opportunity cost with names currently profitable like $SNDK or Samsung.
I think a lot of retail investors conflate stock performance with how a company is doing operationally.
$AAOI is capitalizing on a bottleneck with high demand visibility, but stock has been going nowhere near-term with repeated ATMs.
I do expect AOI to strongly outperform (especially in 2027) if they stop issuing these stupid ATMs.
原帖:https://x.com/aleabitoreddit/status/2103151990146801812
翻译:
$AAOI …终于…完成了…
他们的 $600m ATM 计划,平均约为 $105.36。
只要他们停止提交这些
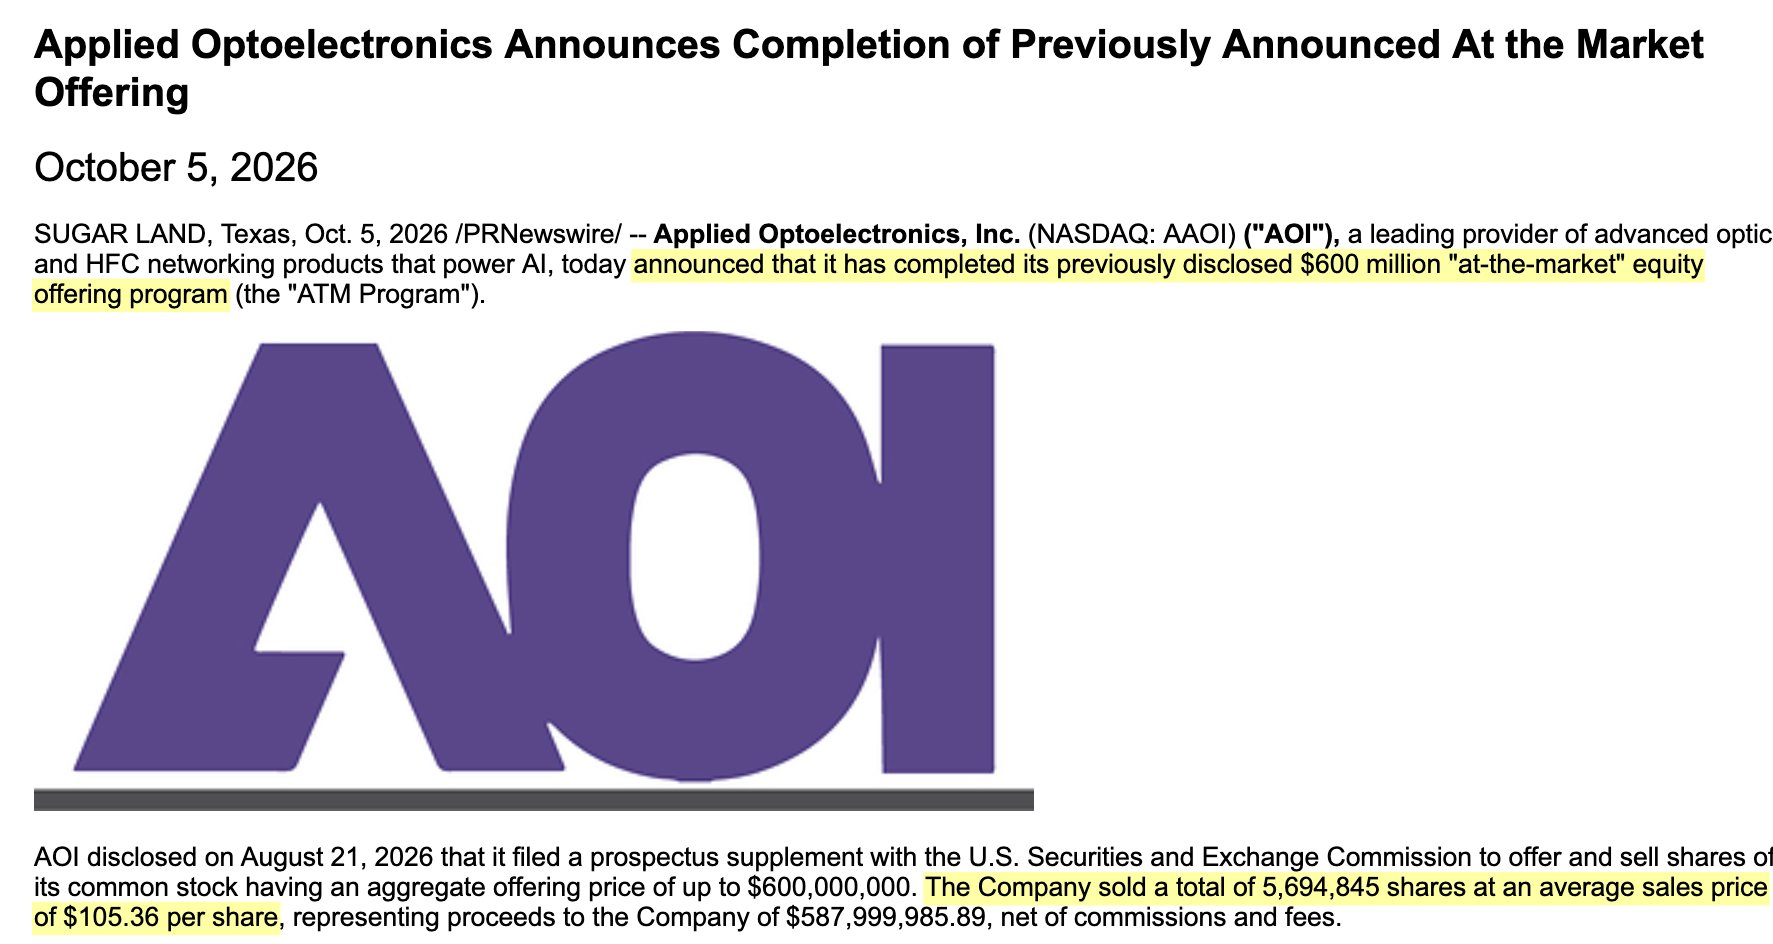
$AAOI is... finally... done...
With their $600m ATM program, turns out it's ~$105.36 average.
I do think AOI outperforms $LITE, as long as they stop filing these ATM programs.
Just due to their sheer magnitude of ramp with $471m/month transceiver revenue + 400K/month ELSFP coming up.
💬 引用 Serenity (@aleabitoreddit)
$AAOI has finished a $500m ATM In April.. $600m ATM in June. Then filed another $600m in August.
It's out of my control if management wants to abuse this trash repeated ATM structure. Instead following $AXTI like LTA prepayments and using that to fund buildout.
Or taking private placements like $NVDA + Nebius for $2B and using that to fund buildout.
Or convertible notes at 40% premiums.
It's really hard for the stock to break out of $100 or $150 or $200 if there's $600M of selling pressure at those levels (and maybe expectations of future ATMs).
I had the same criticism with $IREN with their $6B ATM, which is why it's been rangebound for half a year. And I'll say the same thing with my own thesis names too.
I see $AAOI operationally very bullish for 2027, with $471m/month transceiver revenue. 400k ELSFP units/month entering 2028.
The revenue ramp is absurd and can compress to single digit forward P/E.
But I find it hard to get excited over funding infinite ATMs during the buildout, when you're sacrificing opportunity cost with names currently profitable like $SNDK or Samsung.
I think a lot of retail investors conflate stock performance with how a company is doing operationally.
$AAOI is capitalizing on a bottleneck with high demand visibility, but stock has been going nowhere near-term with repeated ATMs.
I do expect AOI to strongly outperform (especially in 2027) if they stop issuing these stupid ATMs.
原帖:https://x.com/aleabitoreddit/status/2103151990146801812
翻译:
$AAOI …终于…完成了…
他们的 $600m ATM 计划,平均约为 $105.36。
只要他们停止提交这些
Comments
Unlock
ATM 计划,我认为 AOI 的表现会优于 $LITE。
仅凭其庞大的规模,月收入 $471m 的收发器业务,加上即将到来的每月 400K 的 ELSFP。
💬 引用 Serenity (@aleabitoreddit)
$AAOI 已在四月完成了 $500m ATM,六月完成 $600m ATM,随后在八月又提交了 $600m。
如果管理层想要滥用这种重复的 ATM 结构,这超出了我的控制范围。与其像 $AXTI 那样使用 LTA 预付款来资助建设,不如采用类似 $NVDA + Nebius 的私募融资,筹集 $2B 用于建设,或以 40% 溢价发行可转债。
如果在这些价位上有 $600M 的卖压(以及未来 ATM 的预期),股票很难突破 $100、$150 或 $200。
我对 $IREN 的 $6B ATM 也有同样的批评,这也是它半年来横盘的原因。我对自己的投资论点也持相同看法。
我认为 $AAOI 在 2027 年的运营前景非常看好,月收入 $471m 的收发器业务,2028 年每月 400k 的 ELSFP 单元。
收入增长异常强劲,市盈率有望压至个位数。
但在建设期间不断融资无限的 ATM,让我难以提起兴趣,因为这会牺牲像 $SNDK 或 Samsung 这类目前已盈利公司的机会成本。
我觉得很多散户把股票表现与公司运营状况混为一谈。
$AAOI 正在利用需求可视化的瓶颈进行资本化,但短期内因重复的 ATM 而股价停滞不前。
如果他们停止发行这些愚蠢的 ATM,我预计 AOI 将大幅超越(尤其在 2027 年)。
Comments
Unlock
原文:
$LITE CEO: "Next year with the advent of CPO and NPO in 2027, our estimates are that we'll be undershipping demand...
By 70%. Literally 70%. So we can only supply 30%.
And this has caught us by supply. By 2029-2030, we get to some level of balance."
Source: Global Photonics Economic Forum Day 1 (7:57:15 - 7:58:00)
Any other players with laser capacity coming online are probably going to get more market attention soon.
翻译:
$LITE CEO: “明年随着2027年CPO和NPO的出现,我们估计需求将出现供不应求...
缺口达70%。真的70%。所以我们只能供应30%。
这让我们陷入供给困境。到2029-2030年,供需将达到某种平衡。”
来源: Global Photonics Economic Forum Day 1 (7:57:15 - 7:58:00)
其他即将投产激光产能的玩家可能很快会获得更多市场关注。
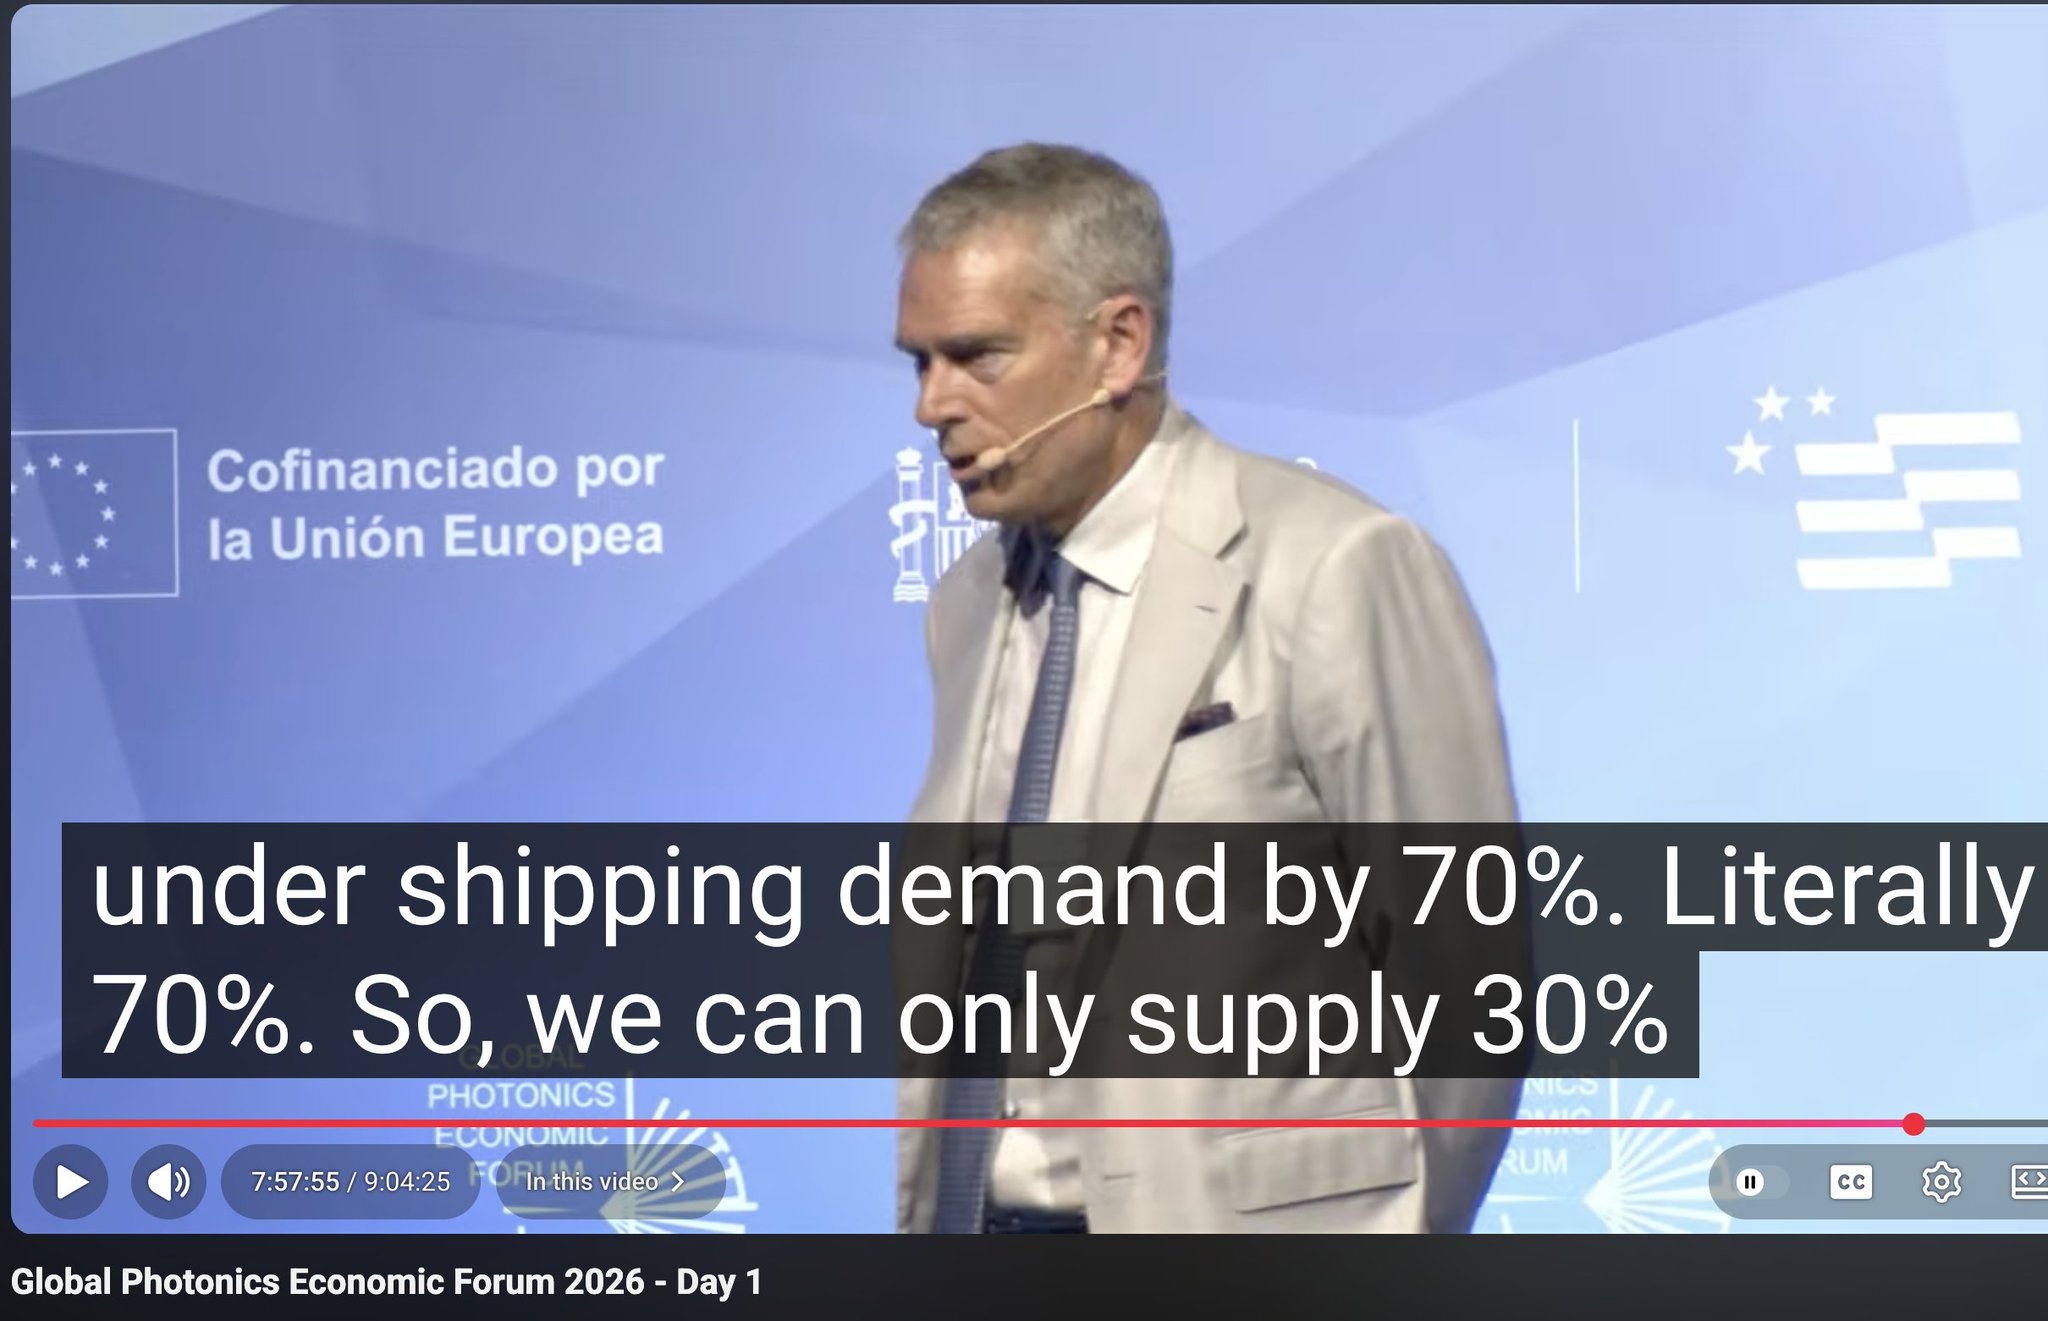
$LITE CEO: "Next year with the advent of CPO and NPO in 2027, our estimates are that we'll be undershipping demand...
By 70%. Literally 70%. So we can only supply 30%.
And this has caught us by supply. By 2029-2030, we get to some level of balance."
Source: Global Photonics Economic Forum Day 1 (7:57:15 - 7:58:00)
Any other players with laser capacity coming online are probably going to get more market attention soon.
翻译:
$LITE CEO: “明年随着2027年CPO和NPO的出现,我们估计需求将出现供不应求...
缺口达70%。真的70%。所以我们只能供应30%。
这让我们陷入供给困境。到2029-2030年,供需将达到某种平衡。”
来源: Global Photonics Economic Forum Day 1 (7:57:15 - 7:58:00)
其他即将投产激光产能的玩家可能很快会获得更多市场关注。
Comments
Unlock
原文:
"Potential FCC rules on optical transceivers more likely to come at 3.2T" - $LITE, $AAOI, $COHR, $SIVE.
Morgan Stanley met with Washington officials:
- Restrictions would likely start at 3.2T modules made in China (800g/1.6T would be left alone)
- Potential restrictions would likely keep laser market tight (combining US DSPs + lasers could meet the 65% US value threshold per MS)
- Chinese modules could qualify if 65% of bill of materials is US content. Chinese modules using US DSPs and lasers are already near that level
- Analysts expect the positive impact on laser pricing... to be more important than any broad redistribution of transceiver market share.
- Analysts don't expect this to bottleneck hyperscaler AI buildouts, they name InP substrate supply as the key variable to watch (hello $AXTI )
TLDR:
Component suppliers in general are really positive. Like $SMTC probably winner here for TIAs/drivers (I don't think this was listed), maybe $MXL for DSPs too.
$AAOI another large beneficiary.
$SIVE is high-key alpha for laser beneficaries since they have "tremendous capacity" coming online, and that points to US foundries (they haven't formally disclosed location).
Since previous slideshows show 2 US foundries 1 Taiwan foundry (Win Semi) in terms of their capacity partnerships. And it's process of elimination.
From CIOE Channel checks it does look like they're starting to work with Chinese pluggable players, (so they'd avenues moving forward as US supply chain component beneficiaries).
Of course $LITE / $COHR would be happy.
TLDR: Western supply chains for Lasers / DSPs / TIAs / others are already bottlenecked but qualified capacity becomes even more important.
翻译:
“潜在的 FCC 对光收发模块的规则更可能在 3.2T 时出台” - $LITE、$AAOI、$COHR、$SIVE。
摩根士丹利与华盛顿官员会面:
- 限制可能从中国制造的 3.2T 模块开始(800g/1.6T 将被保留)
- 潜在限制可能使激光市场保持紧张(美国 DSP 与激光器组合可满足摩根士丹利所说的 65% 美国产值门槛)
- 若物料清单中
Comments
Unlock
65% 为美国内容,中国模块仍可合规。使用美国 DSP 与激光器的中国模块已接近该比例
- 分析师预计激光价格的正面影响……将比任何大范围的收发模块市场份额重新分配更重要
- 分析师不认为这会成为超大规模 AI 部署的瓶颈,他们将关注 InP 衬底供应作为关键变量(你好,$AXTI)
要点:
整体来看,元件供应商持非常乐观的态度。比如 $SMTC 可能在 TIA/驱动器方面获胜(我认为这未被列出),$MXL 也可能在 DSP 方面受益。
$AAOI 将是另一大受益者。
$SIVE 对激光受益者来说是高潜力,因为他们有“巨大的产能”即将上线,这指向美国代工厂(他们尚未正式披露地点)。
此前的幻灯片显示,容量合作伙伴中有 2 家美国代工厂和 1 家台湾代工厂(Win Semi),属于排除法的结果。
从 CIOE 渠道调查来看,他们似乎已经开始与中国可插拔厂商合作(因此未来可能成为美国供应链元件的受益渠道)。
当然 $LITE / $COHR 会感到满意。
要点:西方激光、DSP、TIA 等供应链已经出现瓶颈,但合格产能将变得更加重要。
Comments
Unlock
Loading...