原文: I think we're seeing AI server MLCC demand cause an interesting effect... with tightening capacity for consumer/general-purpose MLCCs.
If you get Vietnam flashbacks like I do to $MU / Samsung / SK Hynix -> Legacy DRAM:
My thesis is we'll see the same thing here maybe late H2, early 2027 with consumer/broad MLCCs.
From July 6th:
"the crowding-out effect from AI-oriented high-end MLCC production has begun spilling over into both the automotive and consumer markets."
July 28th:
"AI Demand Pushes Japanese and Korean MLCC Suppliers to Record Monthly Shipments; Consumer-Grade Order Spillovers Continue to Surge"
Aug 12:
As [MLCC] capacity shifts from consumer grades to AI-oriented products... (Trendforce)
Aug 12:
China's electronics market channel checks found 22µF and 47µF MLCCs (used more broadly) out of stock. Then found and said certain manufacturers had stopped taking orders.
(for reference: Walsin said high-volume smartphone/PC products such as... 22µF, so it's broader MLCCs)
Obviously Samsung Electro-Mechanics/Murata are main beneficiaries of AI server MLCC ramp.
But companies with large market share of overall MLCCs like Taiyo Yuden (6976, disclosure: I have positions) with less AI server share, would be a major beneficiary of this.
Fun part is, we're only in H2 2026, so the next major bottleneck should be fun!
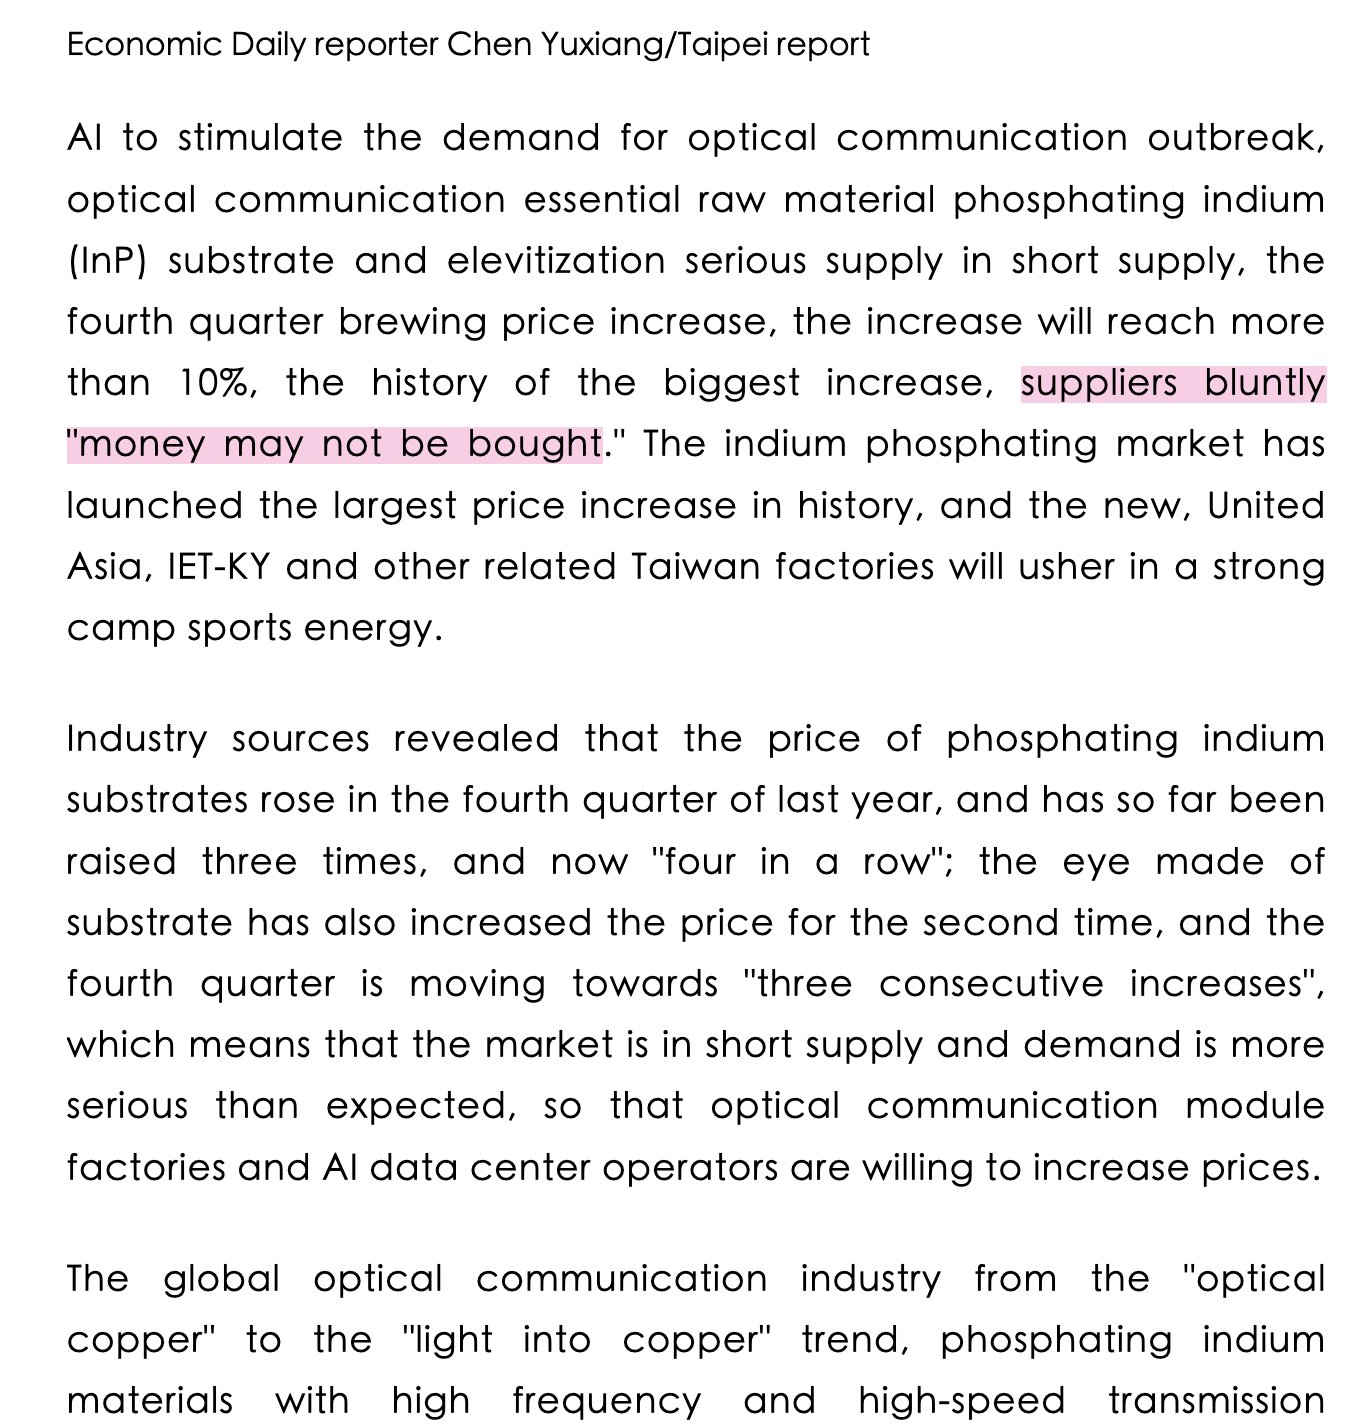
Suppliers have bluntly stated that "even if you have the money, you still may not be able to get the material" (lol).
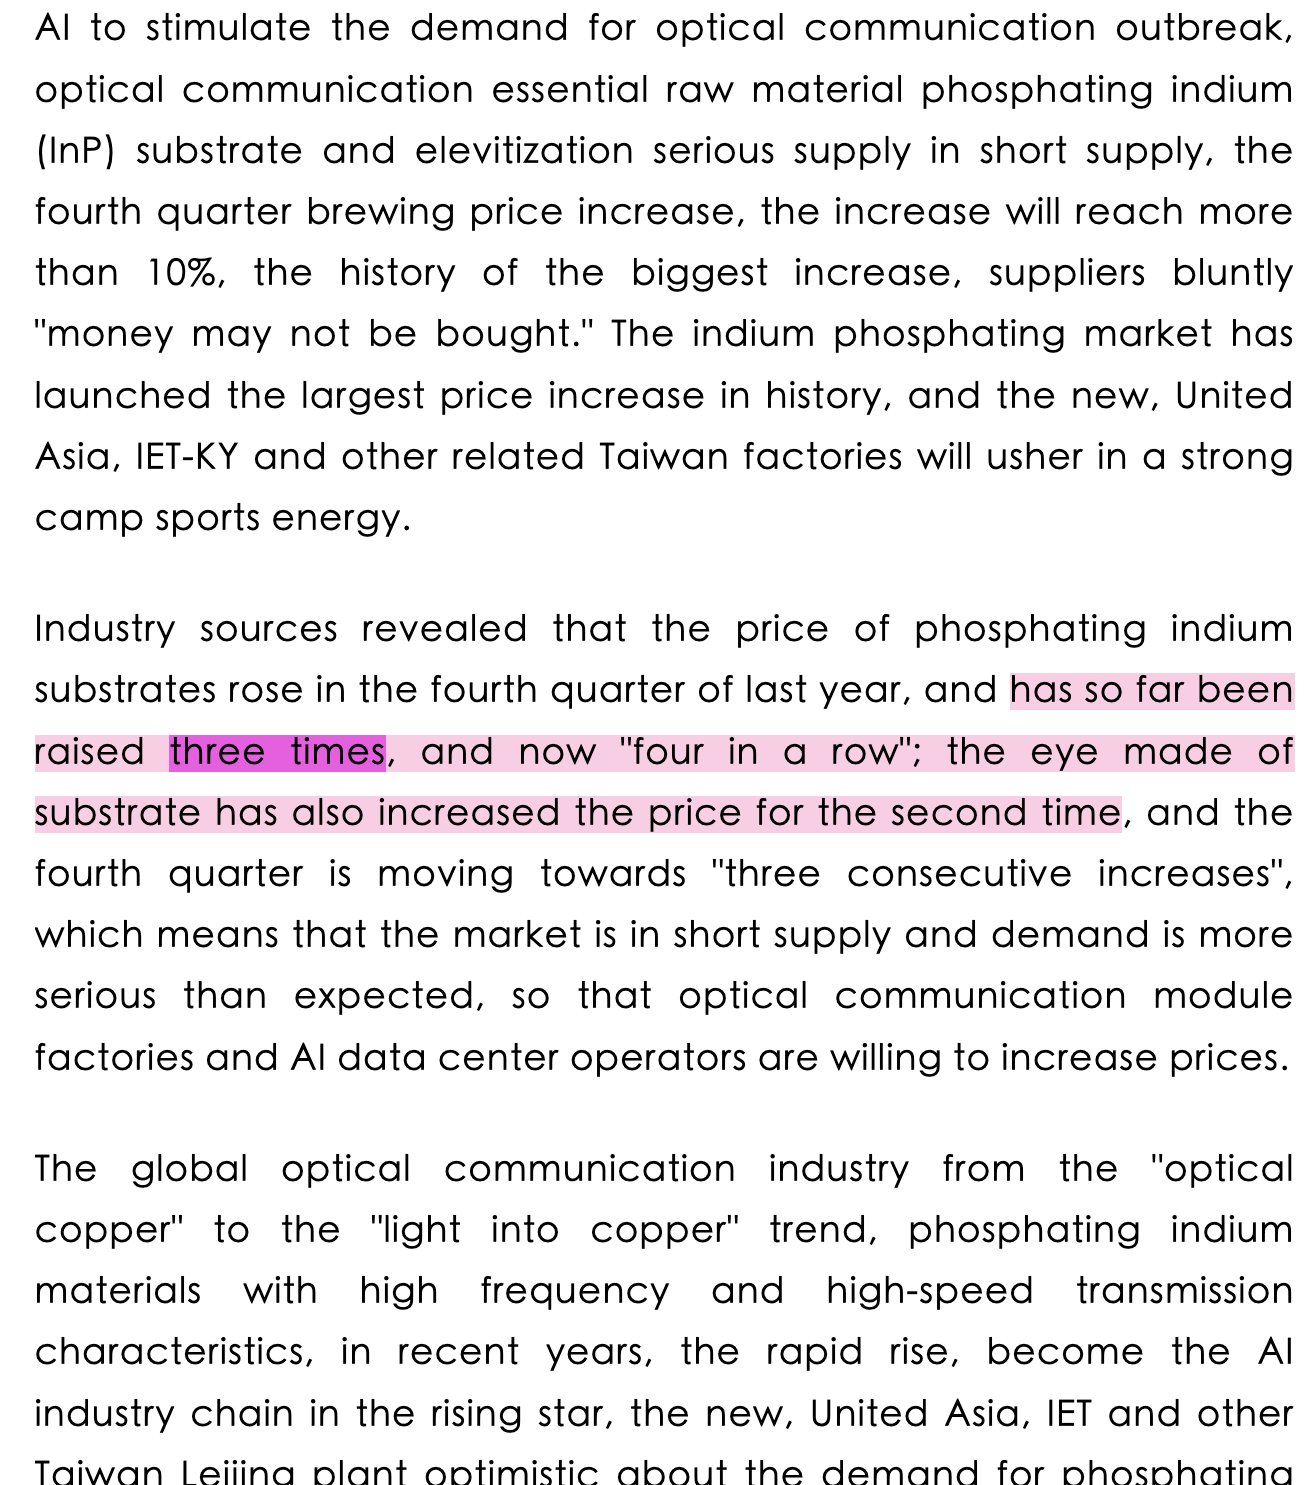
- Industry sources revealed that InP substrate prices began rising in Q4 last year and was the fourth consecutive substrate price hike.
- The latest Q4 hike is expected to be >10%,
- Meanwhile, prices for epitaxial wafers made from those substrates have already been raised two times, and the market is moving toward a 3rd consecutive increase in Q4. (I also wrote a thesis on $IQE, which benefits here too).
Article states VPEC, Landmark, IET benefits (Taiwan centric reporting).
I did predict this last year... The bottleneck is real, but I do have higher expectations for price hikes that comes next.
face not only memory shortages but also tight ABF substrate supply over the next few years"...
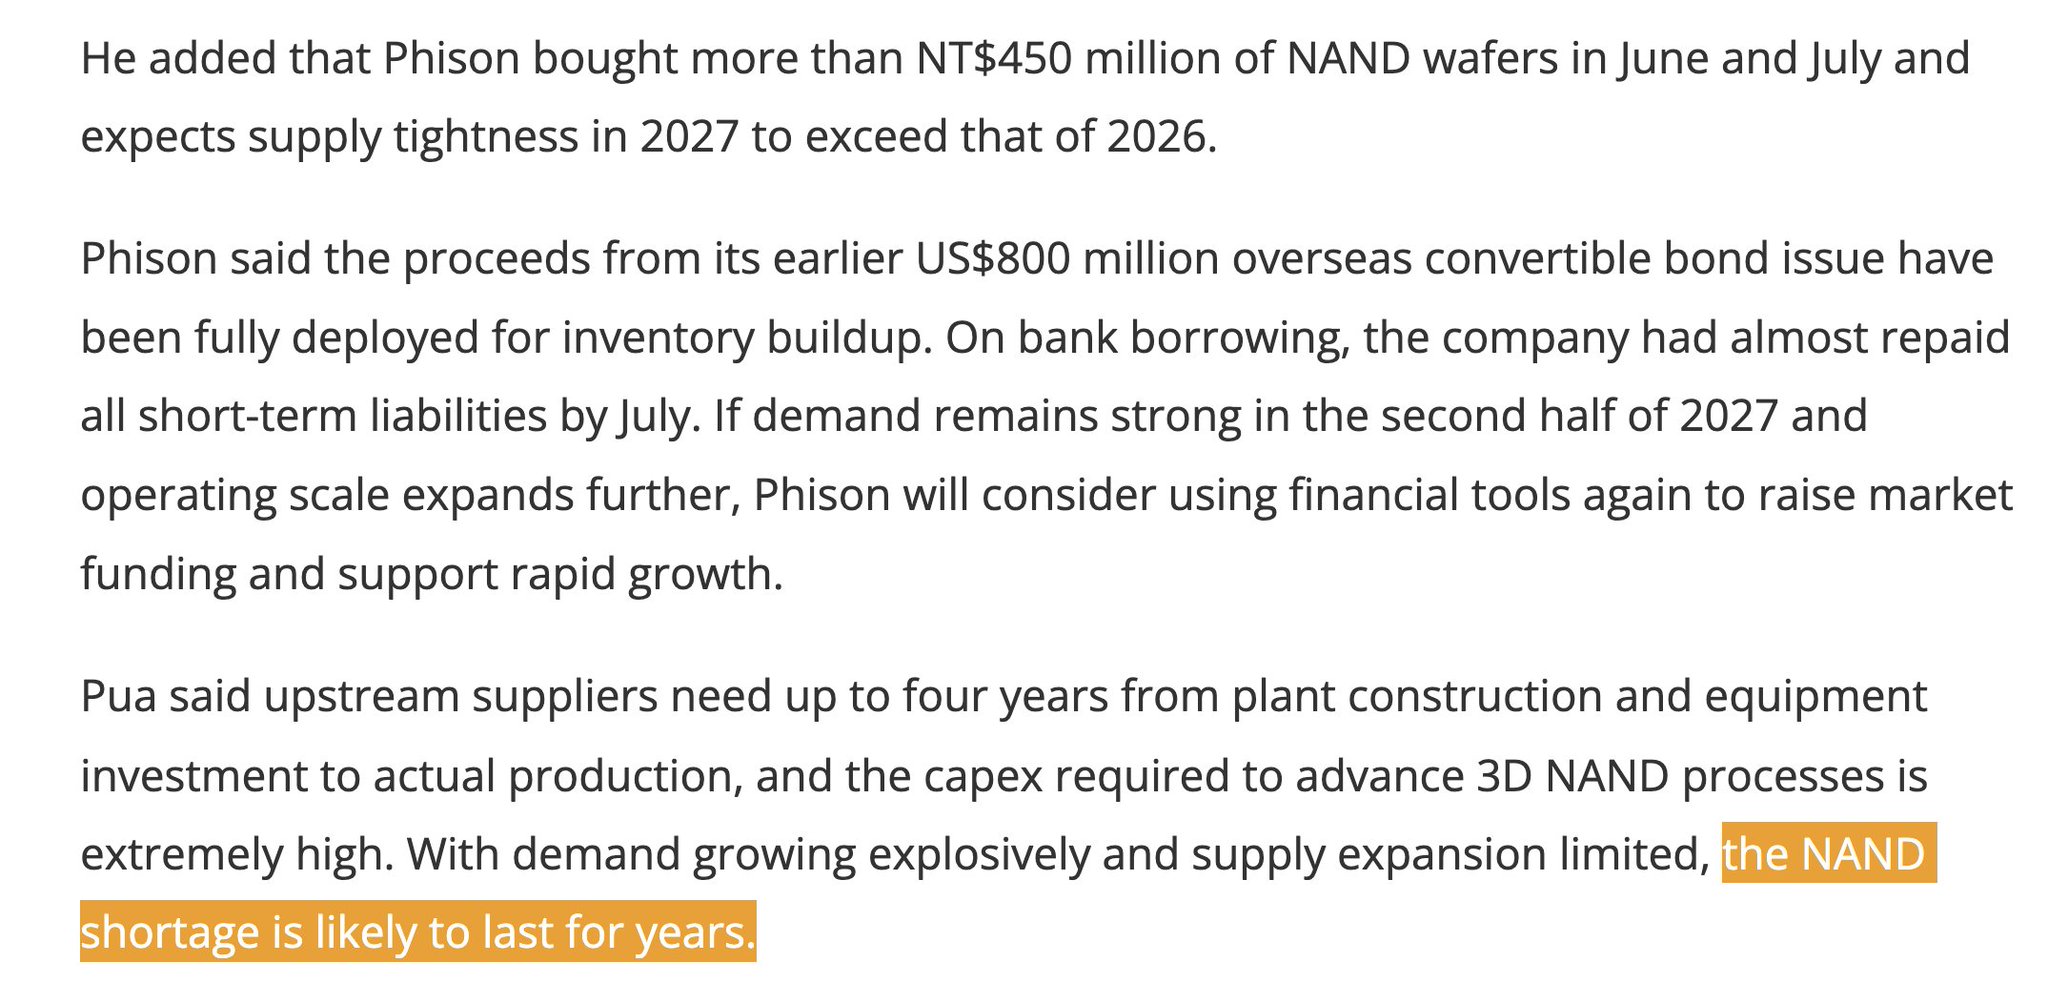
Emphasis on few years for memory + ABF substrates for bottlenecks.
Even upstream abf substrate equipment providers are happy, eg. Eternal Precision which uses vacuum lamination equipment stated orders surged, their plants have been running at full capacity, and 20%+ price hikes.
- $AMAT expects advanced packaging revenue to grow >70% in 2026, versus prior >50%, and said customer discussions now extend all the way to 2030
(not too familiar with this company, but found their growth rate from 2025 Q4 $6.8B ->$7.01B -> 7.91B -> $9.12B -> $10.25B Q4 2026 projections pretty interesting)
- Google said at OCP APAC said conventional 48V is running out of headroom. $NVDA detailed an 800VDC MGX-compatible rack H2 2026 (timeline, Delta / Lite-On beneficaries)
- Aside from $SNDK, Nanya LTAs cover 50% of capacity. CXMT signed multi-year DRAM agreements last month, so entire memory industry seems to be following same playbook as ur big 3.
- Probe cards remain a bottleneck, MPI(6223) said their probe card capacity remains fully utilized because demand exceeds supply.
Already covered the CW laser bottleneck with $AAOI, $SIVE, and $LITE earlier this week, but that's another fun one.
- some MLCC/component lead times have hit 36 weeks per Nichidenbo.
Your Samsung Electro-Mechanics, Taiyo Yuden, Murata, players should be very happy to hear this.
- $SNDK 80% adjusted gross margins projections through 2030, ~75% operating margins and ~50% adjusted FCF margins from investor day.
LTAs already 2/3rd of 2028 output. Minimum contracted revenue reaches $93B (MC is currently ~$239B)... Hard to be a cyclical stock when your revenue/targets are expected to continue 4Y later into 2030.
- $CRWV signs contracts for 6Y old $NVDA A100 GPUs through 2029.
For Neoclouds like Nebius/Iren, this is positive, since it's a counterargument for eg. Burry depreciation short thesis
- conventional DRAM gross margins eg. Micron is estimated to reach an unprecedented 95% by 2027, surpassing HBM GMs per UBS
read through for legacy/standard dram players like Nanya/Winbond should go brrrr if projections are correct.
- Anthropic reportedly achieved 14x+ YoY growth and roughly 2.4x sequential revenue growth q2 to >$11.5B,. estimating growth to $190–200B in 2028r evenue numbers.
Your frontier labs keep growing at stupidly fast paces, it would be worrisome if they didnt.
- $NVDA reportedly in talks to invest $3B in SB Energy (Softbank subsidiary), creates a >$500B compute financing push with Apollo, BlackRock, Blackstone, Brookfield, Goldman, and others. $NVDA Feynman reportedly moves to TSMC A16 + SoIC + custom HBM + CPO in H2 2028
Just more nvidia news every day
- $MSFT Maia 300 discussed $TSM capacity for >300k units in 2027, with expansion to 1m+. Unveils as soon as September.
Likely $MRVL should be more happy from this news. For what's happening right now:
- maybe GUC for Microsoft current ASIC ramp. - For the Amazon party, stuff like Alchip (I do own shares), likely is ramping now with $AMZN ASIC program H2 2026...
So might be a good idea to look at hyperscaler ASIC ramp timelines + their beneficiaries.
- $TSM VP of Advanced Packaging stated "the industry is likely to
原文: My weekend X feed is getting pretty sad. The main things I've seen were:
- Harvard endowment going degen with $SPCX, and + $AMD, $NVDA disclosing billions - AI agent microcosm implications on RuneScape - Hormuz getting renamed to Straight of America - Jane Street getting wiped $15B by Citadel - ____ who's hedge fund is up 30% every year buys a .00005% position my favorite stock _____! - Bunch of noisy motivational quotes or bad takes on trading