觅信聚合
我的关注
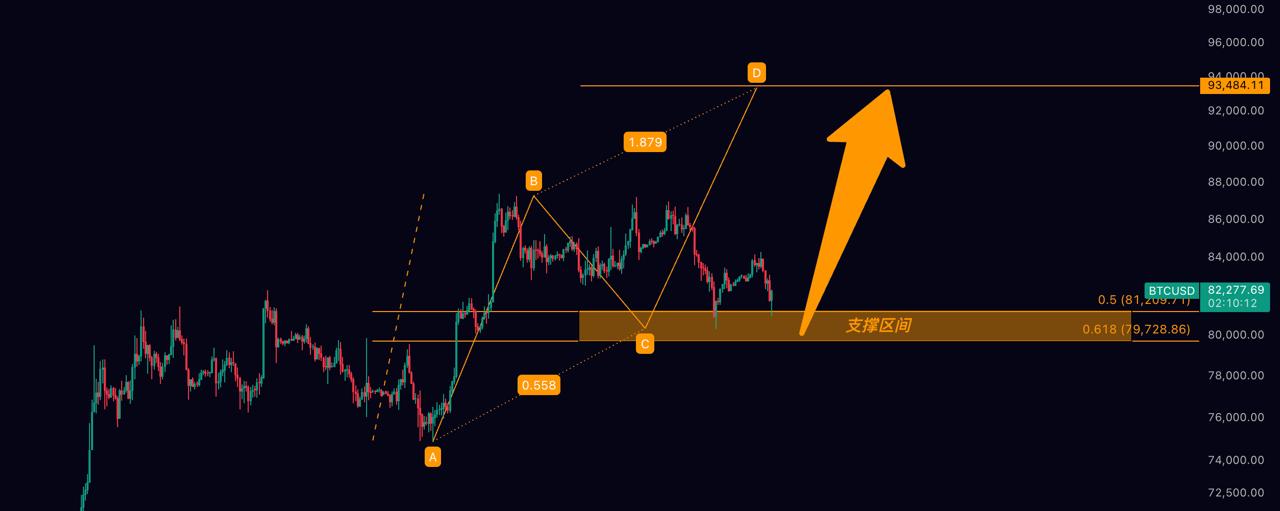
目前价格维持在82800下方,也就代表自从9月21日开始的向上突破,突破失败了,至少目前盘中表现是突破失败了,突破失败了,这个位置,就一定不能看涨了。这个时候就需要关注看跌的逻辑,尊重盘面事实情况。接下来把几个看跌逻辑发出来,大家参考下。
Comments
Unlock
...
Comments
Unlock
给大家梳理下盘面情况
...
Comments
Unlock
https://youtu.be/Qm0ry6vJIlQ
比特幣,BTC三天反彈一根吞掉!頸線得而復失?空...
專注分析BTC比特幣日內短線行情走勢
社群:https://t.me/SwordsmanDBK
本人:https://t.me/dbk9527
註冊交易bitget交易所,即刻加入!
帮助节约手续费20%-50%,Bitget注册链接
https://partner.bitget.cafe/bg/791k7481
#Bitcoin #BTC #比特币 #比特幣 #加密货币 #币圈 #以太坊 #ETH #BTC行情 #比特币...

比特幣,BTC三天反彈一根吞掉!頸線得而復失?空...
專注分析BTC比特幣日內短線行情走勢
社群:https://t.me/SwordsmanDBK
本人:https://t.me/dbk9527
註冊交易bitget交易所,即刻加入!
帮助节约手续费20%-50%,Bitget注册链接
https://partner.bitget.cafe/bg/791k7481
#Bitcoin #BTC #比特币 #比特幣 #加密货币 #币圈 #以太坊 #ETH #BTC行情 #比特币...

...
Comments
Unlock
Comments
Unlock
2026年10月13日早间
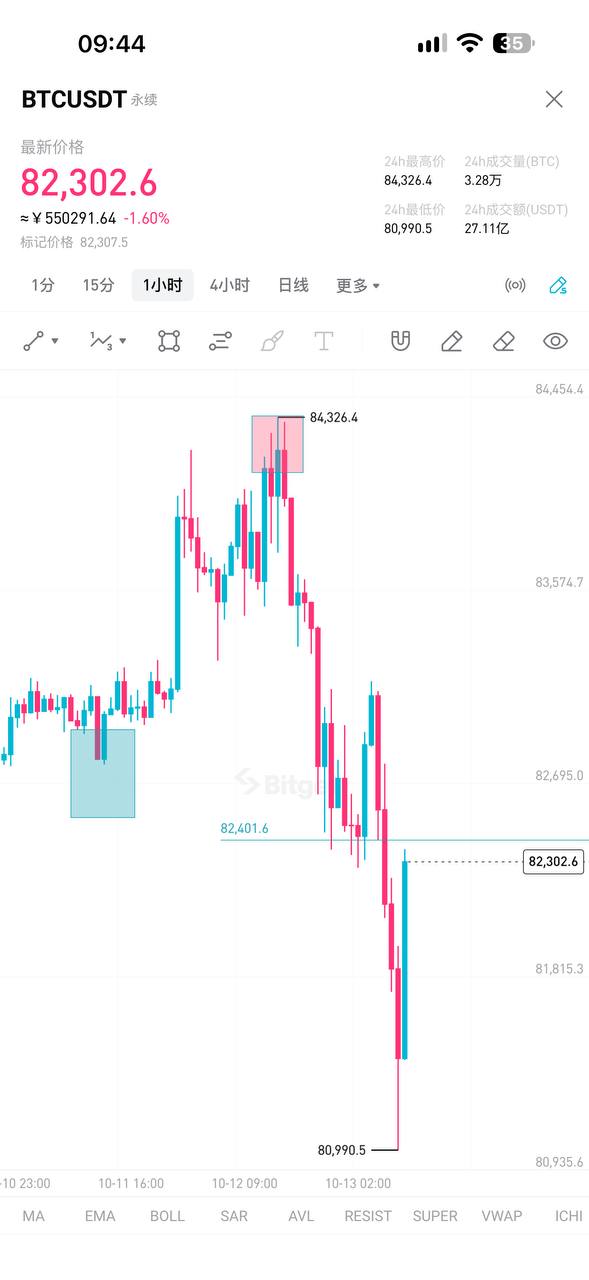
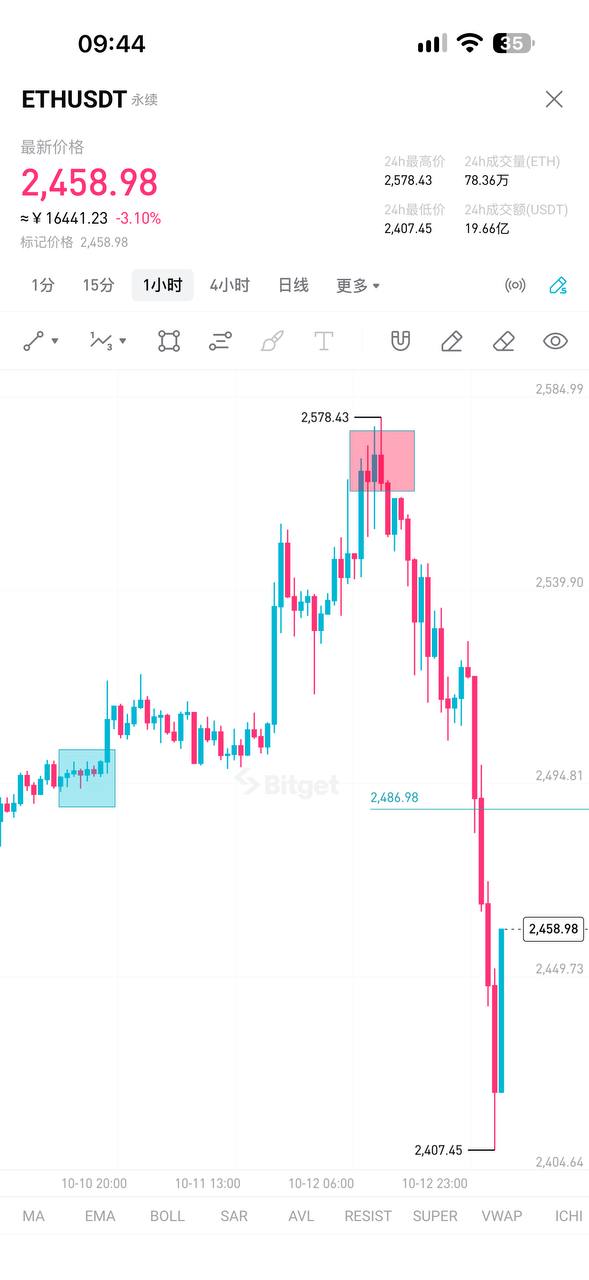
盘面基调:短线偏空,10月9日以来的反弹已经结束。昨天下午冲到84300没有站住,今天凌晨4小时收出看跌吞没,收线又回到三重顶的颈线82500下面,4小时MACD在零轴跟前掉头死叉,日线一根阴线把三天的涨幅几乎全部吞回,收线也回到了82300下面。但是10月9日的低点80300没有破,这一段是减仓跌下来的,现在是回调重新往下、还没有走出新低。刚才早上在下探81000后有了反应,正在上测关键位82500。4小时趋势线和两套斐波位都挤在这一带;如果4小时收线回到82500上面,偏空的看法就要改,往上先看83100,再往上84000,但是站不稳82500-82800,则偏空延续
BTC核心关键位:82500
BTC日线多空分界线:82300
上方压力位:83100、84300、87000
下方支撑位:81600、81000、80300
...
Comments
Unlock
Comments
Unlock
提阿非罗大人
· User uploads
·
BTC上下插針!究竟要去哪?周線大級別分析!
Comments
Unlock
做交易一定不能冲动。
新手都会犯同一个错误,那就是上头,做错了一单,马上就会又做一单,完全不顾有没有交易信号。请问这样盈利单有什么意义?那如果又做错了呢?等待你的只有无尽的深渊。
...
Comments
Unlock
where more capacity comes online like test or DRAM. So it's a lot more nuanced than capex down = everything down or vice versa.
I also slightly agree with community agreements that open weight models wouldn't lessen demand on AI infrastructure (otherwise $NVDA wouldn't be funneling funds into Reflection), but all the contractual obligations that Anthropic has might get messy if their models/company get cannibalized.
Either way, I'd expect some of these frontier lab valuations to likely compress but I do think Jensen knows what he's doing though to avoid contagion.
But basically:
- Extremely difficult market now, can't just throw money at any AI supply chain company like $GLW and expect it to go up. There's cause for concern of rate hikes mixed with financing per $AVGO CEO but not to the point you just blindly sell off everything.
Also I think markets are stupid and ties baskets together so that leads to mispricing + individual buying opportunities with certain chokepoints too.
If capacity + demand is visible and forward p/e compresses like $AAOI to single digits off hundreds or thousands of percent growth from hyperscalers off $471m transceiver revenues and hundreds of thousands of monthly ELSFP capacity. Or $SIVE coming online with 100M+ laser capacity + multiple foundries with ASP hikes on lasers. I wouldn't lump them into other AI supply chain names in IP like $RMBS or others.
My take is that AI supply chain beneficiaries with closer inflection points, demand visibility, and forward P/E compressing due to economic leverage would likely outperform medium term despite current volatility.
TLDR:
- Memory strongest risk/adjusted return with LTAs + pricing floors extending to 2030's + buybacks.
- My opinion is that optical supercycle for 2027-2028 with CPO/NPO is going to look absurd relative to capacity coming online of smaller suppliers.
-
...
Comments
Unlock
Overwhelming fundamentals/growth colliding with sht macro + media scares
- Markets are stupid and groups things in baskets and sells them all off together or buys overvalued names, creating short/long opportunities
I'd give a prayer to people on short term options given underlying drop + IV decline, but there could be a reversal... who knows. Most valuable thing right now is time.
💬 引用 Wolfex (@Wolfex_Yeat)
@aleabitoreddit @SiversSemicond Serenity please give us some cope we are panicking out here with photonic stocks and memory 😭
原帖:https://x.com/Wolfex_Yeat/status/2109748007386087814
翻译:
好的……现在随意聊聊市场的想法,光学方面如 $LITE / 内存 + $IREN / Anthropic。
关于内存:
- 对 $MU / Samsung / SK Hynix 的需求可视性延伸至 2030‑2031。
- Samsung 已签订长期协议,覆盖其 70% 容量至 2031(可能带有 SK Hynix 类的价格底线)……其营业利润已经非常夸张。
- 市场普遍认为 2027 年的短缺将比 2026 年更为严重……甚至 $SNDK 的毛利率将提升至 80% 以上,进入 2030 年。
- 你会听到 Acer 以及其他 CEO 们在希望内存价格下跌时引用 CXMT/YMTC 和中国厂商的悲观案例。
- 但仅从 $NVDA 正在进行的供应采购加上超大规模算力提供商来看,未来 5 年的需求可视性已经非常夸张。到那时,这些买断/付费加价格底线合同产生的累计自由现金流可能超过它们的整体市值,感觉已经形成了某种基准。
- 短期总是波动的(隐含波动率在 $EWY、$DRAM、$MU 上大幅下降),因此持有看涨期权的投资者可能被炸得体无完肤,标的价格也随之下跌。
- 但如果 Samsung 2027 年预期是 3 倍,且已有 5 年长期协议锁定 70% 容量来自超大规模算力提供商,并且设有价格底线,那么这些公司出现持续崩盘的可能性就不大……
关于光学:
- $LITE 的订单已经售罄至 2029,正在讨论 2030 年的供货。需求可视性延伸至 2031……超大规模算力提供商基本上在为产能扩张提供资金。
- 其 2028 年在 Greensboro 的工厂扩建仅光学激光产能收入约 50 亿美元,且基本上已分配给 $NVDA(占比 50% 以上,并有进一步选项)以及渠道调查得到的其他客户。
- 现有供应链瓶颈极为严重,光学内容/XPU 在 2027‑2028 年将出现爆发式增长。
- 因此 DSP、TIA、光电二极管、激光器、InP/SOI 基板、晶圆(外延、SOI 等)都预计会“嗡嗡作响”。
- 那么这对 $AAOI、$SIVE、$MTSI 等将在 2027 年投产的大容量供应商意味着什么?或者其他玩家如 Sumitomo / Furukawa?
- 但这与内存的情况不同,因为在一个集群中 BOM 比例极低……如果 Micron/Samsung 再提升 2000% 超大规模算力提供商将破产。但对 InP 基板来说,这种提升似乎是可能的,或者 CW 激光产能翻倍。
- 我原本认为 $LITE 的市值超过 1000 亿美元相对其容量扩张而言被高估了,尤其是相对于更小光学玩家的市值。因此我选择相应的仓位(但 Lumentum 确实因需求可视性而值得溢价)。
对于领头羊如 $NVDA / $AVGO / $MRVL:
- Nvidia
Wolfex (@Wolfex_Yeat)
https://twitter.com/Wolfex_Yeat/status/2109748007386087814
@aleabitoreddit @SiversSemicond Serenity please give us some cope we are panicking out here with photonic stocks and memory 😭
...
Comments
Unlock
ongoing financing (think they're like halfway through their $6B ATM).
Just some hopium for $IREN investors, $NBIS also signed a deal with $META at the start of the year (but markets didn't care at all, since Nebius dropped to ~$70-80 at the lowest point?).
But did 6 months later, as the time to revenue inflection gets closer and you're past the ATM/capex window, markets would likely care more.
I don't think it's irrational but at the same time, the fundamentals have improved from Mirantis acquisition to others. I also think it was known for awhile it was either OpenAI/Anthropic from CEO comments earlier too?
But either way to be a more risk-off environment where funds seem to be rotating to larger names as a flight to safety.
$CRWD / $PLTR as just two example, but my take is that the valuations of these rotations are reaching clown levels. And that certain AI supply chain beneficiaries in comparison are undervalued now.
I was thinking markets would just rotate to names that are extremely profitable like Samsung or names that have <2X P/E, so it was surprising to see $KOSPI and some legacy memory players get sold off today.
Since all of this is colliding with uncertainty about sht macro environments and renewed sustainability concern of AI capex/commitments from frontier labs like OpenAI/Anthropic from due to that FT piece recently. I've always been sounding the alarm about the contractual backlog OpenAI has with $CBRS, $MSFT, $ORCL and others earlier in the year. But OpenAI did just raise $122B or so , so I don't quite think they're at risk of going down anytime soon.
I also don't think overall capex can just exponentially go up, but even if it stalls / hovers around a certain point or even drops...
Capex toward certain areas like optics will still explode as hyperscalers fight over allocations when CPO scale up comes about, but might drop in others
...
Comments
Unlock
原文:
Sure... Random train of thoughts on markets now, optics like $LITE / memory + $IREN / Anthropic.
On Memory:
- Demand visibility on $MU / Samsung / SK Hynix extend into 2030-2031.
Samsung has LTAs covering 70% of their capacity into 2031 (likely with SK Hynix type price floors)... and their operating profit is already absurd.
There's a consensus that shortage in 2027 will be much more severe than 2026... Even $SNDK expends gross margins to exceed 80% entering 2030.
You're going to hear Acer and other CEOs that want memory prices to go down cite bear cases like CXMT/YMTC, and Chinese players.
But just looking at supply procurement that $NVDA is doing + hyperscalers, demand visibility is absurd for the next 5 years. And by that time, cumulative FCF coming in from these take/pay + pricing floor contracts might exceed some of their entire marketcaps so it feels like there's some baseline.
Near-term is always volatile (IV dropped a ton across $EWY to $DRAM to $MU), so people with call options likely got nuked, along with underlying prices.
But if Samsung is 3x 2027E, has 5 year LTAs with 70% of capacity committed from hyperscalers, and price floors, it's kinda hard to see these names suffer a sustained crash...
For optics:
- $LITE is literally sold out into 2029, starting discussions into 2030. With demand visibility lasting into 2031… with hyperscalers largely funding the capacity buildout.
Their 2028 Greensboro fab expansion was ~$5B in UHP laser capacity revenue alone, yet it’s basically allocated toward $NVDA (50%+ with options for more) and co from channel checks.
Existing supply chain bottlenecks are extremely severe as optical content/XPU skyrockets entering 2027-2028.
So everything from DSPs/TIAs, photodiodes, lasers, InP/SOI substrates, wafers (epi, SOI, etc) are expected to go brrr.
And what does that imply to anyone else with
...
Comments
Unlock
enormous amounts of capacity coming online like $AAOI + $SIVE + $MTSI capacity expansion in 2027? Or other players like Sumitomo / Furukawa?
But again it's not quite the same situation as memory since the BOM % is extremely low in a cluster... If micron/samsung raised another 2000% hyperscalers would go bankrupt. But doing that for InP substrates seems possible. Or a 100% increase on CW laser content.
I actually thought $LITE was overvalued at $100B+ MC, relative to capacity expansion on your smaller optical players to their respective MCs. So I chose to position accordingly (But lumentum does deserve premiums for demand visibility).
For the companies leading the charge like $NVDA / $AVGO / $MRVL:
- Nvidia has 70% forward revenue growth FY2028 which is supply constrained growth.
- Broadcom 100% Y/Y for 2027/2028 which is also supply constrained growth.
- Marvell FY2031 upgraded guidance to $70B-$90B from $46B analyst projections...
They all seem to be very happy.... and read through on demand for next 2-3 years is enormous (also echoing what $INTC CEO said today on the panel with $AVGO CEO).
So you have overwhelming growth on memory + photonics + from the leaders... But the nuance is not everything in the AI supply chain get the same economic benefit.
HBM/Laser/CPU/MLCC and other players in the bottlenecks look to be printing money. And seem to be the largest beneficiaries of the current bottlenecks.
Test players are also getting price hikes + capacity allocated by players like $NVDA, but economic impact seems a tad lower than other players since forward P/E for many I modeled were still in the 45x+ range even if you hiked prices like 10-30%.
As for capex intensive players... there's some like $IREN ($25-30B for 2027) that despite a deal with Anthropic ended up dropping. I don't think markets seem to appreciate players spending a lot of money +
...
Comments
Unlock
https://x.com/cfsq143/status/2109818940126089409?s=20

共振交易系统~必到哥 (@cfsq143)
https://twitter.com/cfsq143/status/2109818940126089409?s=20
Age\-restricted adult content\. This content might not be appropriate for people under 18 years old\. To view this media, you’ll need to log in to X\. Learn more

共振交易系统~必到哥 (@cfsq143)
https://twitter.com/cfsq143/status/2109818940126089409?s=20
Age\-restricted adult content\. This content might not be appropriate for people under 18 years old\. To view this media, you’ll need to log in to X\. Learn more
...
Comments
Unlock
Comments
Unlock
...
Comments
Unlock
比特币现价82000做多
止损:80000
止盈:87000
止损:80000
止盈:87000
...
Comments
Unlock
🔄
Loading...