Comments
Unlock

觅信聚合
我的关注
Comments
Unlock
原文:
A very material catalyst came about for Western supply chains from $AAOI, $SIVE / Jabil, to $LITE and Coherent:
The Trump administration is drafting a ban of new Chinese optical transceivers and DC devices.
Which would likely hit China’s Innolight, Eoptolink, and other Chinese optical interconnect supply chains.
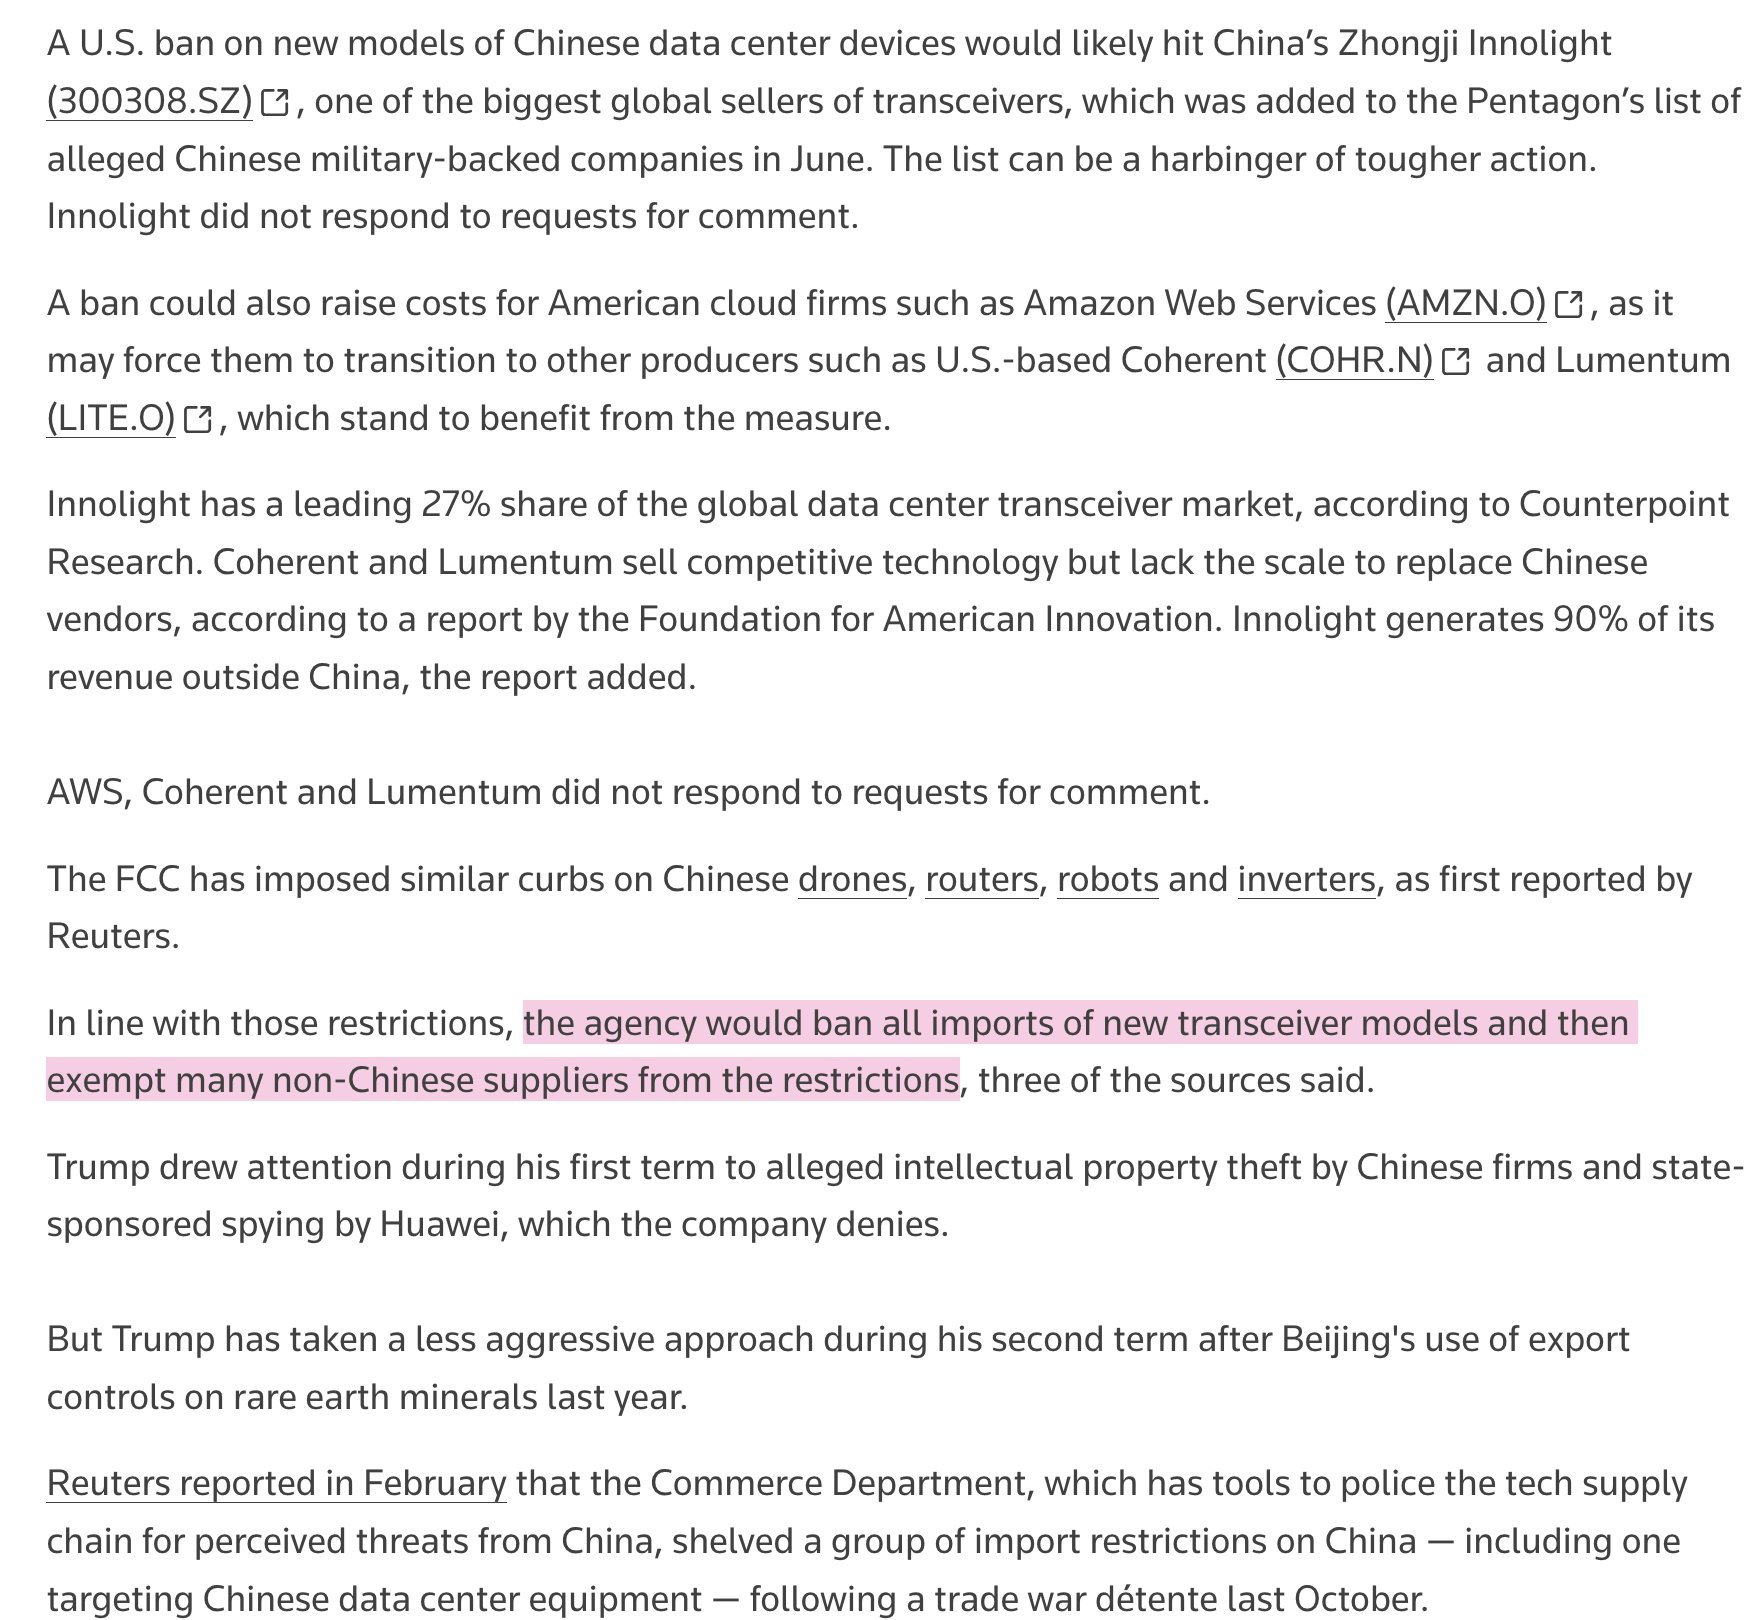
"The agency would ban all imports of new transceiver models and then exempt many non-Chinese suppliers from the restrictions"
We'll likely see a larger bifurcation of supply chains with even greater importance put on Western players.
翻译:
一个非常重要的催化剂出现在西方供应链中,从 $AAOI,$SIVE / Jabil 到 $LITE 和 Coherent:
特朗普政府正在起草一项禁止新型中国光学收发器和直流设备的禁令。
这可能会影响中国的 Innolight,Eoptolink 和其他中国光学互连供应链。
"该机构将禁止所有新型收发器的进口,然后豁免许多非中国供应商的限制"
我们可能会看到供应链的分化加剧,西方玩家将变得更加重要。
A very material catalyst came about for Western supply chains from $AAOI, $SIVE / Jabil, to $LITE and Coherent:
The Trump administration is drafting a ban of new Chinese optical transceivers and DC devices.
Which would likely hit China’s Innolight, Eoptolink, and other Chinese optical interconnect supply chains.
"The agency would ban all imports of new transceiver models and then exempt many non-Chinese suppliers from the restrictions"
We'll likely see a larger bifurcation of supply chains with even greater importance put on Western players.
翻译:
一个非常重要的催化剂出现在西方供应链中,从 $AAOI,$SIVE / Jabil 到 $LITE 和 Coherent:
特朗普政府正在起草一项禁止新型中国光学收发器和直流设备的禁令。
这可能会影响中国的 Innolight,Eoptolink 和其他中国光学互连供应链。
"该机构将禁止所有新型收发器的进口,然后豁免许多非中国供应商的限制"
我们可能会看到供应链的分化加剧,西方玩家将变得更加重要。
Comments
Unlock
原文:
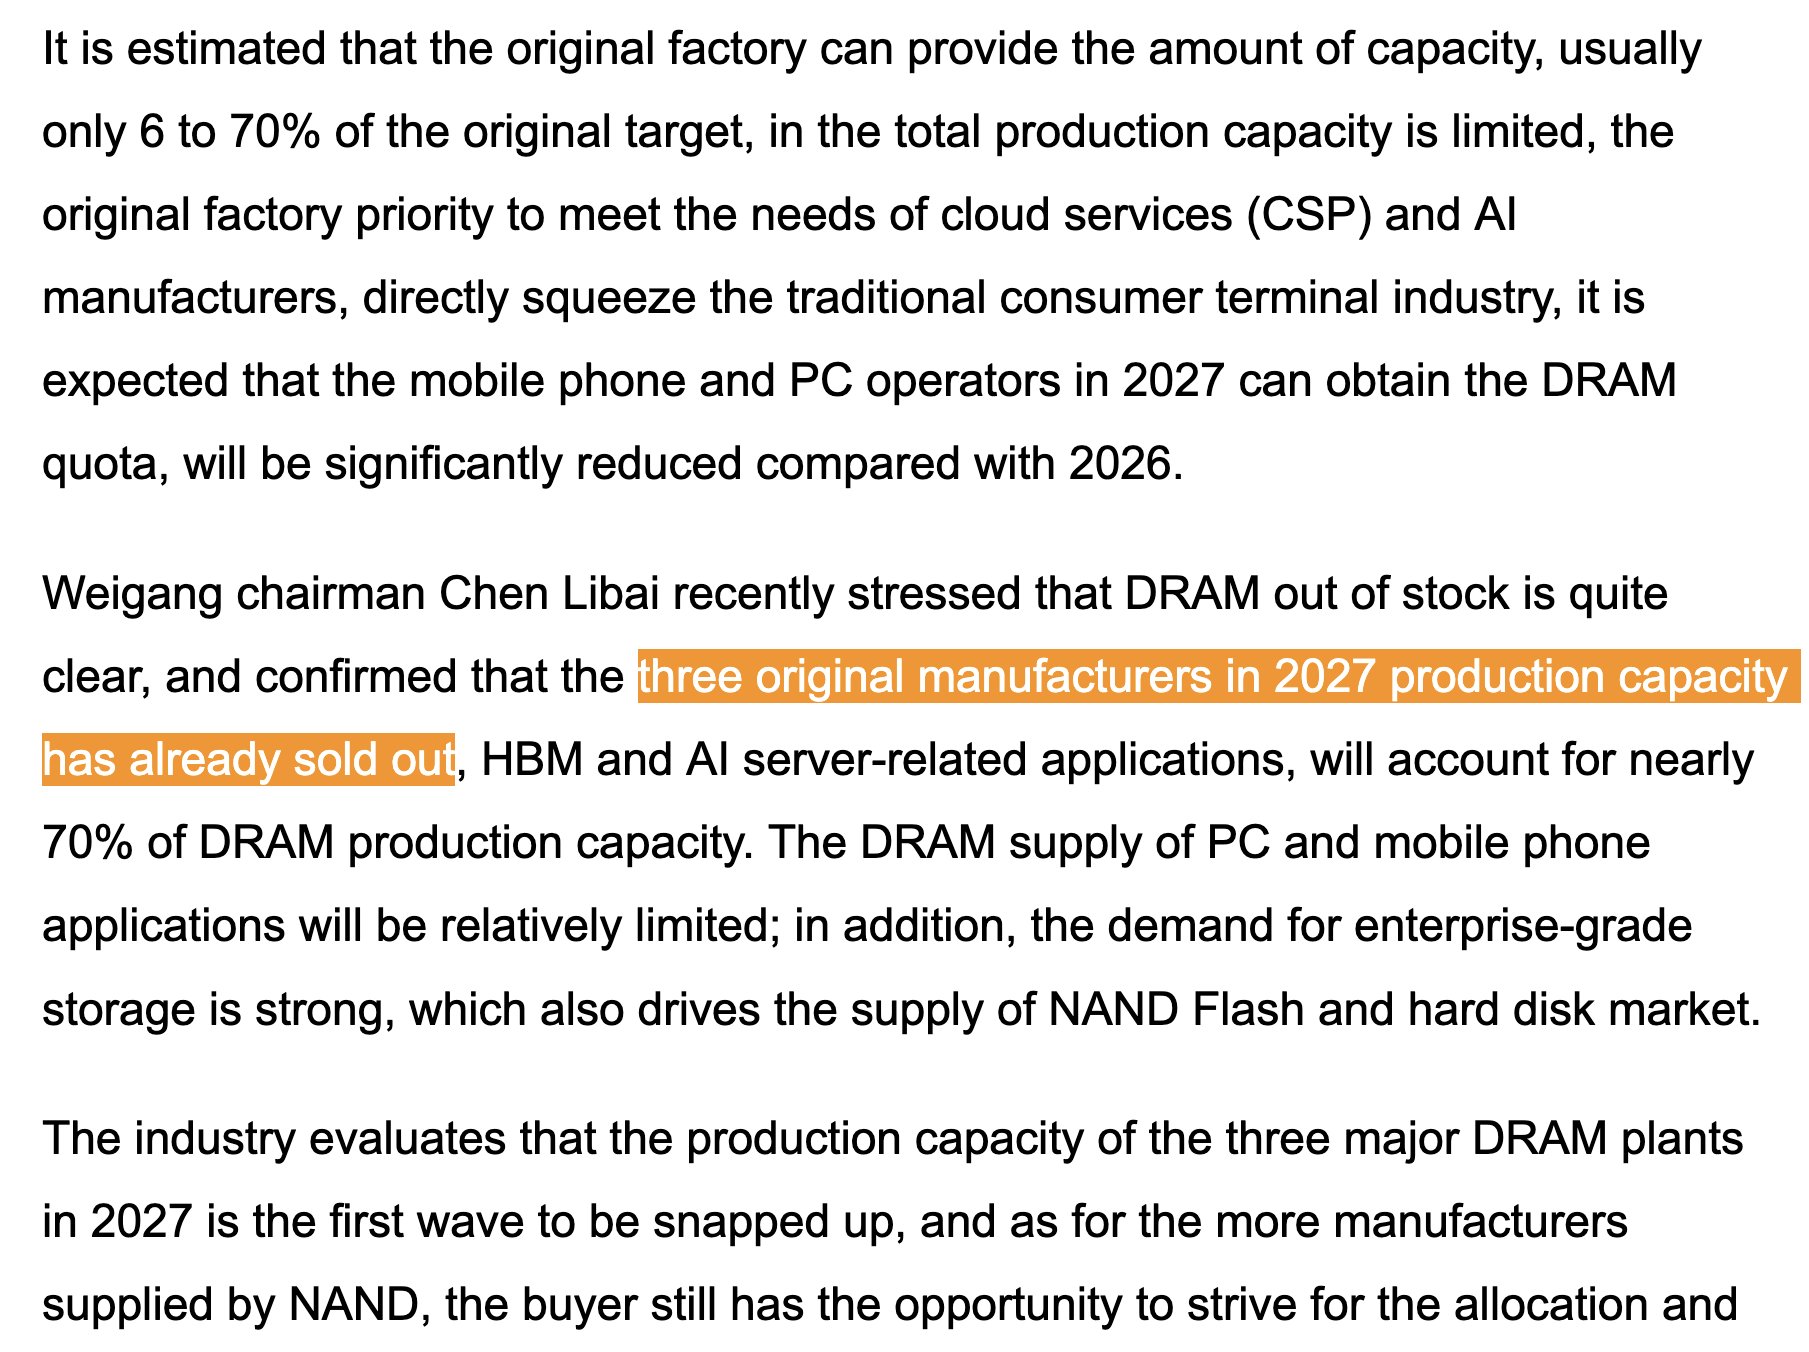
SK Hynix, $MU , and Samsung have sold out of 2027 capacity for DRAM/HBM.
$SNDK, Samsung, Micron current annual NAND capacity has been sold out, with Kioxia and SK Hynix expected to finalize allocations by August 2026.
- Customers are being allocated only 60–70% of the volumes they initially requested
- industry insiders pointed out that 2027 will enter the most severe moment of memory shortage
- Allocation amounts are mostly decided, but final shipment pricing will be determined closer to delivery
Source: Digitimes, citing industry sources.
Hard to see those memory "oversupply" claims in early-mid 2027 when they're all sold out of capacity already.
翻译:
SK Hynix,$MU 和三星已经售出了2027年的DRAM/HBM容量。
$SNDK,三星,美光当前年度的NAND容量已经售罄,预计京瓷和SK Hynix将在2026年8月之前完成分配。
- 客户只被分配了他们最初请求的60-70%的量
- 业内人士指出,2027年将进入内存短缺的最严重时期
- 分配量大多已经确定,但最终的发货价格将在交货前确定
来源:Digitimes,引用业内消息来源。
很难想象2027年初中期会出现内存“过剩”的说法,当时他们已经售出了所有的容量。
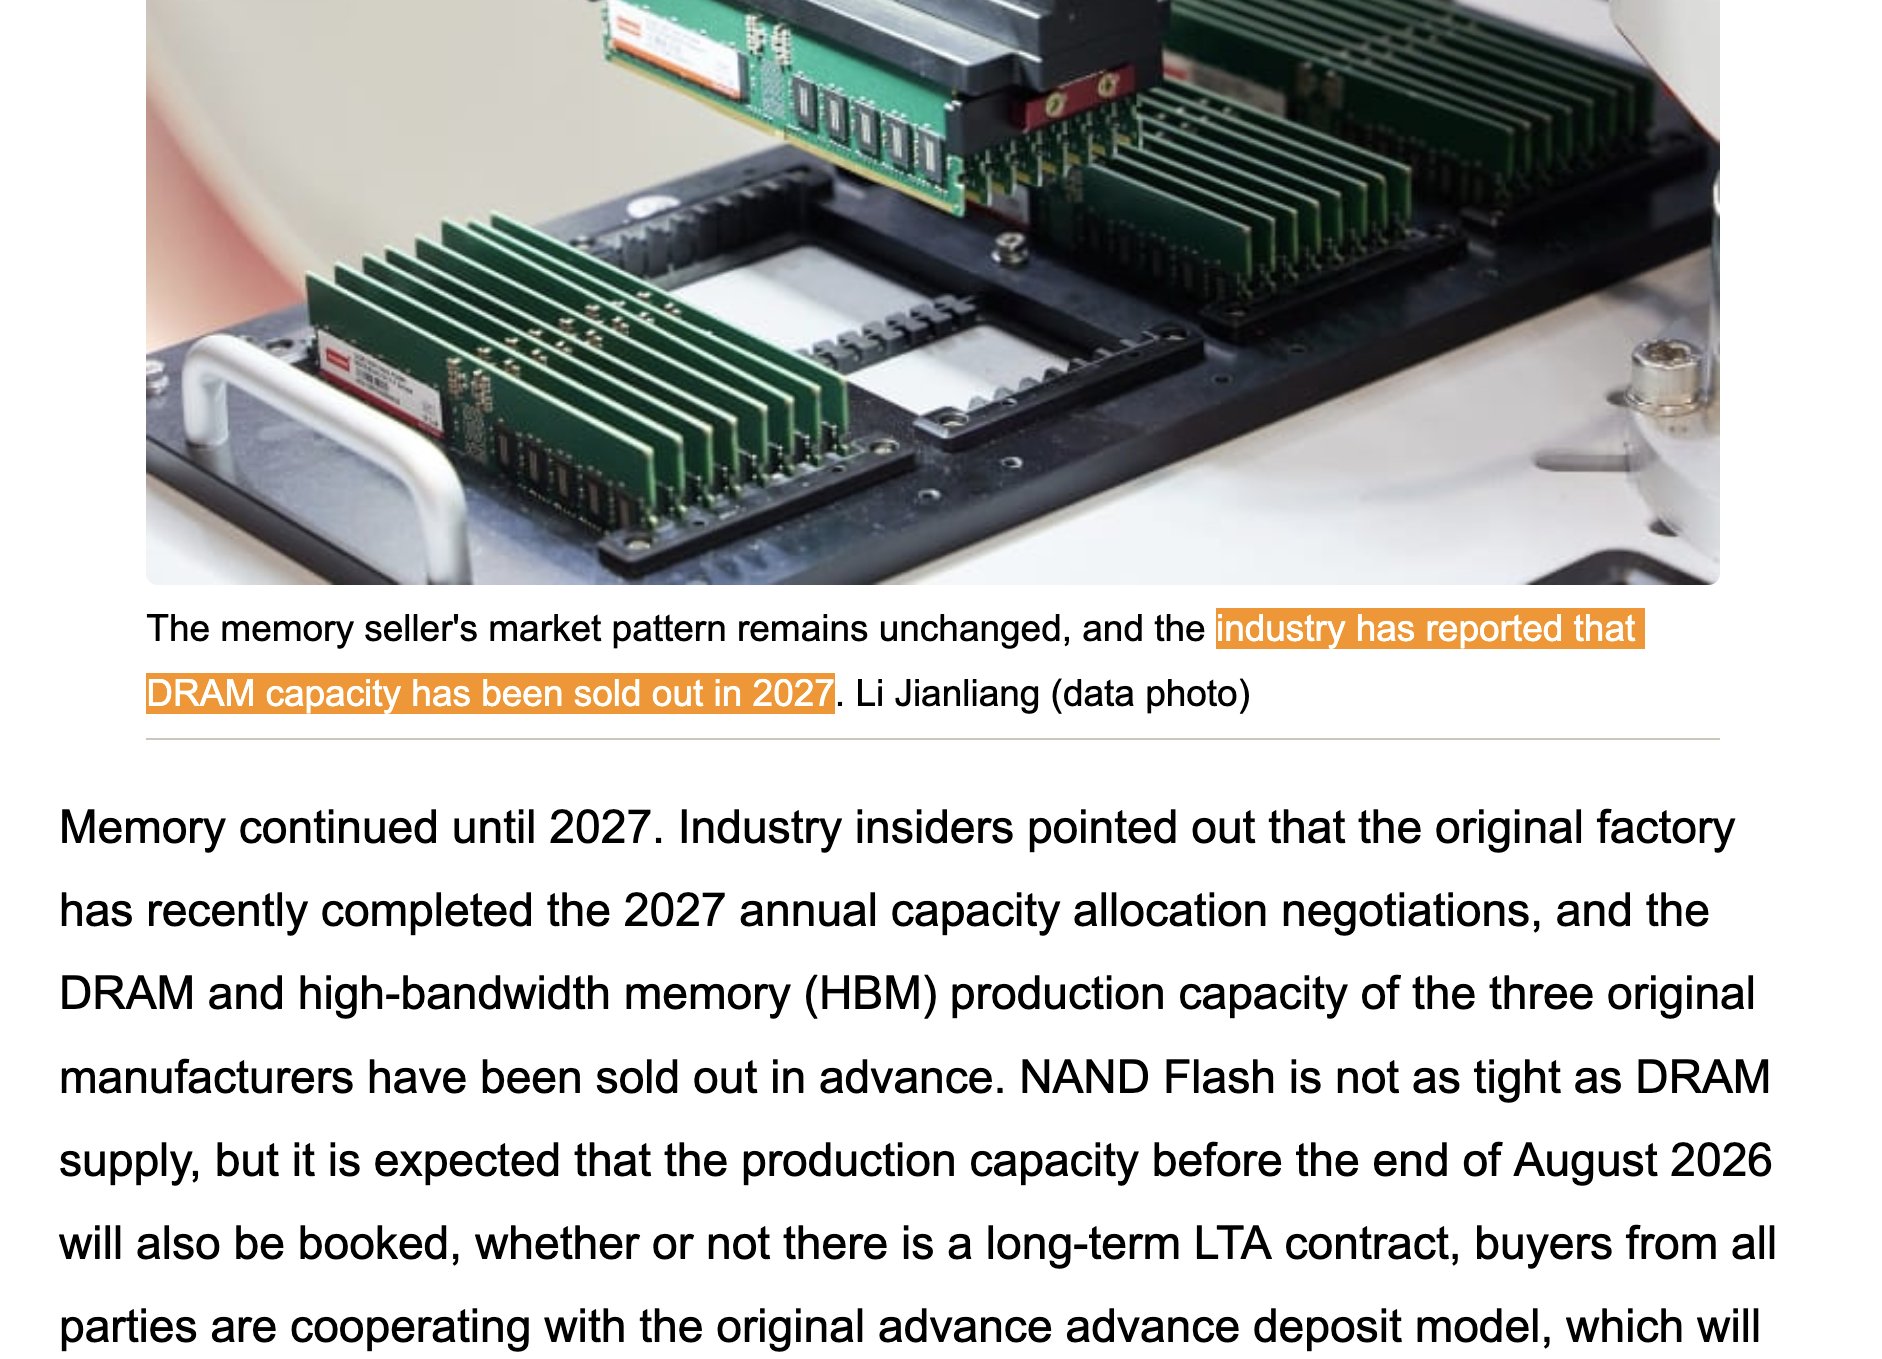
SK Hynix, $MU , and Samsung have sold out of 2027 capacity for DRAM/HBM.
$SNDK, Samsung, Micron current annual NAND capacity has been sold out, with Kioxia and SK Hynix expected to finalize allocations by August 2026.
- Customers are being allocated only 60–70% of the volumes they initially requested
- industry insiders pointed out that 2027 will enter the most severe moment of memory shortage
- Allocation amounts are mostly decided, but final shipment pricing will be determined closer to delivery
Source: Digitimes, citing industry sources.
Hard to see those memory "oversupply" claims in early-mid 2027 when they're all sold out of capacity already.
翻译:
SK Hynix,$MU 和三星已经售出了2027年的DRAM/HBM容量。
$SNDK,三星,美光当前年度的NAND容量已经售罄,预计京瓷和SK Hynix将在2026年8月之前完成分配。
- 客户只被分配了他们最初请求的60-70%的量
- 业内人士指出,2027年将进入内存短缺的最严重时期
- 分配量大多已经确定,但最终的发货价格将在交货前确定
来源:Digitimes,引用业内消息来源。
很难想象2027年初中期会出现内存“过剩”的说法,当时他们已经售出了所有的容量。
Comments
Unlock
原文:
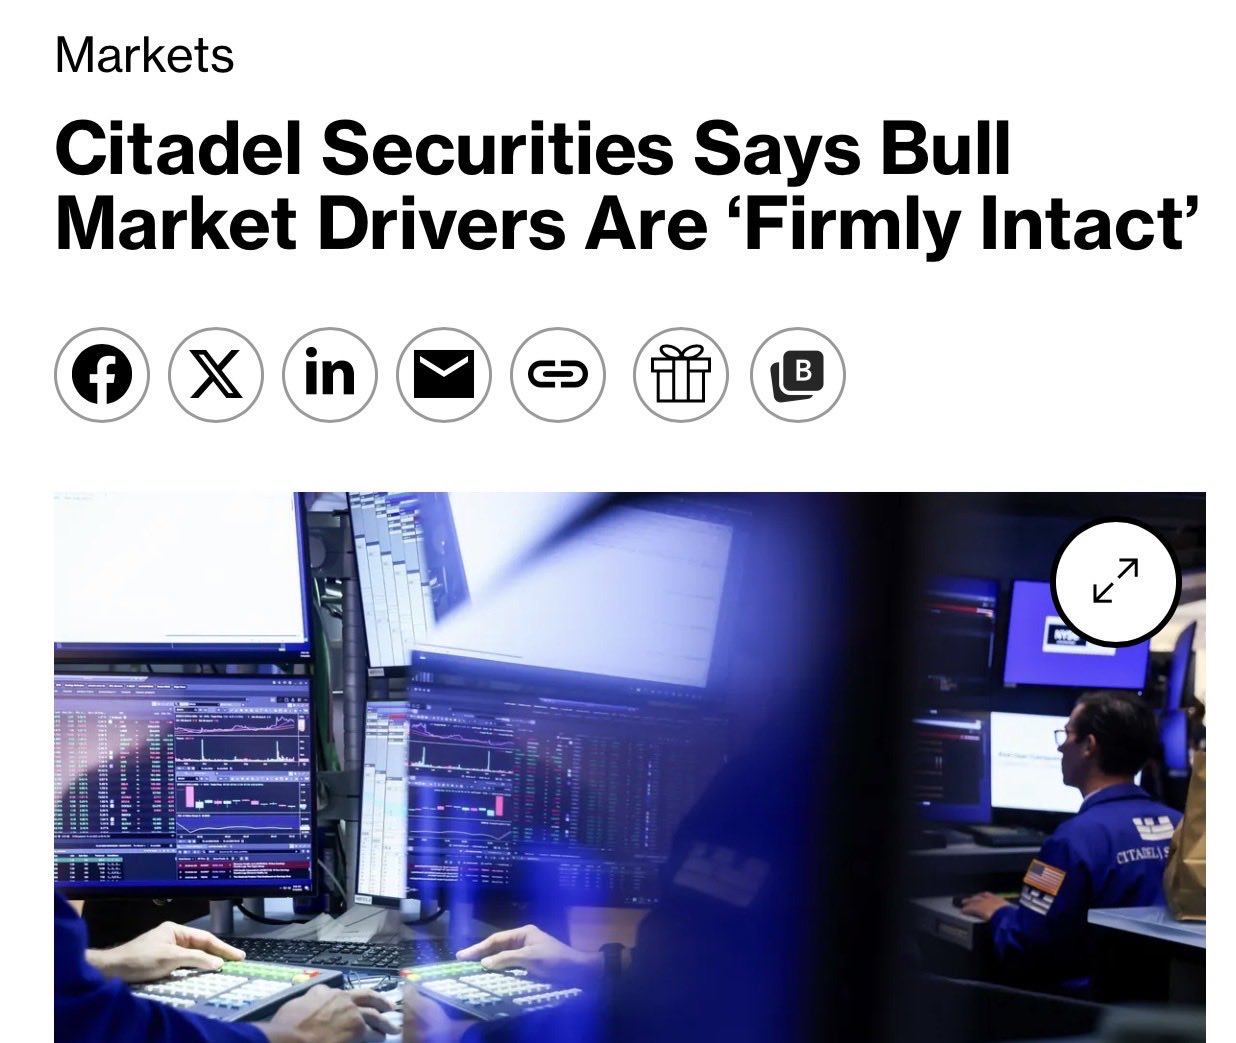
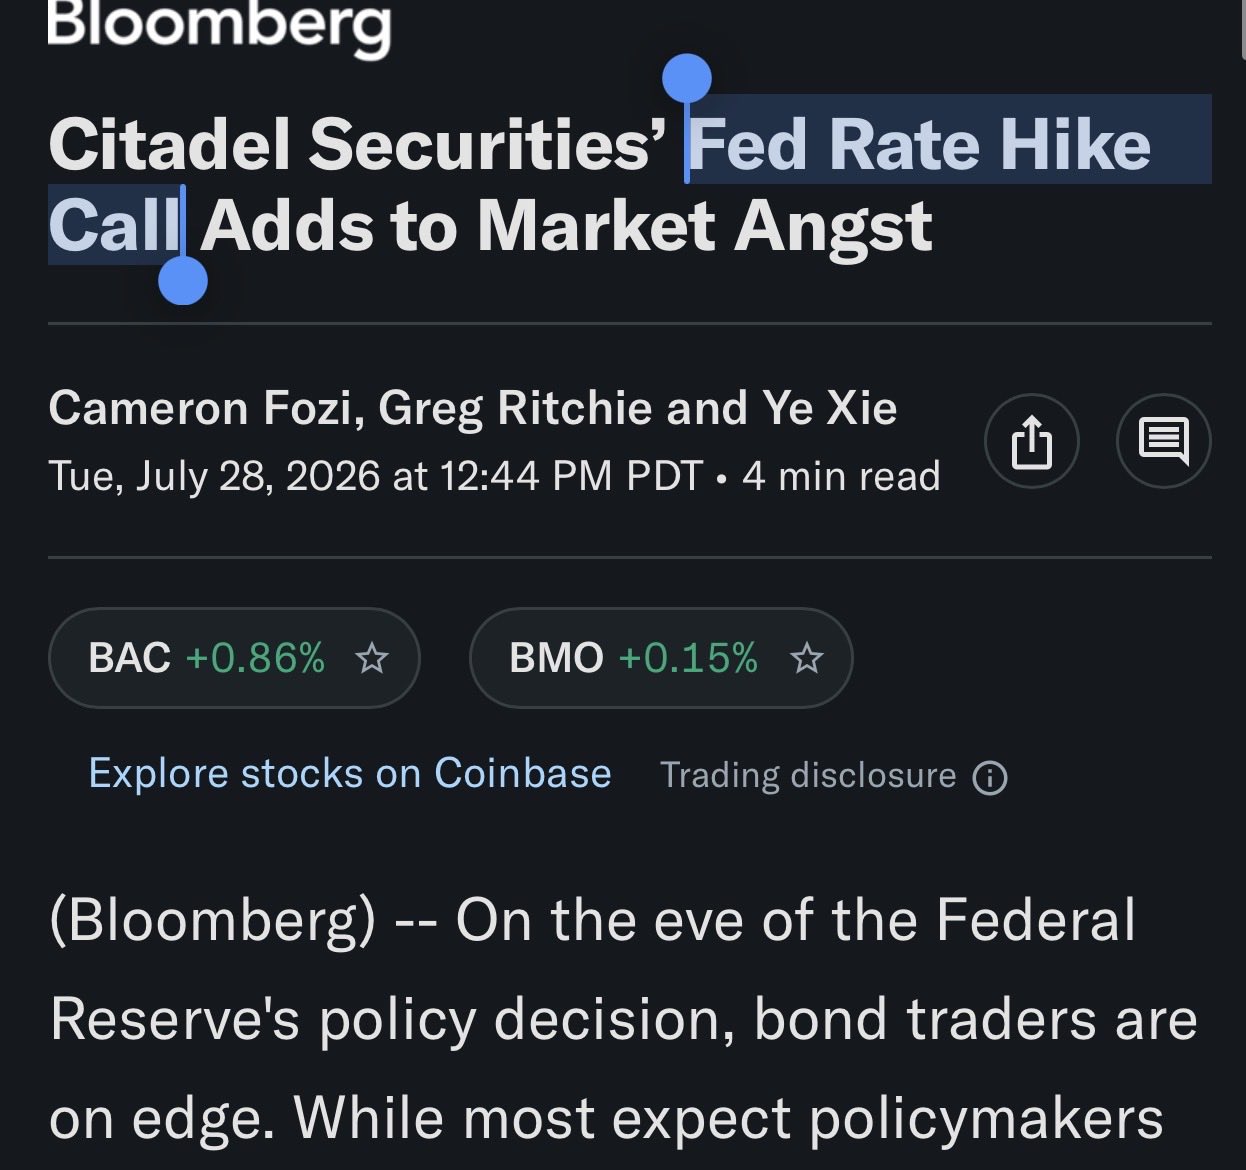
Be Citadel:
> calls for unexpected rate hike few days ago, causing market panic
> reaches out and buys billions of liquidated hedge fund AI assets
> no rate hike
> “Bull market drivers are fully intact” https://t.co/gyy4Nk4SHq
翻译:
是城堡证券:
> 几天前呼吁意外加息,引起市场恐慌
> 主动出击,购买数十亿美元被清算的对冲基金AI资产
> 没有加息
> “牛市驱动因素仍然完好无损” https://t.co/gyy4Nk4SHq
Be Citadel:
> calls for unexpected rate hike few days ago, causing market panic
> reaches out and buys billions of liquidated hedge fund AI assets
> no rate hike
> “Bull market drivers are fully intact” https://t.co/gyy4Nk4SHq
翻译:
是城堡证券:
> 几天前呼吁意外加息,引起市场恐慌
> 主动出击,购买数十亿美元被清算的对冲基金AI资产
> 没有加息
> “牛市驱动因素仍然完好无损” https://t.co/gyy4Nk4SHq
Comments
Unlock
原文:
The bears have gone back into hibernation
翻译:
熊已经回到冬眠状态 🐻💤
The bears have gone back into hibernation
翻译:
熊已经回到冬眠状态 🐻💤
Comments
Unlock
原文:
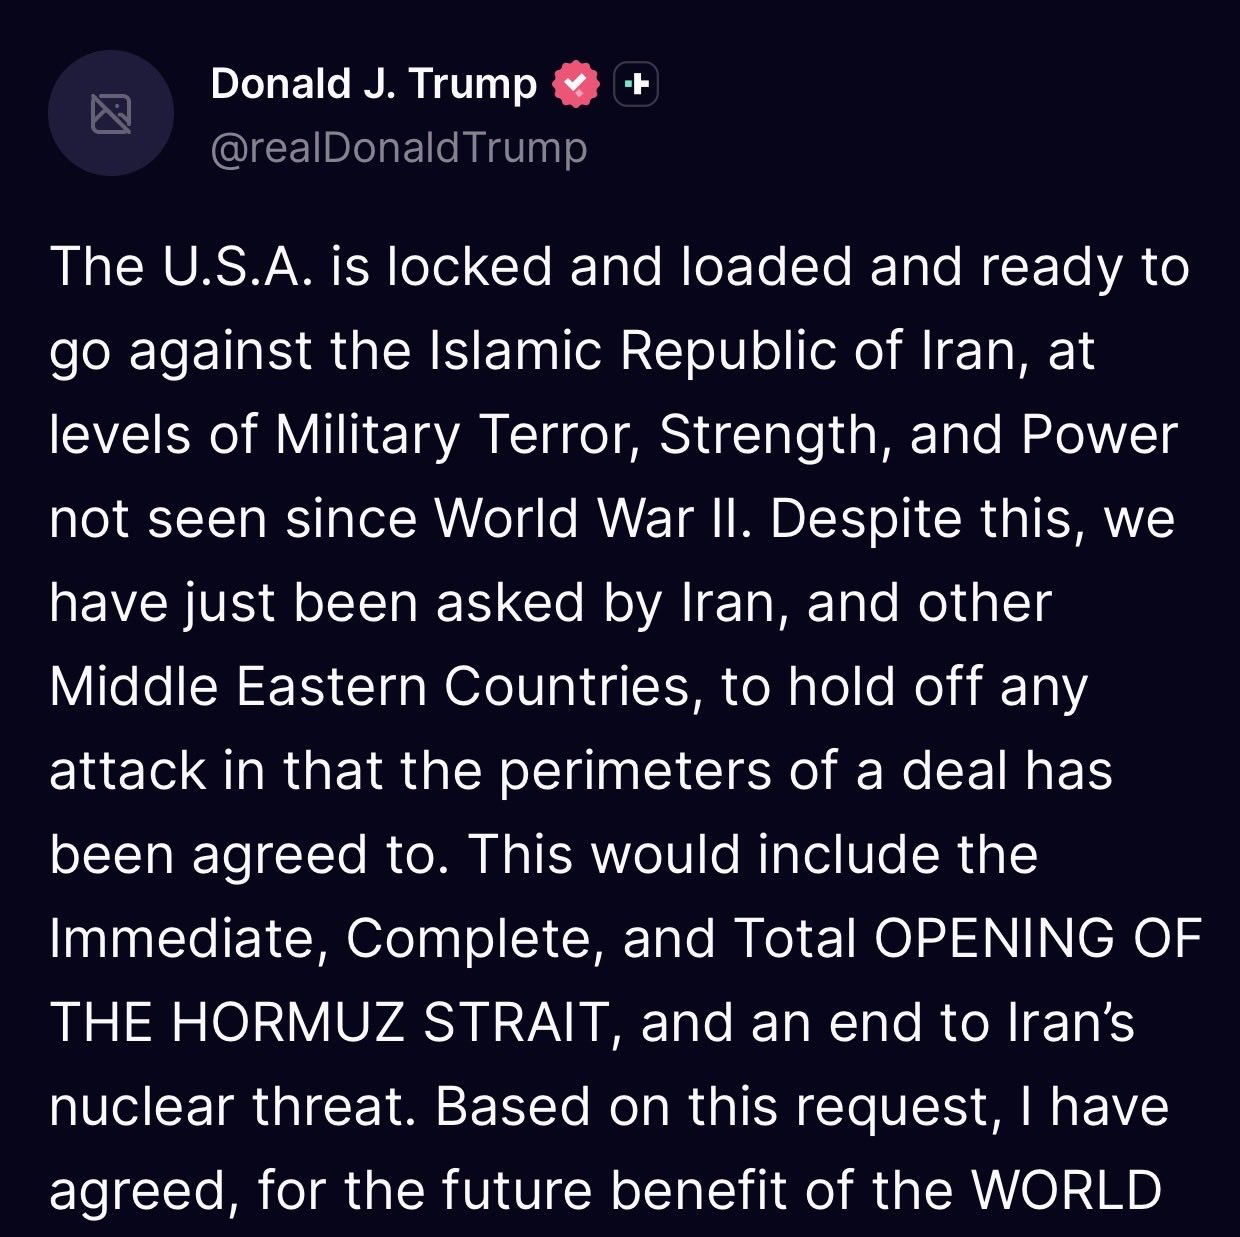
Trump announced that US has cancelled its attack on Iran.
And that they’ve agreed to the perimeters of a deal to open the Strait and end the nuclear program.
Anyone else feel like they’ve aged a few years in the past 6 months? https://t.co/4PK671c548
翻译:
特朗普宣布,美国已取消对伊朗的攻击。
并且他们已同意达成一项协议的框架,以开放海峡并结束核计划。
过去6个月里,有没有人觉得自己老了几岁? https://t.co/4PK671c548
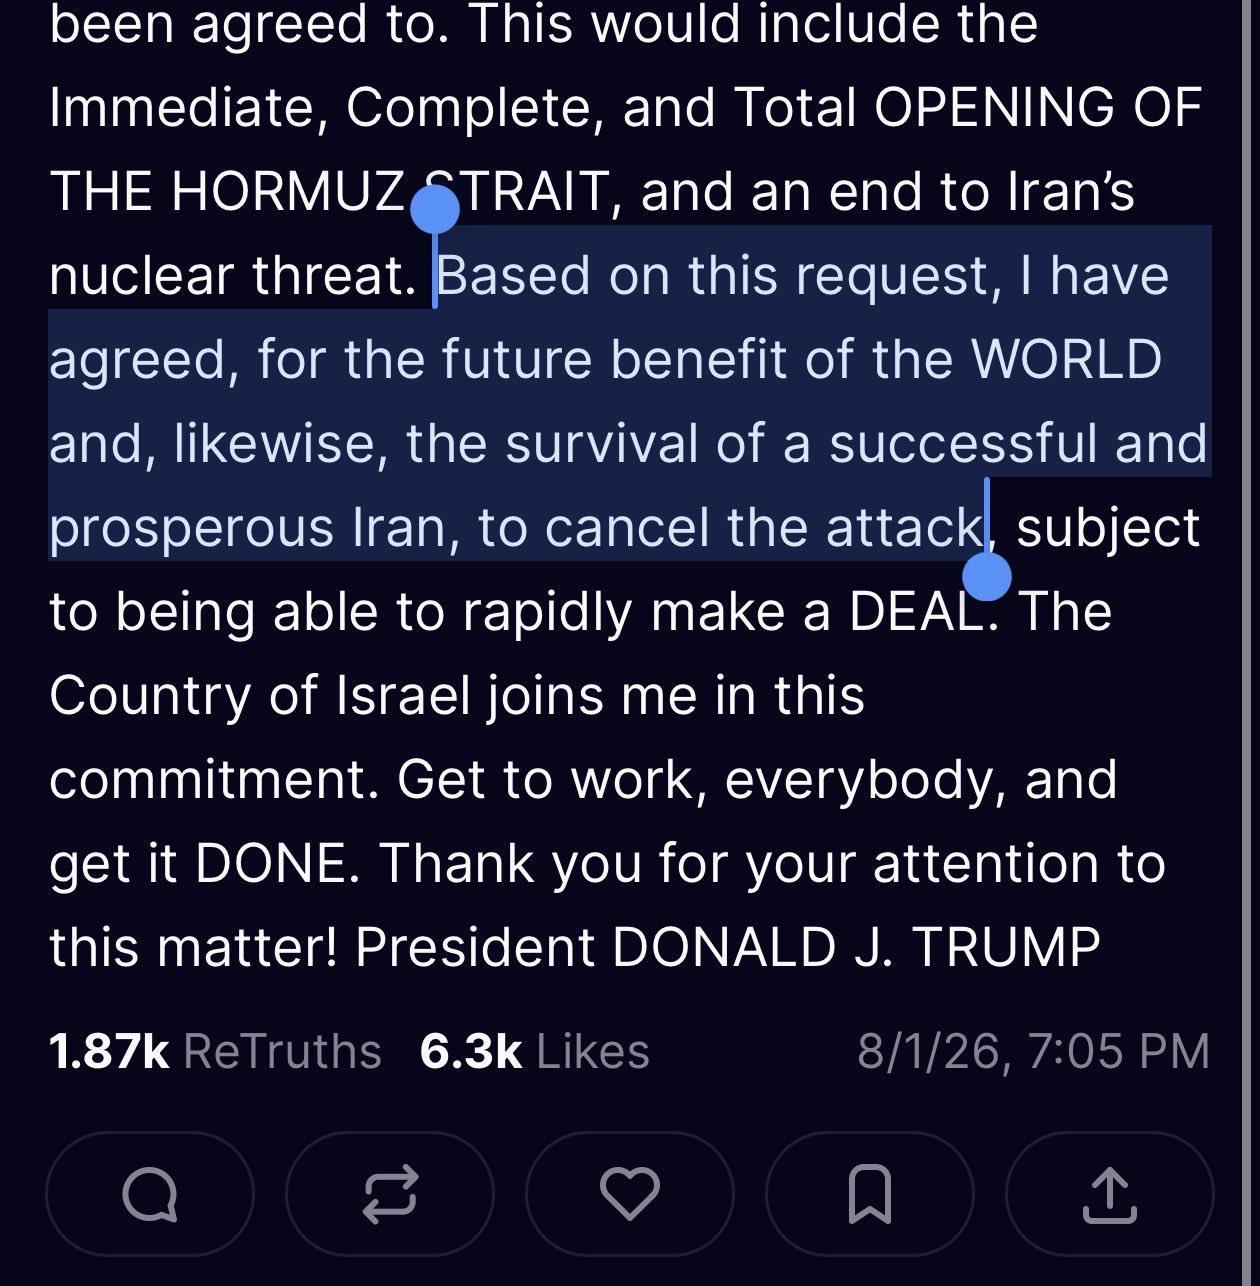
Trump announced that US has cancelled its attack on Iran.
And that they’ve agreed to the perimeters of a deal to open the Strait and end the nuclear program.
Anyone else feel like they’ve aged a few years in the past 6 months? https://t.co/4PK671c548
翻译:
特朗普宣布,美国已取消对伊朗的攻击。
并且他们已同意达成一项协议的框架,以开放海峡并结束核计划。
过去6个月里,有没有人觉得自己老了几岁? https://t.co/4PK671c548
Comments
Unlock
原文:
$LITE CEO Michael Hurlston at the RAISE Summit warned that the supply gap for InP lasers for AI DCs:
Is facing a more severe supply chain crisis than memory.
And with Lumentum's 5 InP fabs, shipments would be more than 30%+ below customer demand.
This is especially visible with EMLs today but is already expanding to CW, especially as CPO ramps.
I've always been a fan of the laser chokepoint + bottleneck from $AAOI, $SIVE, $LITE, and $COHR. And glad this thesis is starting to see validation.
翻译:
$LITE CEO Michael Hurlston 在 RAISE Summit 上警告,AI 数据中心的 InP 激光器供应缺口:
面临的供应链危机比内存更为严重。
而且凭借 Lumentum 的 5 个 InP 代工厂,出货量将比客户需求少 30%+。
这在今天的 EML 中尤其明显,但随着 CPO 的扩张,已经开始扩展到 CW。
我一直是激光瓶颈论的粉丝,$AAOI、$SIVE、$LITE 和 $COHR 都是相关公司。很高兴看到这个观点开始得到验证。
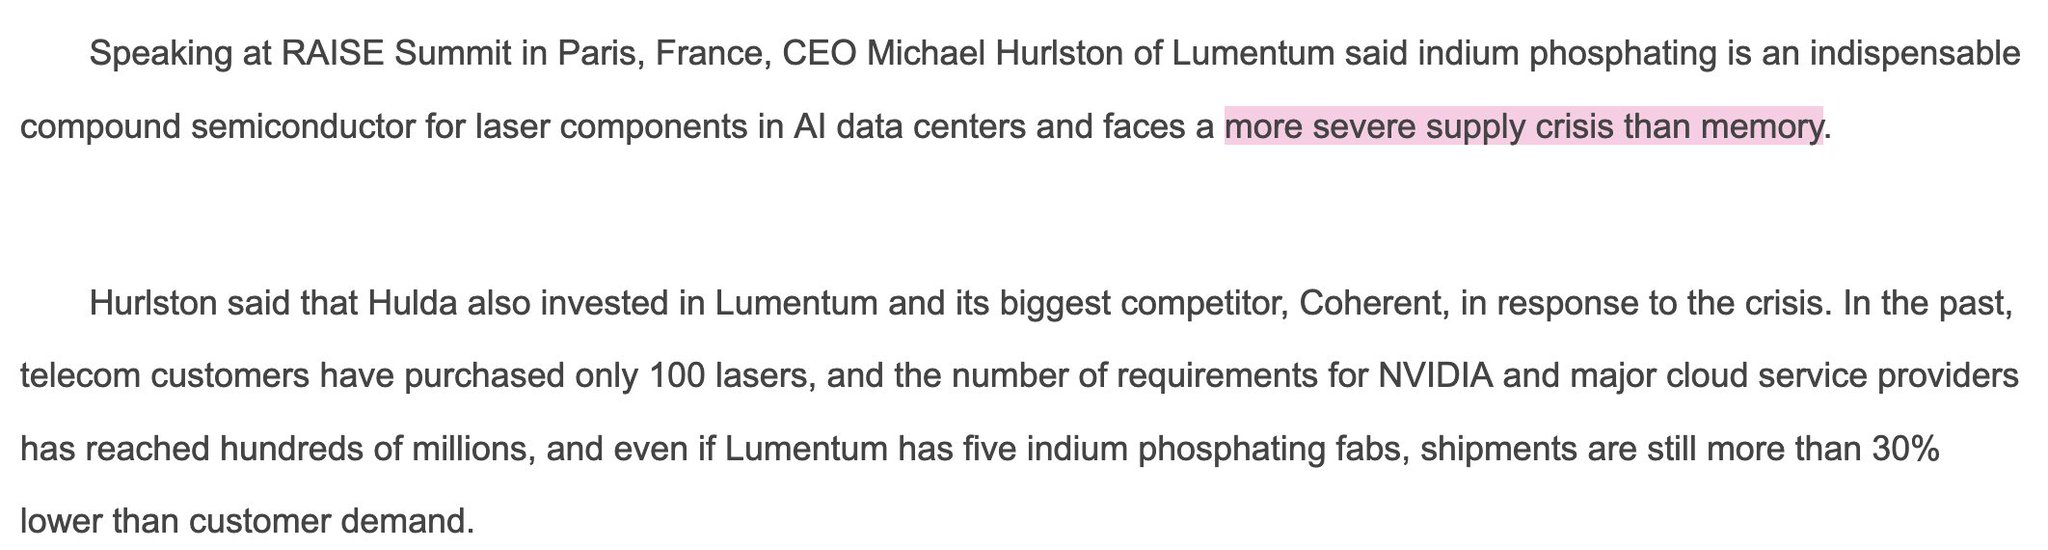
$LITE CEO Michael Hurlston at the RAISE Summit warned that the supply gap for InP lasers for AI DCs:
Is facing a more severe supply chain crisis than memory.
And with Lumentum's 5 InP fabs, shipments would be more than 30%+ below customer demand.
This is especially visible with EMLs today but is already expanding to CW, especially as CPO ramps.
I've always been a fan of the laser chokepoint + bottleneck from $AAOI, $SIVE, $LITE, and $COHR. And glad this thesis is starting to see validation.
翻译:
$LITE CEO Michael Hurlston 在 RAISE Summit 上警告,AI 数据中心的 InP 激光器供应缺口:
面临的供应链危机比内存更为严重。
而且凭借 Lumentum 的 5 个 InP 代工厂,出货量将比客户需求少 30%+。
这在今天的 EML 中尤其明显,但随着 CPO 的扩张,已经开始扩展到 CW。
我一直是激光瓶颈论的粉丝,$AAOI、$SIVE、$LITE 和 $COHR 都是相关公司。很高兴看到这个观点开始得到验证。
Comments
Unlock
原文:
$LITE CEO Michael Hurlston at the RAISE Summit warned that the supply gap for InP lasers for AI DCs:
Is facing a more severe supply chain crisis than memory.
And with Lumentum's 5 InP fabs, shipments would be more than 30%+ below customer demand.
This is especially visible with EMLs today but is already expand to CW, especially as CPO ramps.
I've always been a fan of the laser chokepoint + bottleneck from $AAOI, $SIVE, $LITE, and $COHR. And glad this thesis is starting to see validation.
This is especially visible with EMLs today but is already extending to CW, especially as CPO ramps.
I tend to be a fan of laser players with independent capacity like $SIVE, $AAOI, $LITE, and $COHR.
翻译:
$LITE CEO Michael Hurlston 在 RAISE Summit 上警告称,AI 数据中心的 InP 激光器供应面临着比内存更严重的供应链危机。
即使拥有 5 个 InP 代工厂,Lumentum 的出货量仍将比客户需求少 30%+。
这种情况在今天的 EML 中尤其明显,但已经扩展到 CW,尤其是随着 CPO 的扩张。
我一直是激光瓶颈论的粉丝,$AAOI、$SIVE、$LITE 和 $COHR 都是相关公司,我很高兴看到这个观点开始得到验证。
这种情况在今天的 EML 中尤其明显,但已经扩展到 CW,尤其是随着 CPO 的扩张。
我倾向于支持拥有独立生产能力的激光公司,如 $SIVE、$AAOI、$LITE 和 $COHR。
Comments
Unlock
原文:
The media framing and X reactions around Leopold are egregious.
Framing his successful multi-year thesis from $SNDK to $BE as a "collapse" or "failure".
After July's surprising crash, then personally attacking him on top is just pathetic to witness.
It's almost like everyone is cheering for the downfall of others.
Yes, July's crash exposed problems with SA’s leverage, liquidity management, and hedging.
But his current YTD performance remains +80%, ranking among the best performing hedge funds. And he still has public equities after all this (just removed leverage).
I think he's doing something unique while being successful at it. And this draws the envy of others.
翻译:
媒体对利奥波德的报道和X上的反应令人震惊。
将他从$SNDK到$BE的成功多年投资策略说成是“崩溃”或“失败”,这是不公平的。
7月份令人惊讶的崩盘之后,媒体还对他进行人身攻击,看到这一幕真是令人遗憾。
这几乎就像每个人都在为他人的失败而欢呼。
是的,7月份的崩盘暴露了SA的杠杆、流动性管理和对冲问题。
但是他目前的年度表现仍然是+80%,在最佳表现的对冲基金中排名靠前。并且在经历了这一切之后,他仍然拥有公开的股票(只是去掉了杠杆)。
我认为他正在做一些独特的事情,同时也取得了成功。这引起了他人的嫉妒。
Comments
Unlock
原文:
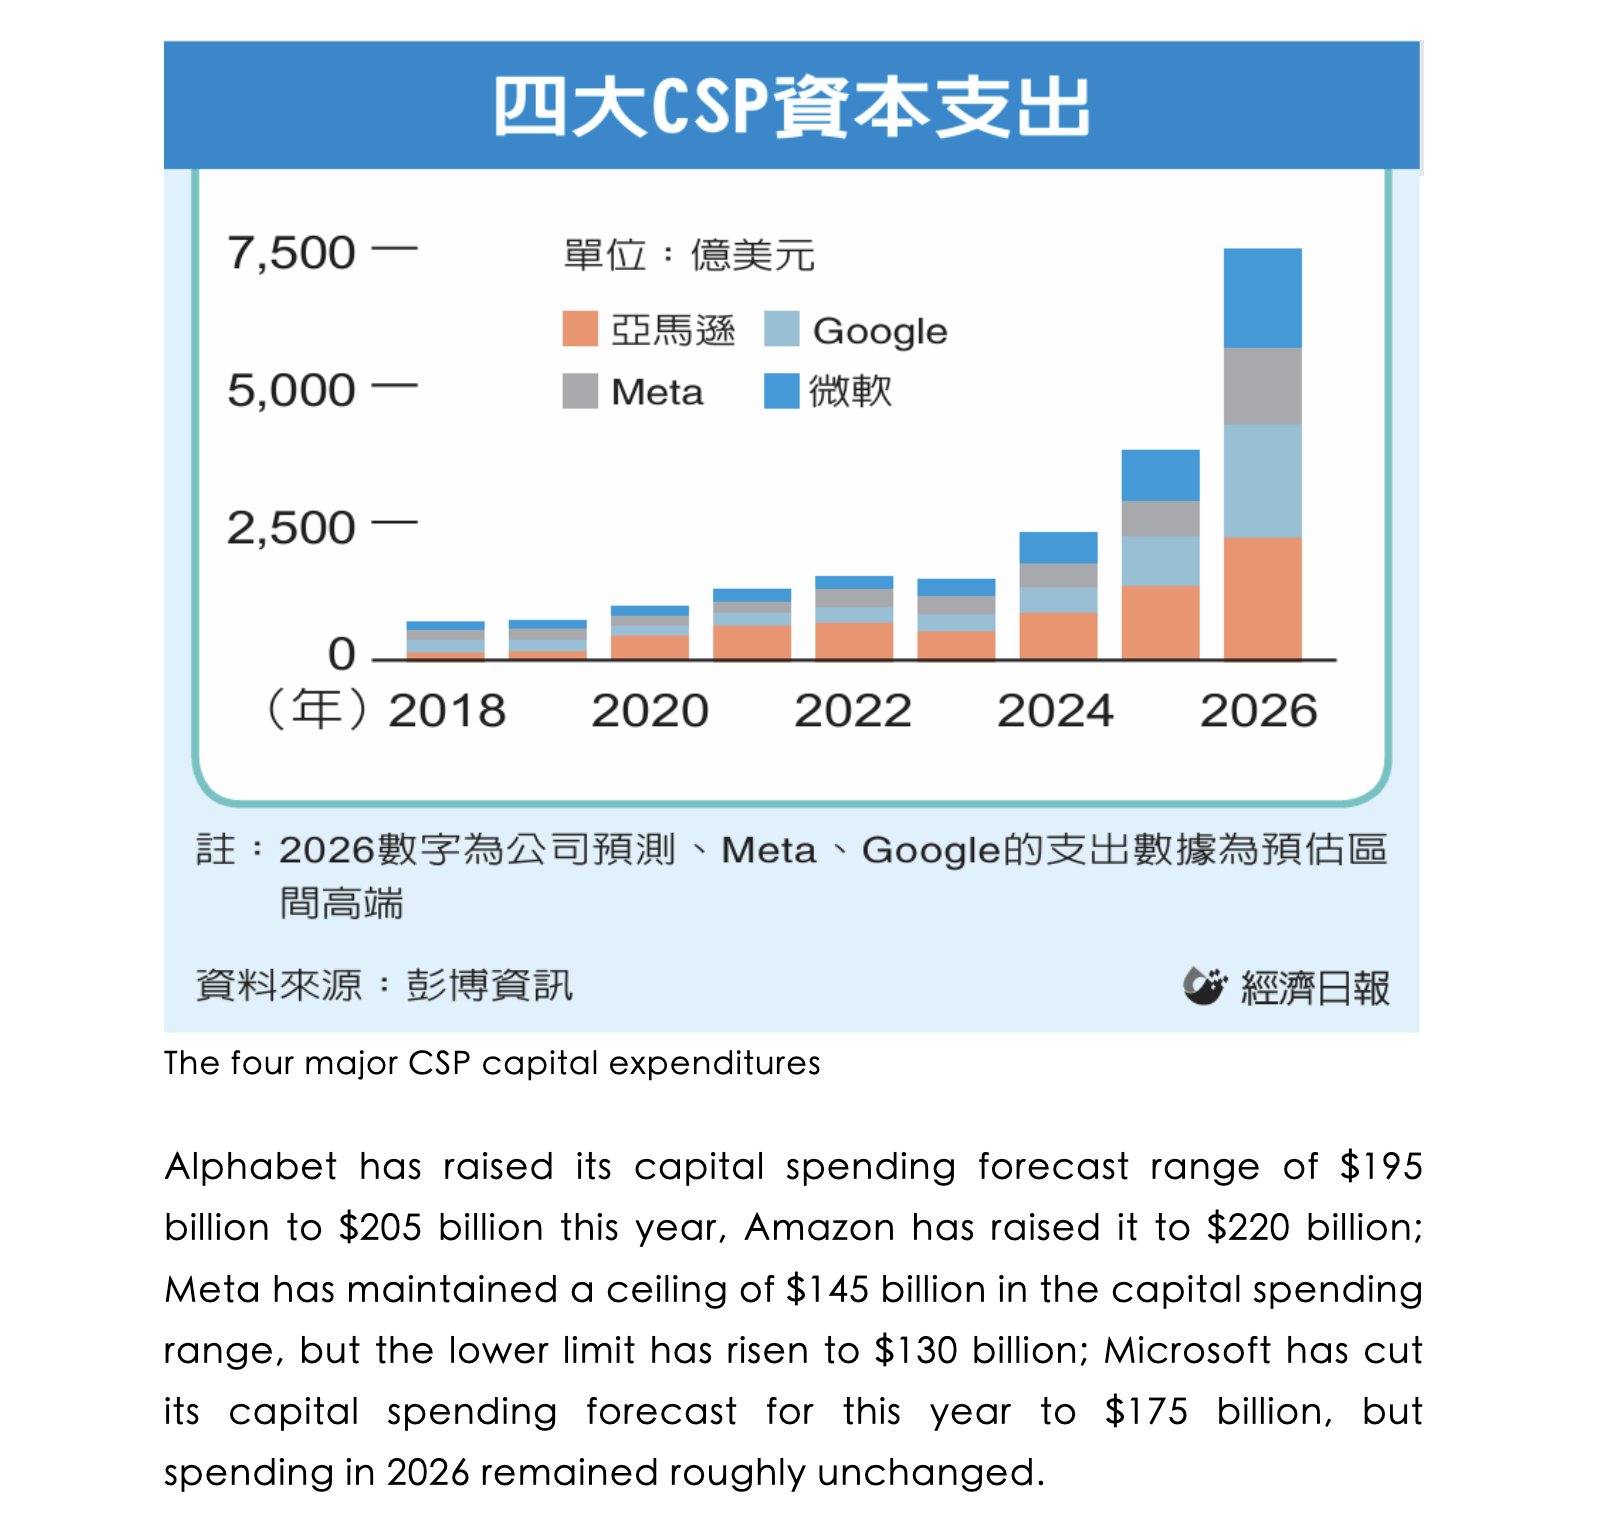
As a earnings recap: $AMZN, $META, $GOOGL, and $MSFT guided a 2026 combined capex forecast to ~$720-$745 Billion.
Up from $695-$725B Billion previously.
Amazon: $220B
Google: $195B-$205B
Meta: $130B-$145B
Microsoft: $175B
We've already seen significant deleveraging and retail/institutional margin liquidations (maybe it continues for more time, who knows).
But medium-long term, I'm not quite sure how anyone can be bearish the upstream semis or neoclouds.
Given each hyperscaler has flagged either compute shortages, rising cloud demand + pricing power, or increased spending for chips/networking.
My "bottleneck" thesis with many of these upstream semi supply chains is that when trillions in capital flows into things from InP substrates or memory (which were both treated as cheap commodities) or even energy.
Lot of these current AI names that were treated as useless before in telecom cycles or even toilet sellers.
Gets rerated when their inflection period hits and capex flows into their balance sheets.
As seen with $NVDA GPUs past few years, memory this year, CPUs/MLCCs next few years, CPO in 2027, Glass Substrates in 2027, 800V in 2027, and so on.
翻译:
作为收益回顾:$AMZN、$META、$GOOGL 和 $MSFT 指出 2026 年综合资本支出预测为约 720-7450 亿美元。
较之前的 695-7250 亿美元有所上升。
亚马逊:2200 亿美元
谷歌:1950-2050 亿美元
Meta:1300-1450 亿美元
微软:1750 亿美元
我们已经看到显著的去杠杆和零售/机构保证金清算(可能会继续一段时间,谁知道)。
但中长期来看,我不太确定为什么有人会看空上游半导体或新云计算。
鉴于每个超大规模云计算公司都提到了计算资源短缺、云计算需求增长+定价权或芯片/网络支出增加。
我关于许多上游半导体供应链的“瓶颈”论点是,当数万亿资本流入诸如磷化物基底板或内存(这些曾经被视为廉价商品)甚至能源等领域时。
许多当前的 AI 公司曾经在电信周期或甚至马桶销售者中被视为无用的东西。
当它们的拐点期到来,资本支出流入它们的资产负债表时,就会被重新评估。
如同过去几年中 $NVDA 的 GPU、今年的内存、未来几年的 CPU/MLCC、2027 年的 CPO、2027 年的玻璃基板、2027 年的 800V 等所见。
As a earnings recap: $AMZN, $META, $GOOGL, and $MSFT guided a 2026 combined capex forecast to ~$720-$745 Billion.
Up from $695-$725B Billion previously.
Amazon: $220B
Google: $195B-$205B
Meta: $130B-$145B
Microsoft: $175B
We've already seen significant deleveraging and retail/institutional margin liquidations (maybe it continues for more time, who knows).
But medium-long term, I'm not quite sure how anyone can be bearish the upstream semis or neoclouds.
Given each hyperscaler has flagged either compute shortages, rising cloud demand + pricing power, or increased spending for chips/networking.
My "bottleneck" thesis with many of these upstream semi supply chains is that when trillions in capital flows into things from InP substrates or memory (which were both treated as cheap commodities) or even energy.
Lot of these current AI names that were treated as useless before in telecom cycles or even toilet sellers.
Gets rerated when their inflection period hits and capex flows into their balance sheets.
As seen with $NVDA GPUs past few years, memory this year, CPUs/MLCCs next few years, CPO in 2027, Glass Substrates in 2027, 800V in 2027, and so on.
翻译:
作为收益回顾:$AMZN、$META、$GOOGL 和 $MSFT 指出 2026 年综合资本支出预测为约 720-7450 亿美元。
较之前的 695-7250 亿美元有所上升。
亚马逊:2200 亿美元
谷歌:1950-2050 亿美元
Meta:1300-1450 亿美元
微软:1750 亿美元
我们已经看到显著的去杠杆和零售/机构保证金清算(可能会继续一段时间,谁知道)。
但中长期来看,我不太确定为什么有人会看空上游半导体或新云计算。
鉴于每个超大规模云计算公司都提到了计算资源短缺、云计算需求增长+定价权或芯片/网络支出增加。
我关于许多上游半导体供应链的“瓶颈”论点是,当数万亿资本流入诸如磷化物基底板或内存(这些曾经被视为廉价商品)甚至能源等领域时。
许多当前的 AI 公司曾经在电信周期或甚至马桶销售者中被视为无用的东西。
当它们的拐点期到来,资本支出流入它们的资产负债表时,就会被重新评估。
如同过去几年中 $NVDA 的 GPU、今年的内存、未来几年的 CPU/MLCC、2027 年的 CPO、2027 年的玻璃基板、2027 年的 800V 等所见。
Comments
Unlock
原文:
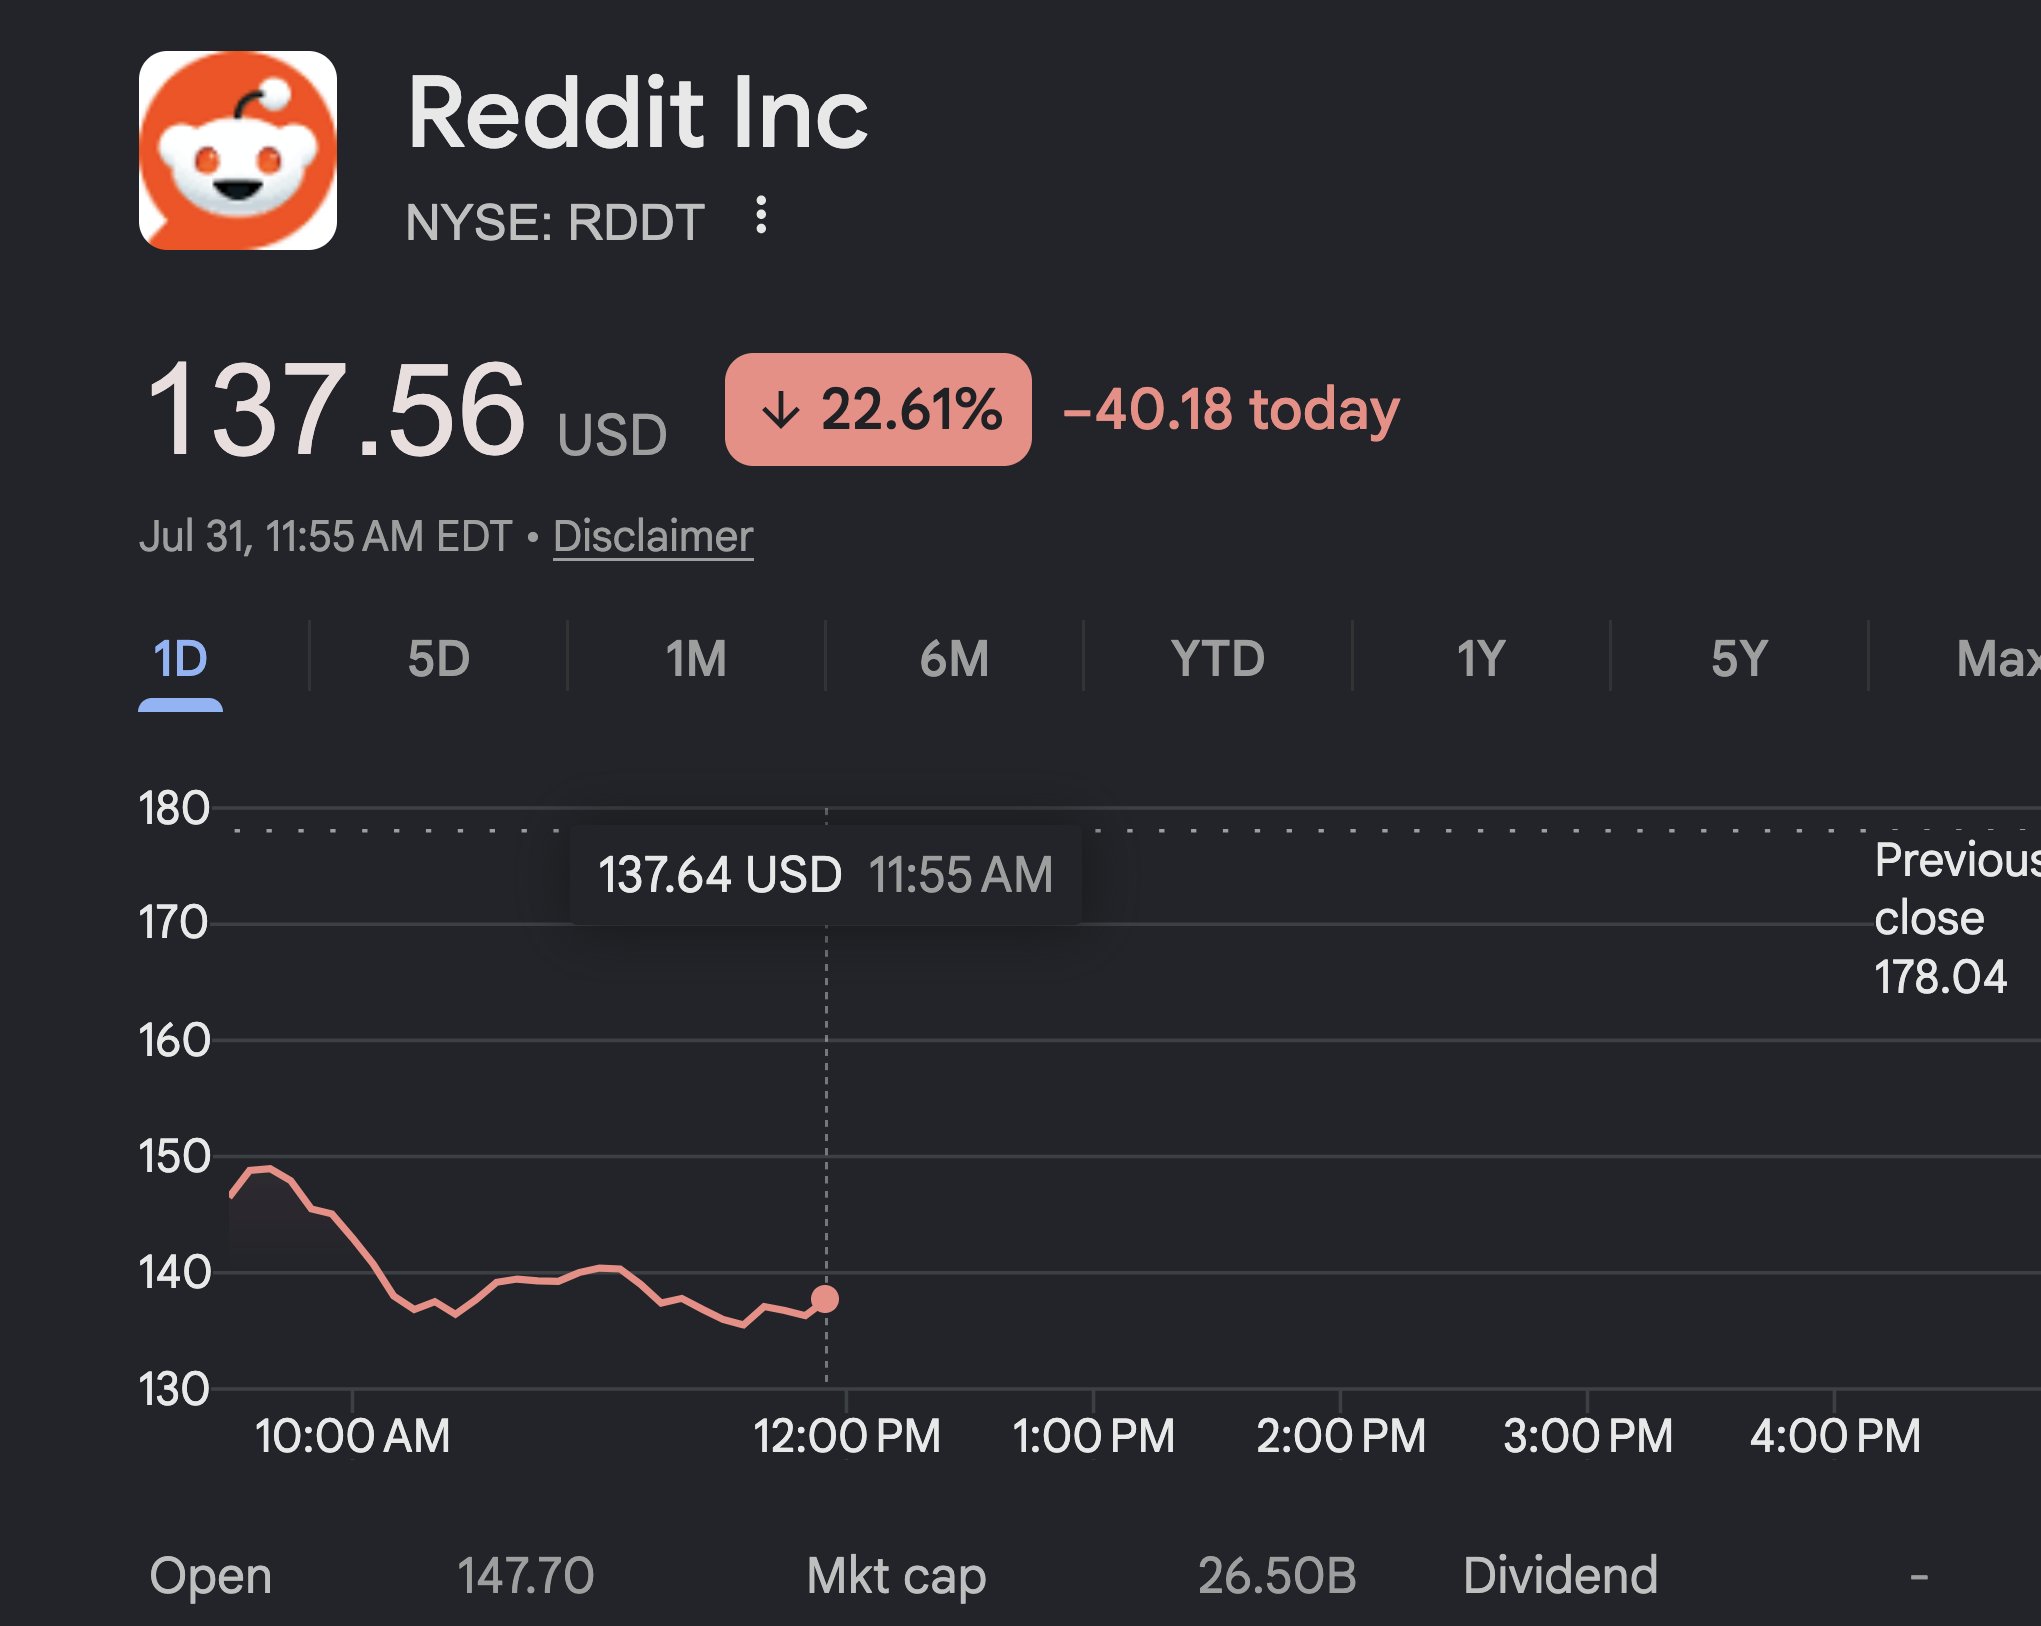
$RDDT ER in a nutshell:
Revenue: $804.9M vs. $730.4M (expected).
EPS: $1.25 vs. ~$0.95.
Net income: $252.8M vs. $196.5M
Q3 guidance:
Revenue: $860–870M vs. 829.1M
Adjusted EBITDA: $385-395M vs. $369M
Blowout financials, market always like to explain the drop 22.6% off some new BS narrative.
Last quarter: "AI will disrupt Reddit causing revenue loss!"
This quarter: "See, DAU fell .6%!" (proceeds to ignore any revenue/profitability growth)
翻译:
$RDDT 财报简要概述:
收入:804.9M 美元,预期为 730.4M 美元。
每股收益:1.25 美元,预期约为 0.95 美元。
净收入:252.8M 美元,预期为 196.5M 美元
第三季度预测:
收入:860–870M 美元,预期为 829.1M 美元
调整后息税折旧摊销前利润:385-395M 美元,预期为 369M 美元
财报非常出色,但市场总是喜欢用一些新编的理由来解释 22.6% 的下跌。
上个季度:“AI 会破坏 Reddit,从而导致收入损失!”
这个季度:“看,日活用户数量下降了 0.6%!”(然后忽略任何收入和盈利能力的增长)
$RDDT ER in a nutshell:
Revenue: $804.9M vs. $730.4M (expected).
EPS: $1.25 vs. ~$0.95.
Net income: $252.8M vs. $196.5M
Q3 guidance:
Revenue: $860–870M vs. 829.1M
Adjusted EBITDA: $385-395M vs. $369M
Blowout financials, market always like to explain the drop 22.6% off some new BS narrative.
Last quarter: "AI will disrupt Reddit causing revenue loss!"
This quarter: "See, DAU fell .6%!" (proceeds to ignore any revenue/profitability growth)
翻译:
$RDDT 财报简要概述:
收入:804.9M 美元,预期为 730.4M 美元。
每股收益:1.25 美元,预期约为 0.95 美元。
净收入:252.8M 美元,预期为 196.5M 美元
第三季度预测:
收入:860–870M 美元,预期为 829.1M 美元
调整后息税折旧摊销前利润:385-395M 美元,预期为 369M 美元
财报非常出色,但市场总是喜欢用一些新编的理由来解释 22.6% 的下跌。
上个季度:“AI 会破坏 Reddit,从而导致收入损失!”
这个季度:“看,日活用户数量下降了 0.6%!”(然后忽略任何收入和盈利能力的增长)
Comments
Unlock
原文:
Just a TLDR of this week:
Media: Hyperscalers overbuilt and are selling excess compute.
-> $GOOGL, $MSFT, $META, and $AMZN: Demand for compute far exceeds capacity. Capex go brrr.
Institutions: Emergency rate hike or 3x rate hikes, it's all over.
-> Kevin Warsh: No rate Hike.
Retail/Media: AI is crashing because it's a bubble.
-> Citadel looking to buy AI leveraged hedge funds positions: 👀
Jim Cramer: Sell all your leveraged DC stocks.
-> Koreans: SK Hynix +30%, Samsung +26.81%
翻译:
本周简要概述:
媒体:超大规模云计算公司过度扩张,现在正在出售多余的计算资源。
-> $GOOGL、$MSFT、$META 和 $AMZN:计算需求远远超过容量。资本支出激增。
机构:紧急加息或三次加息,结果都一样。
-> 凯文·沃什:不会加息。
零售/媒体:人工智能正在崩溃,因为它是一个泡沫。
-> 城堡投资集团正在寻求购买人工智能杠杆对冲基金头寸:👀
吉姆·克莱默:卖掉所有杠杆式数据中心股票。
-> 韩国人:SK海力士 +30%,三星 +26.81%
Comments
Unlock
原文:
Now that I think of it more, $POET optical interposer piece is actually a little more material than I thought with $SIVE.
Originally the wording was "readiness" for EOY 2026.
But $POET upgraded that wording, by stating "production" with Sivers lasers projected EOY 2026.
So a volume orders from across $JBL to $POET, should hit in H1 2027. Which makes a bit of sense, since Sivers did raise an institutional oversubscribed round for future mass production.
On a side note, can't believe it's already August and 5 months left until 2027... Which was my inflection window for glass substrates, CPO, 800v, and new architectures to ramp.
翻译:
现在我想得更多,$POET 光学互连器件实际上比我想象中与 $SIVE 有更多的关联。
最初的表述是“准备就绪”以应对 2026 年底。
但 $POET 升级了这个表述,宣布将在 2026 年底与 Sivers 激光器实现“生产”。
因此,来自 $JBL 到 $POET的大批量订单应该会在 2027 年上半年到来。这有一定的道理,因为 Sivers 曾为未来大规模生产而进行了超额认购的机构融资。
顺便说一下,已经八月了,距离 2027 年只有 5 个月了……这是我预测玻璃基板、CPO、800V 和新架构将实现大规模生产的转折窗口。 🙃
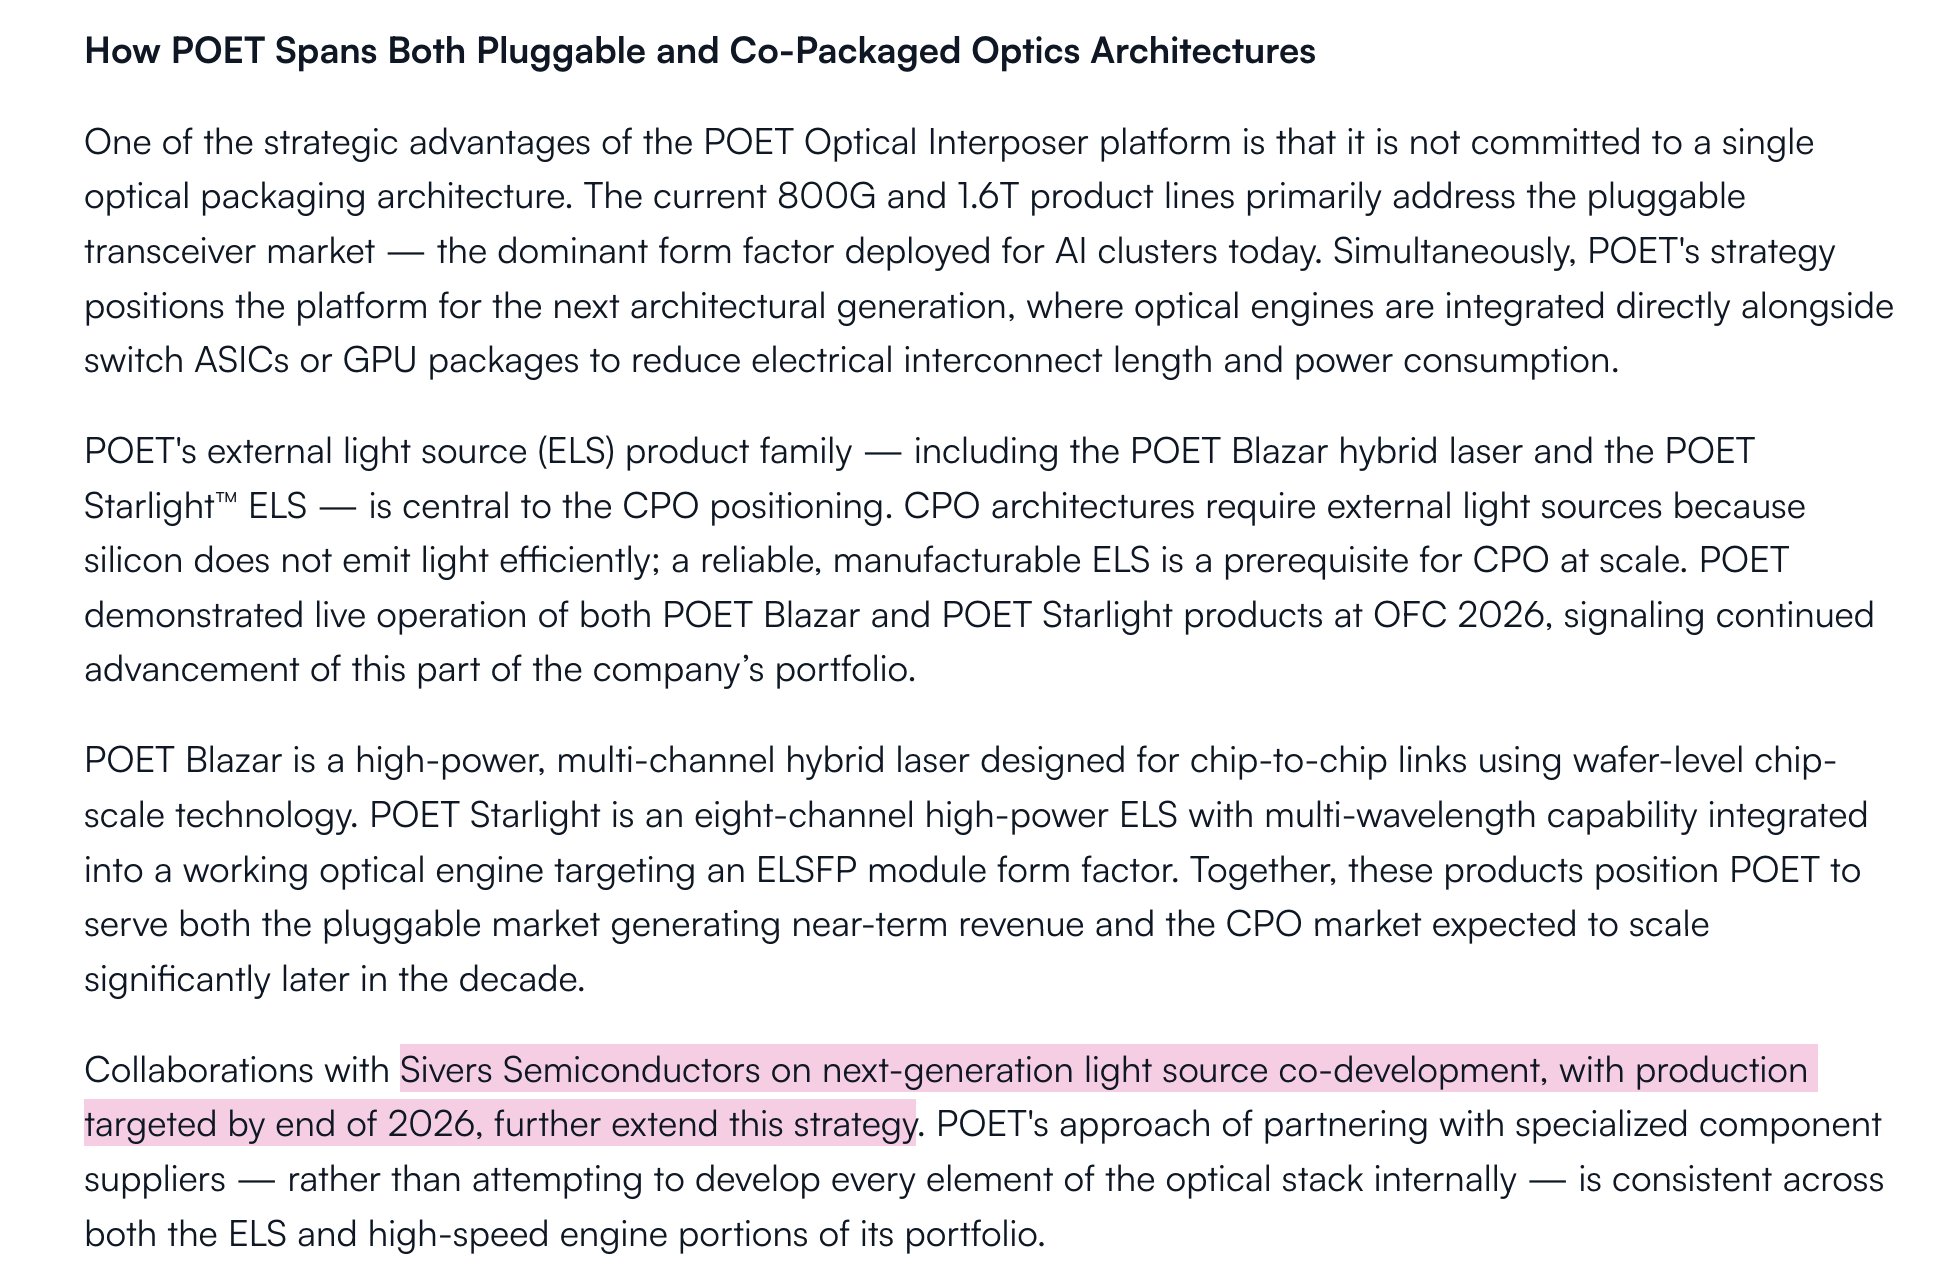
Now that I think of it more, $POET optical interposer piece is actually a little more material than I thought with $SIVE.
Originally the wording was "readiness" for EOY 2026.
But $POET upgraded that wording, by stating "production" with Sivers lasers projected EOY 2026.
So a volume orders from across $JBL to $POET, should hit in H1 2027. Which makes a bit of sense, since Sivers did raise an institutional oversubscribed round for future mass production.
On a side note, can't believe it's already August and 5 months left until 2027... Which was my inflection window for glass substrates, CPO, 800v, and new architectures to ramp.
翻译:
现在我想得更多,$POET 光学互连器件实际上比我想象中与 $SIVE 有更多的关联。
最初的表述是“准备就绪”以应对 2026 年底。
但 $POET 升级了这个表述,宣布将在 2026 年底与 Sivers 激光器实现“生产”。
因此,来自 $JBL 到 $POET的大批量订单应该会在 2027 年上半年到来。这有一定的道理,因为 Sivers 曾为未来大规模生产而进行了超额认购的机构融资。
顺便说一下,已经八月了,距离 2027 年只有 5 个月了……这是我预测玻璃基板、CPO、800V 和新架构将实现大规模生产的转折窗口。 🙃
Comments
Unlock
原文:
For $XFAB ER transcript:
Just to recap, my idea on $XFAB foundry growth opportunities stemmed from SiC for 800v and photonixfab/MTP for CPO applicability.
- $XFAB: "We are making progress in co-packaged optics".
- "The transition to 800v... is expected to support demand for both SiC and GaN... for XFAB"
So those analysts/people that were confidently bearposting about $XFAB that they had "0 exposure to 800V, photonics, CPO" just turned out plainly wrong.
At the time I shared my idea, industry materials showed ASE and others cited photonixfab + XFAB as an upcoming CPO player in EU. And filings showed they had exposure names like $NVTS / $POWI in general.
So glad $XFAB went out to explicitly clear things up to state they were developing in CPO/800v.
Okay back to the ER:
- "We continue to expect photonics volume production to start in 2028". Company currently has three silicon photonics projects in development with key partners.
I thought it would ramp sometime in H2 2027, but was probably early by a few months.
- Several new data center design wins, eg. 3 new SiC design wins (consistent with general 2027 ramp as 800v deployment takes off).
So once those ramp in 2027-2028, (markets tend to price things ahead of time), I'd expect $XFAB to be rerated based on growth opportunities.
TLDR:
- Current revenue numbers not as impressive.
- $XFAB confirmed direct exposure to CPO and 800V shifts (biggest win for thesis)
- 800V exposure opportunities for SiC (should be 2027)
- Timeline is 2028 ramp for photonics volume production
Happy exposure thesis to CPO/800V was confirmed from this ER. Might be a bit of waiting for revenue ramp.
翻译:
关于 $XFAB 收入报告的内容:
为了回顾一下,我之前关于 $XFAB 代工厂增长机会的想法源自于 SiC 在 800v 和 photonixfab/MTP 在 CPO 应用的潜力。
- $XFAB:”我们在共包光学方面取得了进展“。
- ”转向 800v... 预计将支持 SiC 和 GaN 对于 XFAB 的需求“
所以那些自信地发布负面信息关于 $XFAB 的分析师/人士,他们说
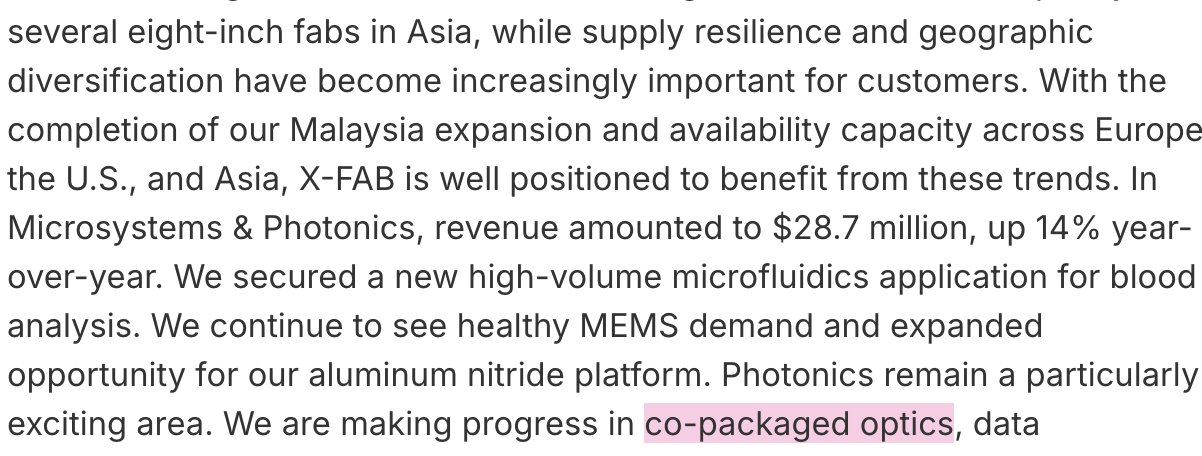
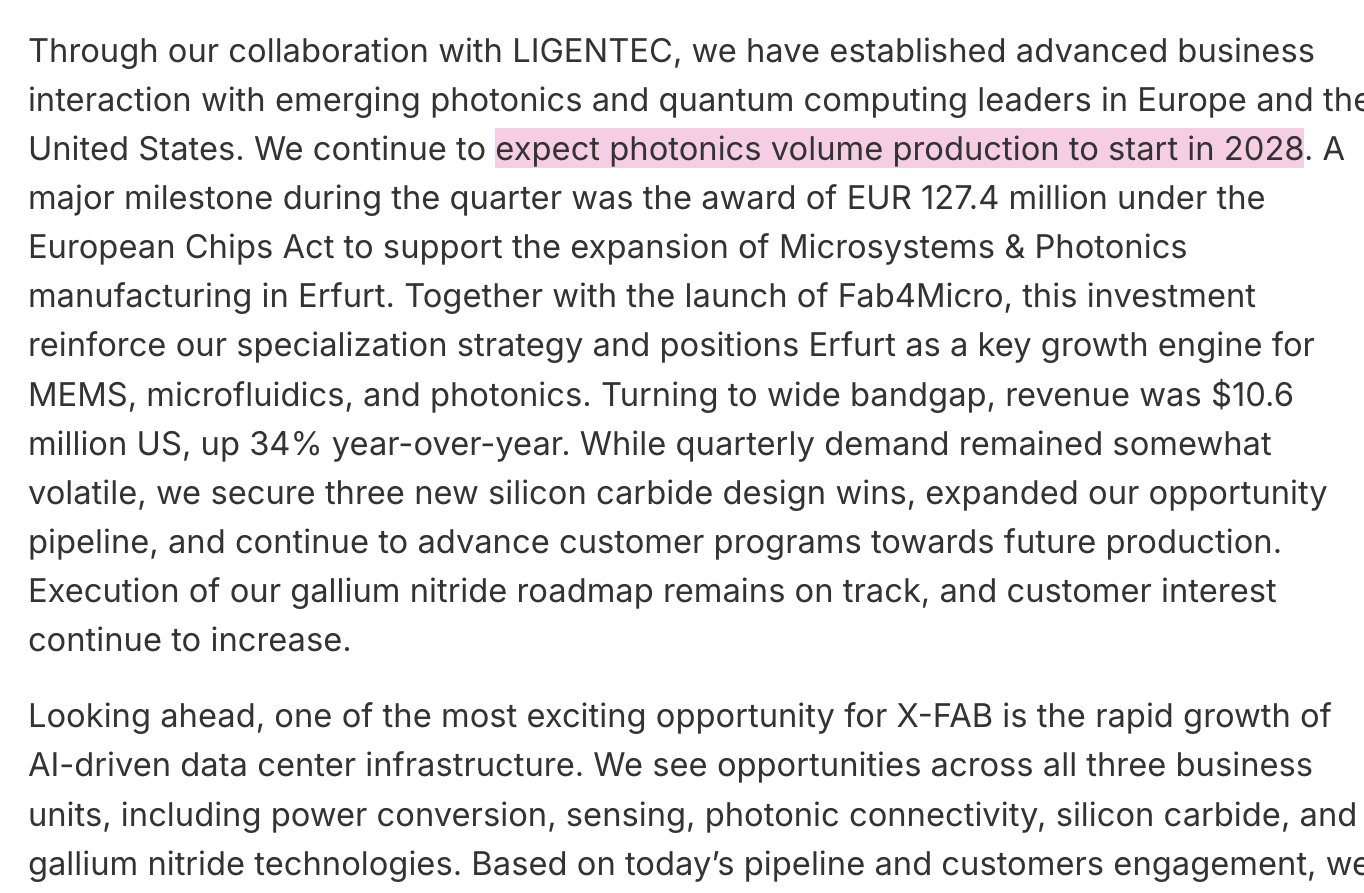
For $XFAB ER transcript:
Just to recap, my idea on $XFAB foundry growth opportunities stemmed from SiC for 800v and photonixfab/MTP for CPO applicability.
- $XFAB: "We are making progress in co-packaged optics".
- "The transition to 800v... is expected to support demand for both SiC and GaN... for XFAB"
So those analysts/people that were confidently bearposting about $XFAB that they had "0 exposure to 800V, photonics, CPO" just turned out plainly wrong.
At the time I shared my idea, industry materials showed ASE and others cited photonixfab + XFAB as an upcoming CPO player in EU. And filings showed they had exposure names like $NVTS / $POWI in general.
So glad $XFAB went out to explicitly clear things up to state they were developing in CPO/800v.
Okay back to the ER:
- "We continue to expect photonics volume production to start in 2028". Company currently has three silicon photonics projects in development with key partners.
I thought it would ramp sometime in H2 2027, but was probably early by a few months.
- Several new data center design wins, eg. 3 new SiC design wins (consistent with general 2027 ramp as 800v deployment takes off).
So once those ramp in 2027-2028, (markets tend to price things ahead of time), I'd expect $XFAB to be rerated based on growth opportunities.
TLDR:
- Current revenue numbers not as impressive.
- $XFAB confirmed direct exposure to CPO and 800V shifts (biggest win for thesis)
- 800V exposure opportunities for SiC (should be 2027)
- Timeline is 2028 ramp for photonics volume production
Happy exposure thesis to CPO/800V was confirmed from this ER. Might be a bit of waiting for revenue ramp.
翻译:
关于 $XFAB 收入报告的内容:
为了回顾一下,我之前关于 $XFAB 代工厂增长机会的想法源自于 SiC 在 800v 和 photonixfab/MTP 在 CPO 应用的潜力。
- $XFAB:”我们在共包光学方面取得了进展“。
- ”转向 800v... 预计将支持 SiC 和 GaN 对于 XFAB 的需求“
所以那些自信地发布负面信息关于 $XFAB 的分析师/人士,他们说
Comments
Unlock
$XFAB ”对 800V、光学、CPO 没有任何接触“,结果被证明是完全错误的。
当时我分享我的想法时,行业资料显示 ASE 和其他公司提到了 photonixfab + XFAB 作为欧洲即将到来的 CPO 玩家。并且文件显示他们在 $NVTS / $POWI 等公司中有接触。
很高兴 $XFAB 明确澄清了他们正在开发 CPO/800v。
好了,回到收入报告:
- ”我们预计光学的大规模生产将在 2028 年开始“。 公司目前与关键合作伙伴合作开发了三个硅光子项目。
我曾经认为它将在 2027 年下半年开始增长,但可能提前了几个月。
- 获得了多个新的数据中心设计订单,例如 3 个新的 SiC 设计订单(符合 2027 年 800v 部署开始时的增长趋势)。
所以,一旦这些订单在 2027-2028 年开始增长(市场往往会提前定价),我预计 $XFAB 将根据增长机会被重新评估。
总结:
- 目前的收入数字并不令人印象深刻。
- $XFAB 确认了直接接触 CPO 和 800V 转变(对我的论点来说是最大的胜利)
- 800V 接触机会为 SiC (应该在 2027 年)
- 时间表是 2028 年光学的大规模生产增长
很高兴我的关于 CPO/800V 的接触论点得到了这一收入报告的确认。可能需要等待一段时间才能看到收入增长。 🚀💡📈
Comments
Unlock
原文:
Few earnings TLDRs with my favorite $AXTI and $AMZN:
Amazon:
- Raised 2026 capex to $220B vs. prior $200B (partly due to higher memory costs, which is bullish on $MU to Samsung)
- Even at $220B, Amazon will not have enough capacity to meet all 2026 demand; Jassy expects the same in 2027.
- Most incoming 2027 capacity is already reserved, with substantial 2028 capacity also reserved.
Mostly read through on upstream semis. $GOOGL, $META, $AMZN, and $MSFT all identified compute shortage.
All the narratives a few weeks earlier was "excess compute" from Meta and others + hyperscalers cutting back on spend... All BS.
Amazon earnings was very bullish on AI semi trade.
AXTI:
- AXT to double InP capacity during 2026. Then double again in 2027.
This is expected to make AXT "by far the largest indium phosphide producer in the world." - LFG
- Q2 rev was $47.6M, the highest quarterly revenue in AXT history (InP revenue reached a record $30.7M, from DC applications.)
- Revenue increased 77% sequentially and 164% year over year.
- InP revenue-capacity targets: $60M per quarter exiting 2026.
- $130M per quarter exiting 2027
That $130m target could be hiked too since management stated they find "whatever ways to increase that capacity expansion"
- Management said the reported backlog remains well above $100M, but that number no longer reflects all available demand.
"Customer demand continues to outpace supply, no matter how fast we add capacity." 800G/1.6T is driving the current cycle, while NPO/CPO extends it beyond 2027.
Also they're targeting 50%-plus gross margin: "We should definitely be targeting a number that begins with a five."
China demand more than doubled, and their agreements with Casela, $COHR and $LITE did not materially drive Q2.
This is not even considering my projected massive ASP hikes yet as InP substrates get more bottlenecked.
TLDR:
-
Comments
Unlock
Amazon too much compute demands, needs capex to fufill it, so upstream semis go brrr.
- AXT world largest InP substrate supplier, high gross margins, expansion, and supply can't keep up with demand.
Bullish on demand side from Amazon + capex. Bullish on upstream optical supply chains from too much demand.
翻译:
以下是关于我最喜欢的 $AXTI 和 $AMZN 的几个收益要点:
亚马逊:
- 将 2026 年资本支出提高到 2200 亿美元,较之前的 2000 亿美元有所增加(部分原因是内存成本更高,这对 $MU 和三星来说是看涨的)
- 即使达到 2200 亿美元,亚马逊仍然无法满足 2026 年的全部需求;Jassy 预计 2027 年也会出现同样的情况
- 大部分即将到来的 2027 年产能已经被预订,2028 年的产能也已有大量预订
上游半导体公司基本上都看到了计算能力短缺。 $GOOGL、$META、$AMZN 和 $MSFT 都指出计算能力短缺。
几周前,大家都在说“过剩的计算能力”和超大规模公司削减支出……全部都是废话。
亚马逊的收益报告对人工智能半导体行业非常看涨。
AXTI:
- AXT 将在 2026 年期间将 InP 产能翻倍,然后在 2027 年再次翻倍。
- 这将使 AXT 成为“世界上最大的磷化铟生产商” - LFG
- 第二季度收入为 4760 万美元,创下 AXT 历史上最高的季度收入(InP 收入达到 3070 万美元的记录,来自 DC 应用)
- 收入按季度计算增加 77%,按年计算增加 164%。
- InP 收入产能目标:2026 年末每季度 6000 万美元。
- 2027 年末每季度 1.3 亿美元
由于管理层表示他们将“找到所有方法来增加产能扩张”,因此 1.3 亿美元的目标可能会进一步提高。
- 管理层表示,报告的订单积压仍然远远超过 1 亿美元,但这个数字不再反映所有可用的需求。
“客户需求继续超过供应,无论我们如何快速增加产能。”800G/1.6T 正在推动当前周期,而 NPO/CPO 将其延伸到 2027 年之后。
此外,他们的目标是实现 50% 以上的毛利率:“我们绝对应该瞄准一个以 5 开头的数字。”
中国的需求增加了一倍以上,他们与 Casela、$COHR 和 $LITE 的协议并没有显著推动第二季度的业绩。
这还没有考虑到 InP 基板变得更加瓶颈化时,我预计的巨大平均销售价格上涨。
总结:
- 亚马逊的计算需求过大,需要资本支出来满足,因此上游半导体公司将会大幅增长。
- AXT 是世界上最大的 InP 基板供应商,具有高毛利率、扩张和供不应求。
- 从亚马逊和资本支出方面看,需求端看涨。从过多的需求来看,上游光学供应链看涨。
Comments
Unlock
原文:
Did Citadel really just liquidate Situational Awareness…
Then brought up entire markets the next day?
$NBIS +26.25%
$IREN +25.96%
$SHAZ +22.82%
$SNDK + 23.98%
$BE +23.67%
$SKHY +16.98%
$INTC +12.16%
Amid many others. This has gotta be one of the wildest liquidations I’ve seen.
翻译:
城堡证券真的刚刚清算了态势感知……
然后第二天就拉升了整个市场?
$NBIS +26.25%
$IREN +25.96%
$SHAZ +22.82%
$SNDK + 23.98%
$BE +23.67%
$SKHY +16.98%
$INTC +12.16%
还有很多其他股票。这一定是我见过的最疯狂的清算之一。
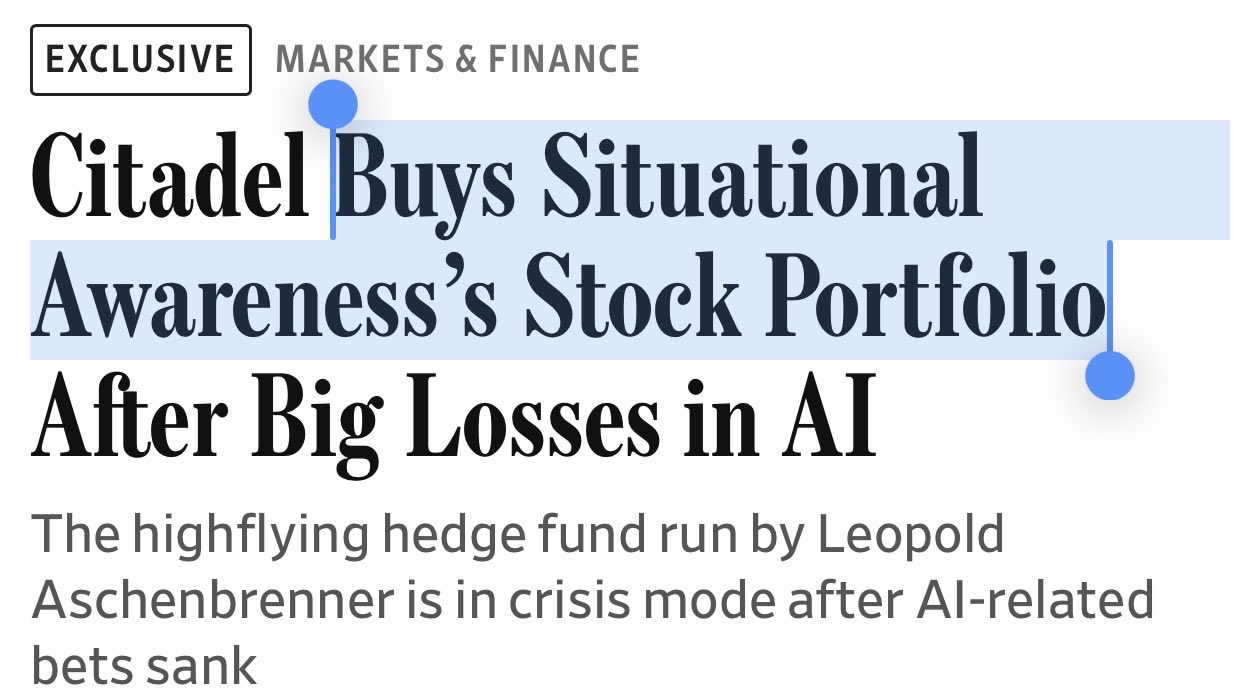
Did Citadel really just liquidate Situational Awareness…
Then brought up entire markets the next day?
$NBIS +26.25%
$IREN +25.96%
$SHAZ +22.82%
$SNDK + 23.98%
$BE +23.67%
$SKHY +16.98%
$INTC +12.16%
Amid many others. This has gotta be one of the wildest liquidations I’ve seen.
翻译:
城堡证券真的刚刚清算了态势感知……
然后第二天就拉升了整个市场?
$NBIS +26.25%
$IREN +25.96%
$SHAZ +22.82%
$SNDK + 23.98%
$BE +23.67%
$SKHY +16.98%
$INTC +12.16%
还有很多其他股票。这一定是我见过的最疯狂的清算之一。
Comments
Unlock
原文:
There's a lot of stupid commentary around Leopold raising funds. After names like $BE, $SNDK, $SHAZ, and others all had very sharp drawdowns in July.
Just remember... here's a man in finance that's
1. 6'5
2. Blue Eyes
3. Hedge Fund
Probably better looking than you, and was up 439% through June YTD.
Regarding the drawdown, Aschenbrenner acknowledged that the fund had "not been immune" to the market turmoil, particularly in Asia. FT separately reported that leverage amplified both its extraordinary gains and recent losses.
He described the sell-off as potentially the best buying opportunity since early 2025
I'd agree with him and hope he succeeds with the raise.
Since a lot of the current selloff looks like it overshot its mark through forced deleveraging.
翻译:
关于利奥波德筹集资金的议论有很多愚蠢的看法。像 $BE、$SNDK、$SHAZ 等名字在七月都经历了非常剧烈的回调。
只要记住……这是一个金融界的人,他是
1. 6'5
2. 蓝眼睛
3. 对冲基金
可能比你更好看,并且截至六月的年初至今收益率为 439%。
关于回调,阿申布伦纳承认该基金并非对市场动荡“免疫”,尤其是在亚洲。金融时报(FT)单独报道称,杠杆放大了其非凡的收益和最近的损失。
他将抛售描述为可能是自 2025 年初以来最好的买入机会。
我同意他的看法,并希望他能够成功筹集资金。
由于当前的抛售看起来像是由于强制去杠杆化而过度反应。
Comments
Unlock
Loading...