Comments
Unlock

觅信聚合
我的关注
原文:
哇,中国的 AI 视频生成能力可能已经是世界第一了吧?字节跳动的 Seedance 也太强了, 强到让我开始担心…
日本的动画师会不会很快就被 AI 取代?
但想象一下你可以随时生成新的剧情,让故事一直延续下去, 想看多久就看多久
这还挺酷的
翻译:
哇,中国的 AI 视频生成能力可能已经是世界第一了吧?字节跳动的 Seedance 也太强了,强到让我开始担心…
日本的动画师会不会很快就被 AI 取代?
但想象一下你可以随时生成新的剧情,让故事一直延续下去,想看多久就看多久
这还挺酷的
哇,中国的 AI 视频生成能力可能已经是世界第一了吧?字节跳动的 Seedance 也太强了, 强到让我开始担心…
日本的动画师会不会很快就被 AI 取代?
但想象一下你可以随时生成新的剧情,让故事一直延续下去, 想看多久就看多久
这还挺酷的
翻译:
哇,中国的 AI 视频生成能力可能已经是世界第一了吧?字节跳动的 Seedance 也太强了,强到让我开始担心…
日本的动画师会不会很快就被 AI 取代?
但想象一下你可以随时生成新的剧情,让故事一直延续下去,想看多久就看多久
这还挺酷的
Comments
Unlock
原文:
Some color on current memory environments for the $MU / $SKHY bros:
"There is zero risk of memory prices dropping" per Team Group GM Gerry Chen.
- Memory module makers have received notices warning of drastic cuts to their 2027 supply allocations. Some could receive 50% or less of their 2026 allocation.
- Upstream manufacturers have reportedly sold out nearly all of their 2027–2028 capacity.
- DDR5 supply, in particular, is projected to come in at less than 80% of previous expectations.
- Chen expects prices to continue rising 20–30% quarter-over-quarter into 2027 (source Digitimes)
- Chen's commentary on $MU is that even before their new MegaFab capacity comes online Q4 2027 at the earliest, orders for 2028 through 2029 are already fully booked.
So that there's virtually no relief in sight to current shortages.
Sharply lower allocations, fully booked capacity into 2029, and future price hikes doesn't quite sound like the AI buildout is slowing down.
翻译:
关于 $MU / $SKHY 兄弟们当前的内存环境,来点信息:
“内存价格绝不会下跌”,Team Group GM Gerry Chen 如是说。
- 内存模组厂商已收到通知,警告其 2027 年供应配额将被大幅削减。有的甚至只能拿到 2026 年配额的 50% 或更少。
- 上游制造商据称已几乎售罄 2027–2028 年的产能。
- DDR5 供应预计将低于此前预期的 80%。
- 陈预计价格将在 2027 年每季度环比上涨 20–30%(来源 Digitimes)。
- 陈对 $MU 的评论是,即使他们的新 MegaFab 产能最早要到 2027 年第四季度才上线,2028 至 2029 年的订单已经全部订满。
因此目前的短缺几乎没有缓解的迹象。
配额大幅削减、产能到 2029 年已订满、未来还会涨价,这听起来 AI 需求并没有放缓。
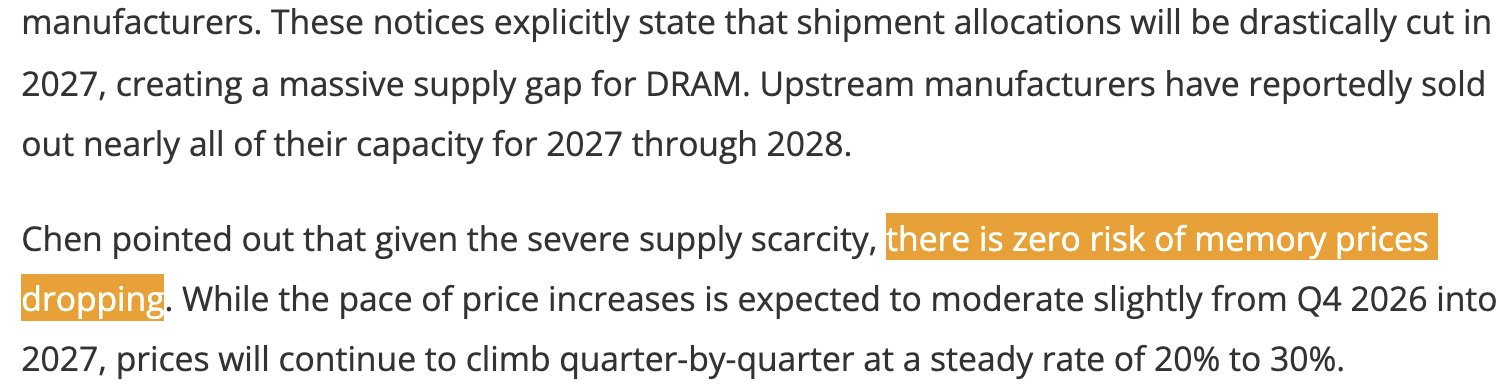
Some color on current memory environments for the $MU / $SKHY bros:
"There is zero risk of memory prices dropping" per Team Group GM Gerry Chen.
- Memory module makers have received notices warning of drastic cuts to their 2027 supply allocations. Some could receive 50% or less of their 2026 allocation.
- Upstream manufacturers have reportedly sold out nearly all of their 2027–2028 capacity.
- DDR5 supply, in particular, is projected to come in at less than 80% of previous expectations.
- Chen expects prices to continue rising 20–30% quarter-over-quarter into 2027 (source Digitimes)
- Chen's commentary on $MU is that even before their new MegaFab capacity comes online Q4 2027 at the earliest, orders for 2028 through 2029 are already fully booked.
So that there's virtually no relief in sight to current shortages.
Sharply lower allocations, fully booked capacity into 2029, and future price hikes doesn't quite sound like the AI buildout is slowing down.
翻译:
关于 $MU / $SKHY 兄弟们当前的内存环境,来点信息:
“内存价格绝不会下跌”,Team Group GM Gerry Chen 如是说。
- 内存模组厂商已收到通知,警告其 2027 年供应配额将被大幅削减。有的甚至只能拿到 2026 年配额的 50% 或更少。
- 上游制造商据称已几乎售罄 2027–2028 年的产能。
- DDR5 供应预计将低于此前预期的 80%。
- 陈预计价格将在 2027 年每季度环比上涨 20–30%(来源 Digitimes)。
- 陈对 $MU 的评论是,即使他们的新 MegaFab 产能最早要到 2027 年第四季度才上线,2028 至 2029 年的订单已经全部订满。
因此目前的短缺几乎没有缓解的迹象。
配额大幅削减、产能到 2029 年已订满、未来还会涨价,这听起来 AI 需求并没有放缓。
Comments
Unlock
原文:
I've seen comments from Jim Cramer today supporting hedge funds that short Leopold's "nonsense" $SNDK / $DRAM / SK Hynix type calls.
As well Cramer calling $CRWD a "Must Buy".
I'm not sure if Jim Cramer sees a $241B company labelled "Cybersecurity" and thinks of it as safe... while ignoring all their fundamentals.
But with Crowdstrike, you have a ~145x FY2028 fwd P/E company, growing revenue 26% Y/Y. That Cramer thinks is a "must buy".
And then you turn your eyes to the AI capex beneficiary theme that Leopold is long on.
With names like $SKHY / Samsung in $DRAM... Both FY2027 ~2.8-3x fwd P/E off analyst projections.
-> Samsung LTAs to 2031 (70% capacity) for durability... -> Minimum price floor + no price ceiling type contracts from SK Hynix.
-> Memory shortage much tigher for the next year.
-> DRAM/NAND % of hyperscaler capex goes higher (est. 68% per Trendforce)
-> 2027 hyperscaler capex projections all hiked.
Then with $SNDK, 50% FCF margins, 80% gross margin projections into 2030.
Only Situational Awareness position I'm in disagreement with is $CRWV due to debt interest eating FCF, but I can make a similar bullish argument with $BE, $INTC, $AMD, and others.
Not quite sure about short-term, but over the medium run:
It's hard to not see Leopold's positions pulling an Inverse Cramer due to overwhelming fundamentals.
翻译:
我今天看到 Jim Cramer 的评论,支持做空 Leopold 所谓的“胡说” $SNDK / $DRAM / SK Hynix 类股票的对冲基金。
Cramer 还把 $CRWD 称为“必买”。
我不确定 Jim Cramer 是否把一家市值 2410 亿美元、标榜为“网络安全”的公司视为安全……却忽视了它的基本面。
但 Crowdstrike 的市盈率约为 FY2028 前瞻 145 倍,收入同比增长 26%。Cramer 却认为它是“必买”。
再看 Leopold 持
Comments
Unlock
Loading...