原文:
Serenity 白毛女-中文翻译(公开)
Serenity 白毛女-中文翻译(公开)
原文:
So on optical vs. photonics... Memory like $MU / $SKHY is in it's current supercycle.
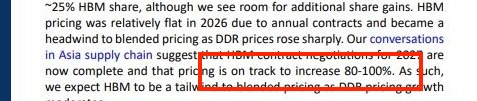
-> RBC channel checks for example projects 80-100% HBM ASP hikes for 2027.
-> Per $NVDA ER, Hyperscaler capex goes up in 2027. Then you have 68% of hyperscaler capex per Trendforce going to DRAM/NAND.
-> 50-70% for next 3-5 years already allocated toward LTAs.
So supercycle is here... demand visibility is high and the price hikes are still ongoing.
As photonics like $SMTC to $AAOI, I expect to cook heavily in 2027 since we're already seeing widespread optical shortages in 2026.
Plus, you're going from $67.7B in 2026 (per GS) to $131.4B TAM in 2027 for optical modules...
Which impacts the DSPs/TIAs/lasers/fiber suppliers before CPO scale up really takes off in 2028.
I don't think we'll ever see the same scale of memory price hikes, but I do think there's a lot room for more for MC growth in optical supply chains (given smaller starting point eg. $1B CW laser supplier vs $1T memory maker).
But still there's room for price hikes on laser content (eg. $15–$20 for 4 70 mW lasers per GS note) since starting point is really cheap... and one component, like cheap InP substrates can break hundreds of billions worth of supply chains downstream.
We're already seeing laser price hikes tho from CIOE channel checks confirmed by both Innolight / $SIVE from the Serenity's follower channel checks.
So entering uncharted territory.
TLDR: Messy thought but, memory has near term earnings power, midst of current supercycle.
The next "memory" ASP hikes I'm seeing is clearly legacy memory (DDR2/DDR3/SLC NAND) from cascading bottlenecks. It just looks to be an extension of the memory theme.
Maybe MLCC looks similar in terms of earlier cycles.
If we were to track supercycle impact on the supply chain in the space...
I'm confident next thematic one looks to be photonics
So on optical vs. photonics... Memory like $MU / $SKHY is in it's current supercycle.
-> RBC channel checks for example projects 80-100% HBM ASP hikes for 2027.
-> Per $NVDA ER, Hyperscaler capex goes up in 2027. Then you have 68% of hyperscaler capex per Trendforce going to DRAM/NAND.
-> 50-70% for next 3-5 years already allocated toward LTAs.
So supercycle is here... demand visibility is high and the price hikes are still ongoing.
As photonics like $SMTC to $AAOI, I expect to cook heavily in 2027 since we're already seeing widespread optical shortages in 2026.
Plus, you're going from $67.7B in 2026 (per GS) to $131.4B TAM in 2027 for optical modules...
Which impacts the DSPs/TIAs/lasers/fiber suppliers before CPO scale up really takes off in 2028.
I don't think we'll ever see the same scale of memory price hikes, but I do think there's a lot room for more for MC growth in optical supply chains (given smaller starting point eg. $1B CW laser supplier vs $1T memory maker).
But still there's room for price hikes on laser content (eg. $15–$20 for 4 70 mW lasers per GS note) since starting point is really cheap... and one component, like cheap InP substrates can break hundreds of billions worth of supply chains downstream.
We're already seeing laser price hikes tho from CIOE channel checks confirmed by both Innolight / $SIVE from the Serenity's follower channel checks.
So entering uncharted territory.
TLDR: Messy thought but, memory has near term earnings power, midst of current supercycle.
The next "memory" ASP hikes I'm seeing is clearly legacy memory (DDR2/DDR3/SLC NAND) from cascading bottlenecks. It just looks to be an extension of the memory theme.
Maybe MLCC looks similar in terms of earlier cycles.
If we were to track supercycle impact on the supply chain in the space...
I'm confident next thematic one looks to be photonics
Could not load this section.