原文:
Serenity 白毛女-中文翻译(公开)
Serenity 白毛女-中文翻译(公开)
原文:
Just as a thought... I think $NBIS is the best example of high-beta "speculative" growth companies that emerged a winner.
And there's some lessons learned applying concepts to $AAOI to $SIVE + other inflection type players in 2027.
So story time:
1. I wrote my thesis on Neoclouds in 2025, since I saw them as being $NVDA way to diversify away from hyperscaler AI Clouds.
2. As such, I went long on $WULF, $CIFR, $IREN, $NBIS, $BRUN, and the colo/neocloud ecosystem.
3. But eventually I decided to consolidate Neocloud positions into Nebius, since I found them to be the winner for nuanced reasons with financing/sum-of-parts/moats/deals.
Lot people got mad at me then, especially with $IREN, but all good now cause I own 2 shares.
4. What blew me away was Nebius $17B-$19B deals with $MSFT, their 2025 $3B deal $META (now ~$27B), and diversified customer base.
But... it was a 1 year waiting period for their Q4 2026 inflection period, where Nebius projected $7-9B ARR runrate...
5. The institutional % holding of Nebius was extremely low back then... maybe ~30%'s and was popular among retail.
6. But I had conviction that Nebius would be repriced eventually into Q4 2026 and institutions would increase their holdings off retail favored longs, like they did with $HOOD and others.
7. Despite all of their revenue inflection visibility and hyperscaler deals... $NBIS still tanked to $70, and was targeted by short sellers (eg. Hedgeye + others), especially around December.
8. There was a several month type lull period between November to March... where it ping ponged between $80 to $110, despite the company improving fundamentally.
9. And there was a lot of other media fears from $ORCL leaks about Neocloud profitability, Stargate buildout, GPU depreciation, etc. that caused panic.
10. But despite that... Institutional holding grew to around 67% from 30%'s.
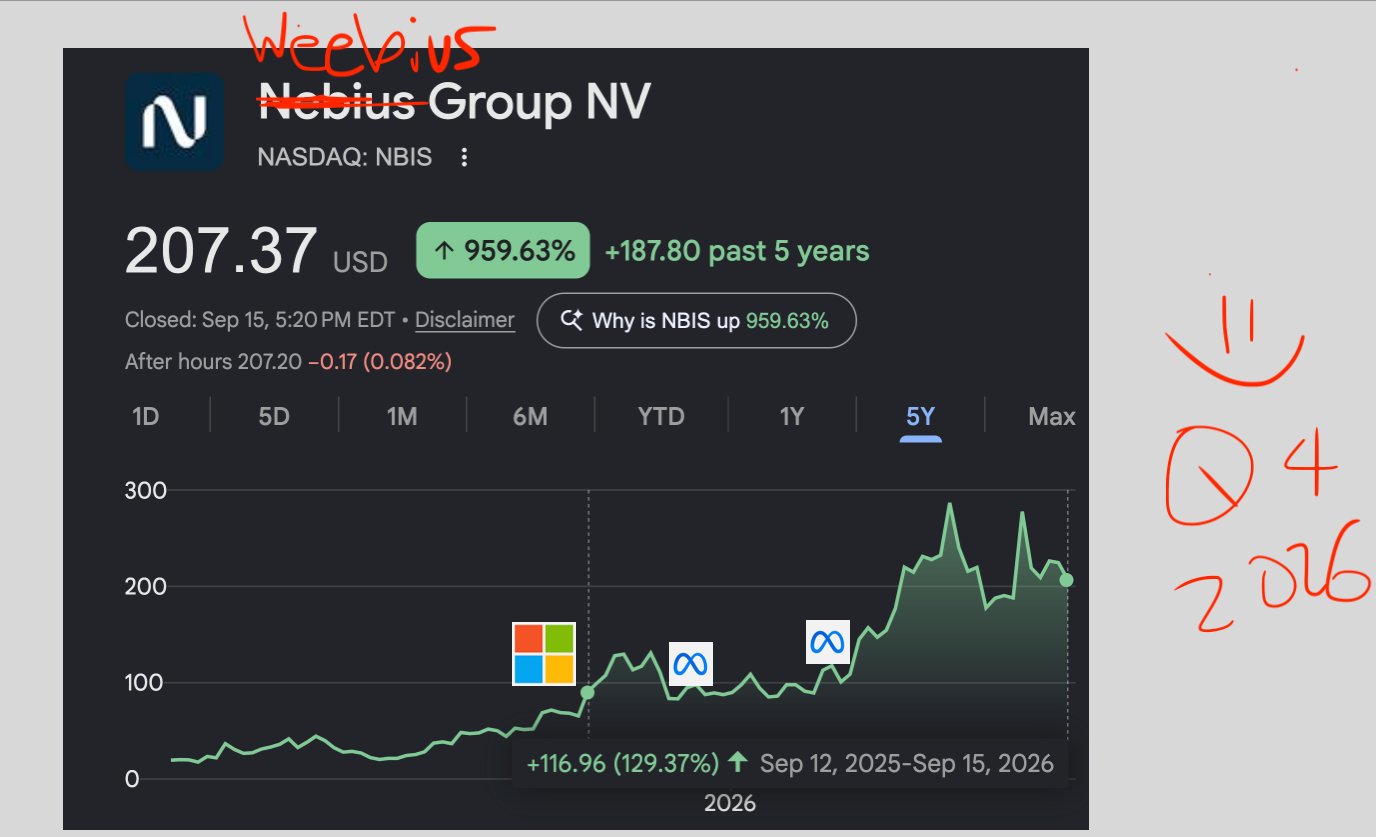
Just as a thought... I think $NBIS is the best example of high-beta "speculative" growth companies that emerged a winner.
And there's some lessons learned applying concepts to $AAOI to $SIVE + other inflection type players in 2027.
So story time:
1. I wrote my thesis on Neoclouds in 2025, since I saw them as being $NVDA way to diversify away from hyperscaler AI Clouds.
2. As such, I went long on $WULF, $CIFR, $IREN, $NBIS, $BRUN, and the colo/neocloud ecosystem.
3. But eventually I decided to consolidate Neocloud positions into Nebius, since I found them to be the winner for nuanced reasons with financing/sum-of-parts/moats/deals.
Lot people got mad at me then, especially with $IREN, but all good now cause I own 2 shares.
4. What blew me away was Nebius $17B-$19B deals with $MSFT, their 2025 $3B deal $META (now ~$27B), and diversified customer base.
But... it was a 1 year waiting period for their Q4 2026 inflection period, where Nebius projected $7-9B ARR runrate...
5. The institutional % holding of Nebius was extremely low back then... maybe ~30%'s and was popular among retail.
6. But I had conviction that Nebius would be repriced eventually into Q4 2026 and institutions would increase their holdings off retail favored longs, like they did with $HOOD and others.
7. Despite all of their revenue inflection visibility and hyperscaler deals... $NBIS still tanked to $70, and was targeted by short sellers (eg. Hedgeye + others), especially around December.
8. There was a several month type lull period between November to March... where it ping ponged between $80 to $110, despite the company improving fundamentally.
9. And there was a lot of other media fears from $ORCL leaks about Neocloud profitability, Stargate buildout, GPU depreciation, etc. that caused panic.
10. But despite that... Institutional holding grew to around 67% from 30%'s.
Could not load this section.