原文:
Serenity 白毛女-中文翻译(公开)
Serenity 白毛女-中文翻译(公开)
原文:
I'll let you decide that for yourself since that was an illustrative laser revenue modeling off $SIVE 100M CW DFB laser/year target.
But... do you want to know the main reason I like laser companies so much?
They don't just have to stay laser companies... just look at $LITE!
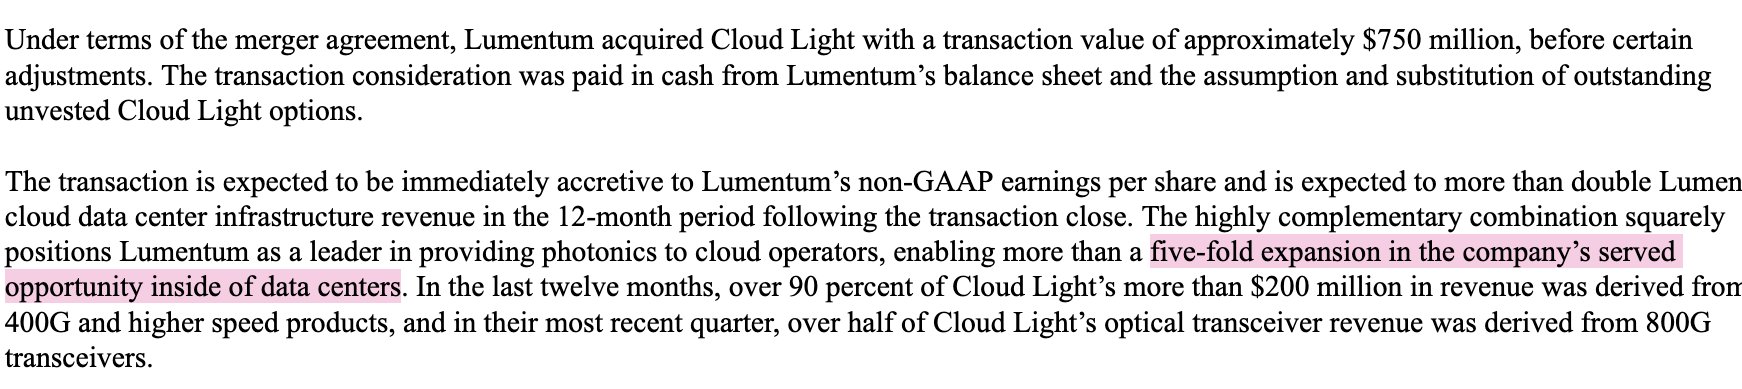
If we look at Lumentum's previous Cloud Light acqusition (pluggables)... it enabled:
- more than a 5X+ expansion in served opportunity inside DCs.
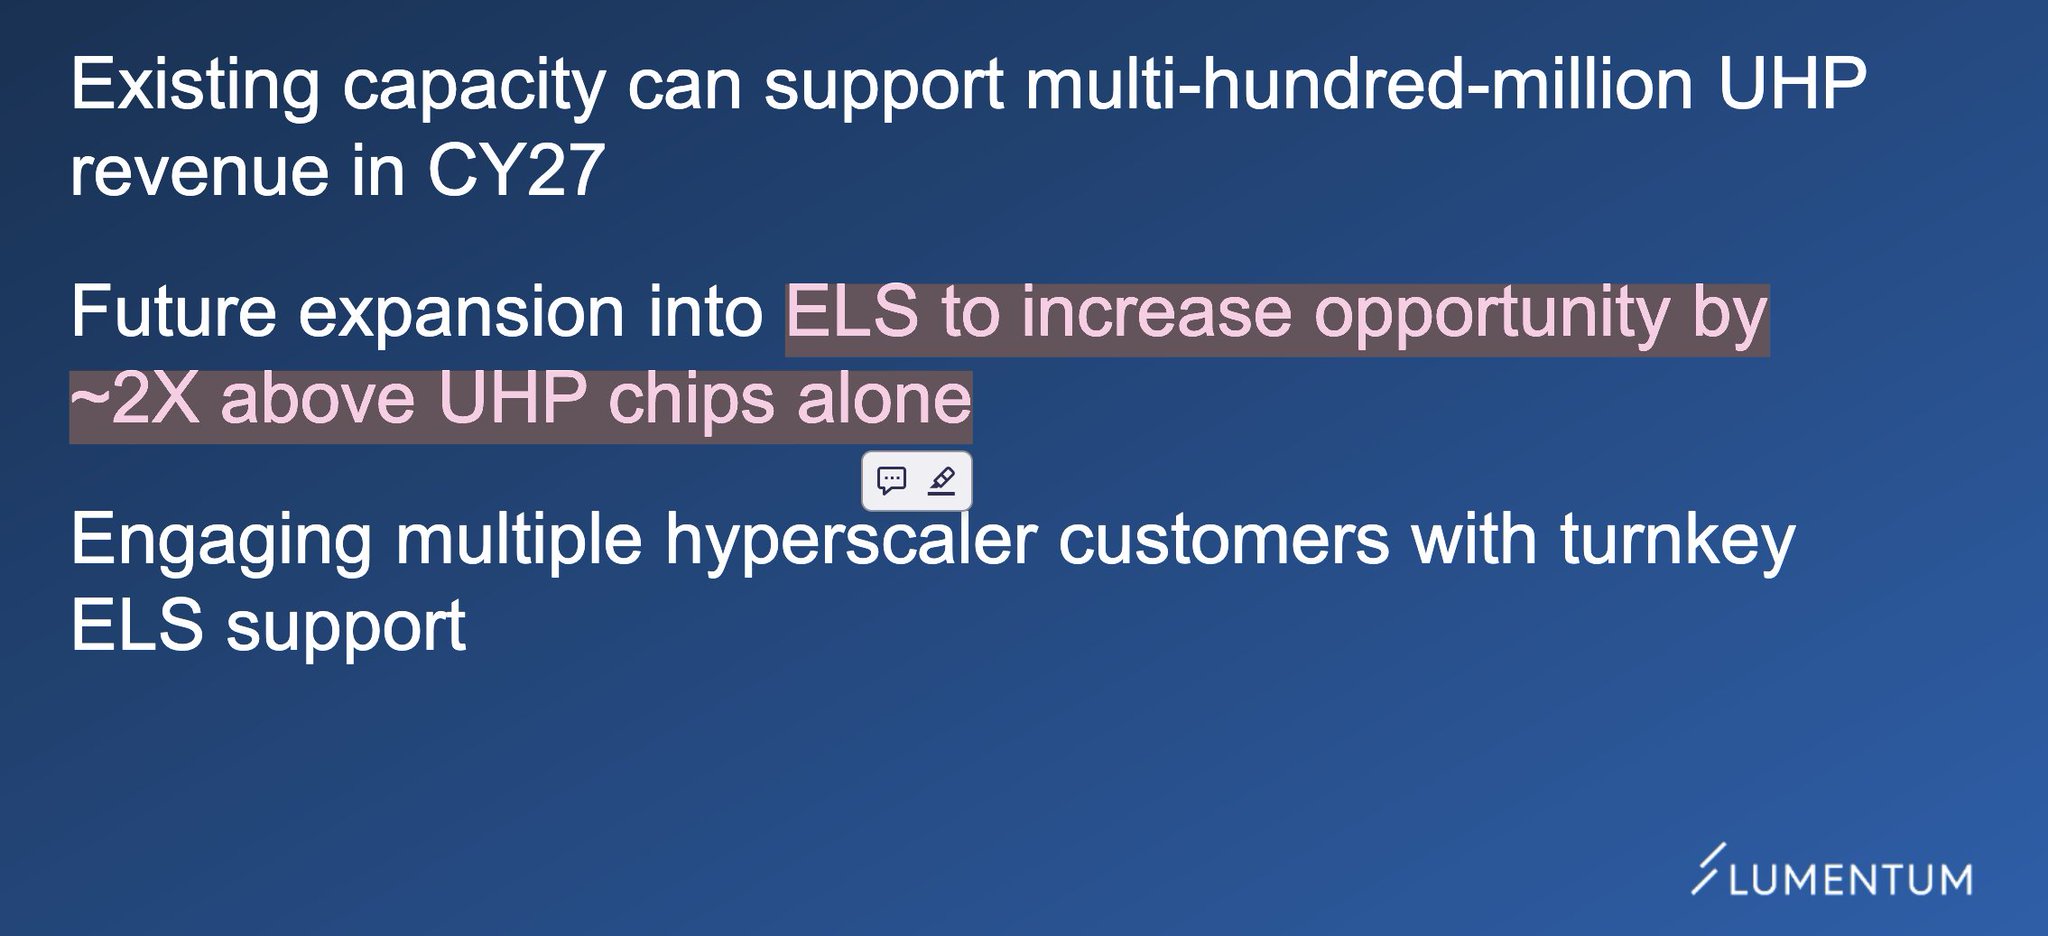
From Lumentum's OFC deck:
- ELS expansion from UHP laser chips was 2X TAM opportunity..
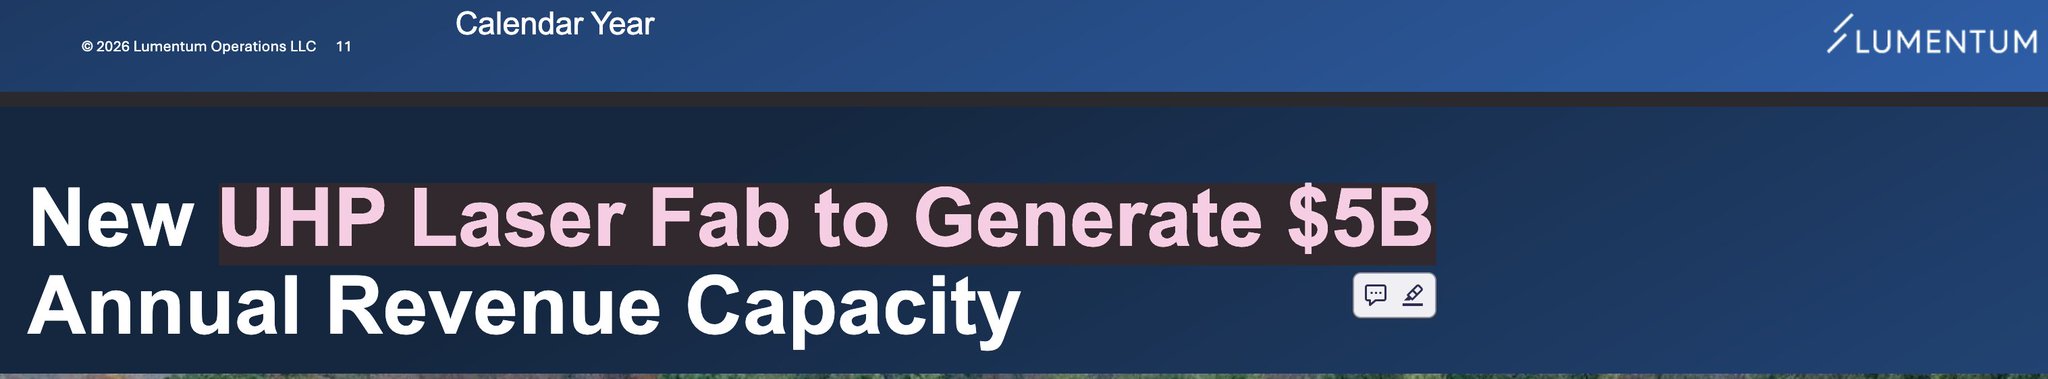
But selling lasers alone... just from one UHP laser fab was $5B in projected revenue capacity (their fab expected to ramp in early 2028), if we apply similar 55-65% CPO laser margin quotes by $AAOI.
So lasers by itself is very profitable, and despite industry capacity expansion, there would likely still be a demand imbalance for lasers.
Isn't that pretty cool?
So it's not quite just modeling component value for certain types of companies since they can keep growing into other products.
And you have new overlapping cycles eg. NPO/CPO/1.6T pluggables increasing demand.
So I'd personally assign higher premiums for laser companies over types of suppliers that stay in the same layer.
翻译:
我就让你自行判断,因为那是基于 $SIVE 每年 1 亿 CW DFB 激光的示例性收入模型。
不过……你想知道我如此喜欢激光公司的主要原因吗?
它们不一定只能做激光公司……只要看看 $LITE!
如果我们回顾 Lumentum 之前的 Cloud Light 收购(可插拔),它实现了:
- 在数据中心内部的服务机会扩大了超过 5 倍。
根据 Lumentum 的 OFC 演示文稿:
- 来自 UHP 激光芯片的 ELS 扩展带来了 2 倍的 TAM 机会。
但仅销售激光……仅一家 UHP 激光工厂的预计收入规模就达 50 亿美元(该工厂预计在 2028 年初投产),如果采用 $AAOI 给出的 55%‑65% CPO 激光利润率。
因此激光本身非常盈利,尽管行业产能在扩张,激光需求仍可能出现供不应求的失衡。
这不是很酷吗?
所以这不仅仅是对某类公司的组件价值建模,因为它们可以不断向其他产品扩展。
而且还有新的叠加周期,例如 NPO/CPO/1.6T 可插拔产品提升需求。
因此我个人会给激光公司更高的溢价,而不是那些停留在同一层级的供应商。
I'll let you decide that for yourself since that was an illustrative laser revenue modeling off $SIVE 100M CW DFB laser/year target.
But... do you want to know the main reason I like laser companies so much?
They don't just have to stay laser companies... just look at $LITE!
If we look at Lumentum's previous Cloud Light acqusition (pluggables)... it enabled:
- more than a 5X+ expansion in served opportunity inside DCs.
From Lumentum's OFC deck:
- ELS expansion from UHP laser chips was 2X TAM opportunity..
But selling lasers alone... just from one UHP laser fab was $5B in projected revenue capacity (their fab expected to ramp in early 2028), if we apply similar 55-65% CPO laser margin quotes by $AAOI.
So lasers by itself is very profitable, and despite industry capacity expansion, there would likely still be a demand imbalance for lasers.
Isn't that pretty cool?
So it's not quite just modeling component value for certain types of companies since they can keep growing into other products.
And you have new overlapping cycles eg. NPO/CPO/1.6T pluggables increasing demand.
So I'd personally assign higher premiums for laser companies over types of suppliers that stay in the same layer.
翻译:
我就让你自行判断,因为那是基于 $SIVE 每年 1 亿 CW DFB 激光的示例性收入模型。
不过……你想知道我如此喜欢激光公司的主要原因吗?
它们不一定只能做激光公司……只要看看 $LITE!
如果我们回顾 Lumentum 之前的 Cloud Light 收购(可插拔),它实现了:
- 在数据中心内部的服务机会扩大了超过 5 倍。
根据 Lumentum 的 OFC 演示文稿:
- 来自 UHP 激光芯片的 ELS 扩展带来了 2 倍的 TAM 机会。
但仅销售激光……仅一家 UHP 激光工厂的预计收入规模就达 50 亿美元(该工厂预计在 2028 年初投产),如果采用 $AAOI 给出的 55%‑65% CPO 激光利润率。
因此激光本身非常盈利,尽管行业产能在扩张,激光需求仍可能出现供不应求的失衡。
这不是很酷吗?
所以这不仅仅是对某类公司的组件价值建模,因为它们可以不断向其他产品扩展。
而且还有新的叠加周期,例如 NPO/CPO/1.6T 可插拔产品提升需求。
因此我个人会给激光公司更高的溢价,而不是那些停留在同一层级的供应商。
Could not load this section.